Head of Credits

• 四半期アウトルック
Higher bond yields in an era of abundant supply
Fixed income outlook
Higher yields have strengthened the case for fixed income, even as abundant bond supply, inflation and tight spreads complicate the outlook. Our first integrated Fixed Income Quarterly Outlook brings together Robeco’s macro, rates and credit views to explore where opportunities remain and why selectivity matters.
執筆者

Head of Global Macro and Portfolio Manager
CIO High Yield, Portfolio Manager
Head of Emerging Markets Debt
まとめ
- High starting yields provide a strong base for future fixed income returns
- Higher rates are increasing pressure on risk assets and leveraged borrowers
- AI investment and rising issuance are reshaping fixed income markets
AI is usually discussed as a technology or equity market story. For fixed income investors, however, it is increasingly becoming a supply story. Consensus expectations for hyperscaler capital expenditure in 2027 now exceed USD 1 trillion, while expected bond issuance from the largest technology companies has risen sharply as more of that investment is financed through debt.
The funding requirement also extends well beyond the hyperscalers. Data centers require a substantial and reliable supply of electricity, drawing utilities and grid operators into the same investment cycle. As this infrastructure expands, financing needs are spreading across the wider AI ecosystem.
Higher yields have strengthened the case for fixed income, but this is not a market for large directional bets
Understanding fixed income
Fixed income forms the stable core of a portfolio, providing regular income and capital return.
This new corporate borrowing arrives at a time when governments and supranational issuers already have substantial funding requirements. Fiscal deficits remain large and sovereign issuance is elevated, while public investment needs are growing. This means governments, technology companies and utilities are increasingly competing for the same pool of long-term capital.
This represents a reversal from recent years, when companies borrowed less, shortened maturities and reduced net issuance in response to higher rates. Limited bond supply, combined with persistent investor demand, provided powerful technical support for credit spreads. That scarcity is now giving way to greater bond abundance.
For investors, greater supply is not simply a risk. It should also create more choice and potentially better entry points into high-quality issuers. But it strengthens the case for active selection across sectors, maturities and currencies rather than relying on scarcity to keep spreads compressed.
Table 1 - Fixed income views at a glance
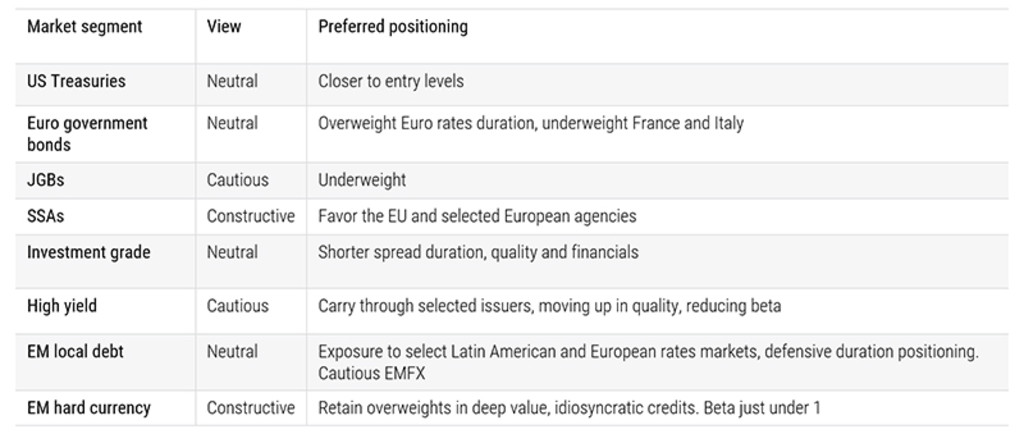
For illustrative purposes only. This is the current overview as of the date stated above and not a guarantee of future developments. It should not be assumed that any investments in sectors/markets/regions/themes/market cap/country identified were or will be profitable.
Source: Robeco, October 2026
For our detailed views on rates, credit and emerging market debt, including the developments that could make us more constructive, read the full Fixed Income Quarterly Outlook, or explore the key messages and positioning implications in Fixed Income Quarterly Outlook in Brief.
クレジットの最新動向は?
クレジット運用の最新情報を先取りするニュースレター(英文)に登録しましょう。
重要事項
当資料は情報提供を目的として、ロベコ・ジャパン株式会社(以下「当社」)が独自に作成、または当社のグループ会社(Robeco Institutional Asset Management B.V.およびその関連会社を含む)から提供された資料を当社が編集・翻訳したものです。資料中の個別の金融商品の売買の勧誘や推奨等を目的とするものではありません。記載された情報は十分信頼できるものであると考えておりますが、その正確性、完全性を保証するものではありません。意見や見通しはあくまで作成日における弊社の判断に基づくものであり、今後予告なしに変更されることがあります。運用状況、市場動向、意見等は、過去の一時点あるいは過去の一定期間についてのものであり、過去の実績は将来の運用成果を保証または示唆するものではありません。また、記載された投資方針・戦略等は全ての投資家の皆様に適合するとは限りません。当資料は法律、税務、会計面での助言の提供を意図するものではありません。 ご契約に際しては、必要に応じ専門家にご相談の上、最終的なご判断はお客様ご自身でなさるようお願い致します。 運用を行う資産の評価額は、組入有価証券等の価格、金融市場の相場や金利等の変動、及び組入有価証券の発行体の財務状況による信用力等の影響を受けて変動します。また、外貨建資産に投資する場合は為替変動の影響も受けます。運用によって生じた損益は、全て投資家の皆様に帰属します。したがって投資元本や一定の運用成果が保証されているものではなく、投資元本を上回る損失を被ることがあります。弊社が行う金融商品取引業に係る手数料または報酬は、締結される契約の種類や契約資産額により異なるため、当資料において記載せず別途ご提示させて頂く場合があります。具体的な手数料または報酬の金額・計算方法につきましては弊社担当者へお問合せください。 当資料及び記載されている情報、商品に関する権利は弊社に帰属します。したがって、弊社の書面による同意なくしてその全部もしくは一部を複製またはその他の方法で配布することはご遠慮ください。 商号等: ロベコ・ジャパン株式会社 金融商品取引業者 関東財務局長(金商)第2780号 加入協会: 一般社団法人 資産運用業協会