
Sector Lead

• 市場觀點
Energy security: How AI and electrification are driving infrastructure investment
Robeco’s lead Energy and Utilities sector analyst, Farahnaz Pashaei Kamali, argues that energy security is evolving beyond access to affordable oil and gas. It now increasingly depends on the resilience of the networks, infrastructure, trade routes, supply chains and raw materials that underpin the global energy system.
概要
- Geopolitical shocks have re-focused energy security from cost efficiency to system resilience
- AI and electrification are powerful catalysts for energy system investments
- Resilience spending supports infrastructure, hard assets and commodities in portfolio allocations
Pashaei Kamali labels this evolution as ‘Energy Security 2.0’ and characterizes the transition as a shift from a ‘just-in-time’ globalized system toward a more resilient ‘just-in-case’ model. In this new era, governments and corporations are prioritizing strategic reserves, backup capacity, diversification and strategic autonomy over pure efficiency optimization. For investors, this shift matters because resilience is becoming an increasingly important driver of capital expenditure, earnings visibility and long-term returns.
Energy Security 2.0 is a transition from a ‘just-in-time’ globalized system toward a more resilient ‘just-in-case’ model Farahnaz Pashaei Kamali
Farahnaz Pashaei Kamali
Sector Lead
Recent geopolitical shocks have accelerated this transition. Europe’s energy crisis following the loss of Russian gas supply exposed the macroeconomic costs of concentrated dependencies. More recently, tensions in the Middle East and disruptions around the Strait of Hormuz and Bab el-Mandeb have highlighted the vulnerability of global shipping lanes and energy chokepoints.
In parallel, artificial intelligence (AI), industrial reshoring, and electrification trends are accelerating the need for dependable power systems, creating a new phase of capital investments across grids, storage, generation and energy infrastructure. The result is a structural repricing of resilience, redundancy and dependable energy systems after decades in which efficiency dominated corporate and policy decision-making.
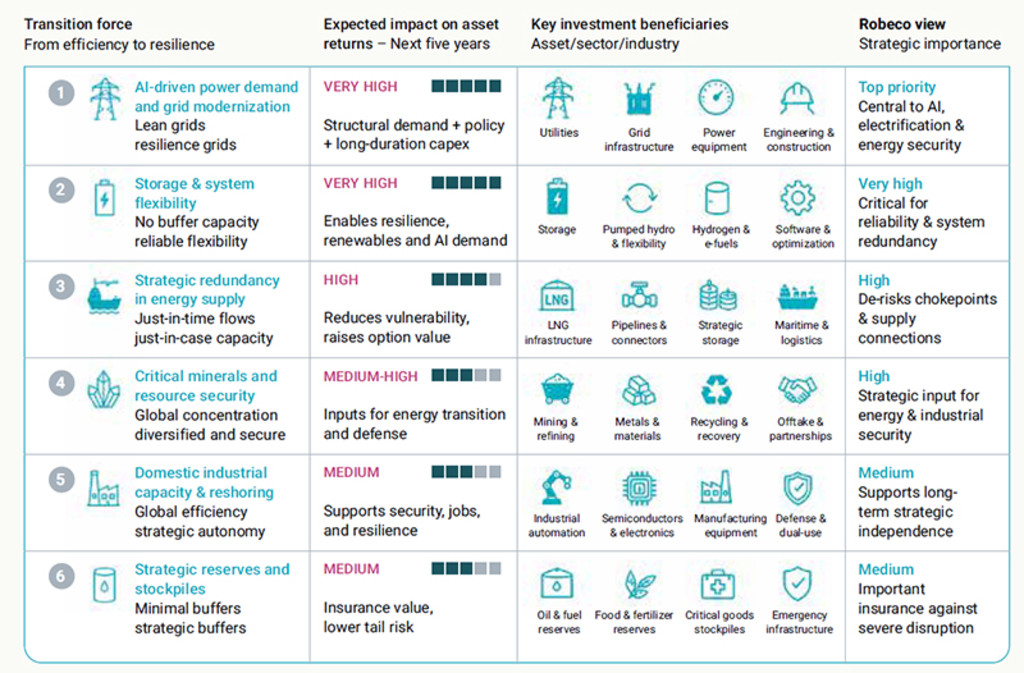
Figure 1: The structural shift from efficiency to resilience
Source: McKinsey Global Institute, Morgan Stanley Research, Robeco, June 2026.
Note: The estimated impact reflects our assessment of the potential effect on asset class returns over the next five years.
Power security becomes the new energy security
Historically, energy markets were characterized by globally integrated trade flows that optimized efficiency and minimized costs. Yet energy insecurity is often experienced locally. The Strait of Hormuz, Bab el-Mandeb and the Suez Canal remain critical chokepoints for oil, LNG and broader commodity trade. Building resilience is inherently more capital-intensive than efficiency. Strategic reserves, redundant infrastructure, domestic manufacturing and grid reinforcement require substantial investment. As this continues to play out, the disinflationary impulse associated with established trade routes and globalization is likely to weaken and inflation volatility may remain structurally higher.
AI-driven electricity demand and grid modernization are acting as powerful catalysts in this process and appear likely to have the greatest impact on asset returns over the next five years because they combine structural demand growth with strong policy support and long-duration investment requirements. This should support the strategic role of not only oil and other commodities but also infrastructure and real assets within diversified portfolios.
Governments globally are investing in resilience
Governments and corporations are increasingly responding through investments in strategic infrastructure. The IEA also estimates that global energy investment has already surpassed USD 3 trillion annually, which likely understates the real investment need. Natural gas, LNG infrastructure, nuclear power, storage systems, and transmission networks will be the primary beneficiaries of capital deployment.
Because capital expenditure remains highly selective, and because investment in upstream oil and gas and parts of the commodity supply chain has lagged projected demand growth, spare capacity in several key markets will remain limited. This increases the probability of supply-driven price shocks.
獲取最新市場觀點
訂閱我們的電子報,時刻把握投資資訊和專家分析。
Sovereignty and security in the age of AI
Over the next five years, energy security will increasingly be defined as power security. As transport, heavy industry, and data systems electrify, power shortages transform from localized disruptions into systemic macroeconomic risks. AI serves as the primary structural accelerator of this trend. AI data centers are exceptionally energy-intensive and forward-looking estimates indicate that future AI-related infrastructure investment could rival or exceed traditional energy investment in the years ahead.
Over the next five years, energy security will increasingly be defined as power security Farahnaz Pashaei Kamali
Farahnaz Pashaei Kamali
Sector Lead
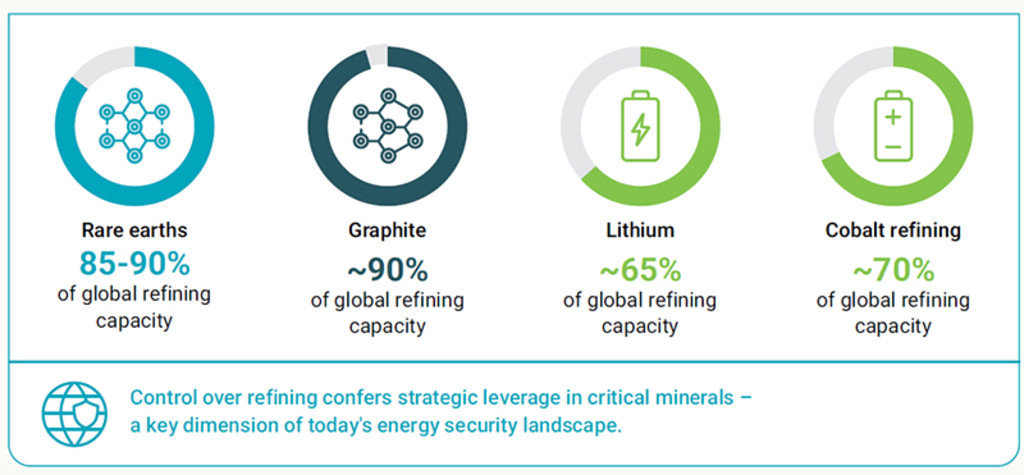
Renewable generation alone cannot bridge this compounding demand gap. This structural demand deficit cements the long-term cash-flow visibility and return profiles of regulated grids, battery storage, and dispatchable generation. Grid infrastructure, in particular, will benefit from strong political support, higher regulated returns, and robust earnings visibility as utilities race to solve emerging bottleneck constraints. Modern energy systems are underpinned by copper, lithium, graphite, nickel and rare earth elements, supply chains where China plays a dominant role.
Figure 2: Global critical-mineral processing remains highly concentrated
Source: IEA Critical Minerals Outlook, USGS, May 2025.
As a result, governments are placing greater emphasis on domestic mining, strategic reserves, recycling technologies and friendshoring arrangements. Hence, commodities, technology sovereignty and energy security are increasingly intertwined.
The implications of Energy Security 2.0 differ materially across regions. The US appears relatively well positioned due to abundant domestic energy resources, expanding LNG export capacity and deep industrial ecosystems. Europe remains more vulnerable from an import perspective, although recent shocks have accelerated investment in LNG infrastructure, renewables and storage. Asia faces the greatest exposure to imported energy flows, but also represents the largest source of future investment growth.
Figure 3: Ranking the highest conviction beneficiaries of Energy Security 2.0
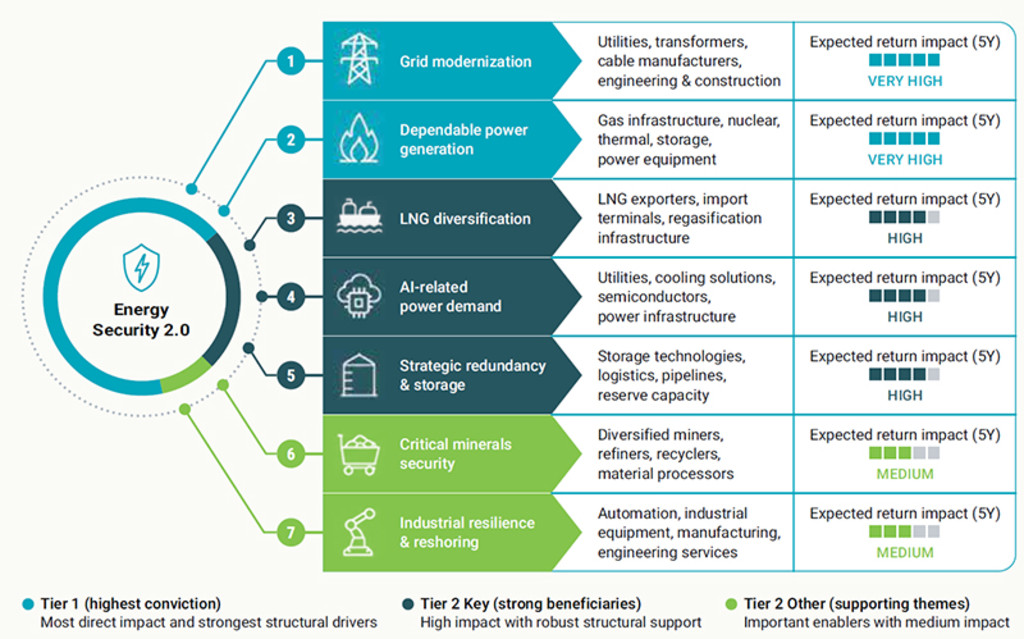
Source: Robeco, June 2026.
Note: Ranking reflects Robeco's assessment of the expected influence of each theme on asset and sector returns over the next five years.
Our base case, to which we assign a 50% probability, is a regime in which disruption effects dominate the supply-side benefits of resilience investment. Persistent geopolitical fragmentation, climate-related disruptions and strategic competition are likely to keep inflation more volatile, despite substantial investment aimed at strengthening energy and infrastructure resilience.
In this environment, we expect commodities and infrastructure to be the clearest beneficiaries, reflecting the increasing strategic value of secure energy supplies, critical resources and resilient infrastructure networks. The implications for equities are more mixed, as companies benefiting from higher resilience investment coexist with those facing higher input costs, financing costs and supply-chain pressures.
This article is an excerpt of a special topic in Robeco’s 5-year Expected Returns publication.
Expected Returns 2027-2031
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。