Portfolio Manager
獲取最新市場觀點
訂閱我們的電子報,時刻把握投資資訊和專家分析。



The valuation gap between Asia-Pacific and the US has narrowed, but we believe the trend is nascent. We believe this makes Asia-Pacific equities an appropriate allocation for investors seeking diversification from concentrated US exposure.
For investors seeking long-term diversification from an overweight position in the US, Asia-Pacific equities have a compelling investment thesis. The combination of macroeconomic strength, a broad sector mix, and long‑term structural drivers is starting to be recognized, with the region outperforming through 2025 and 2026.
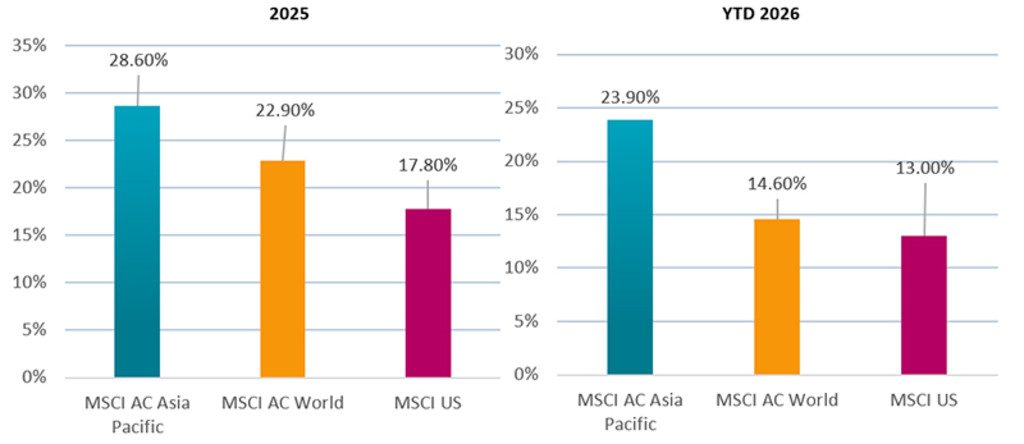
Past performance is no guarantee of future results. The value of your investments may fluctuate.
Source: MSCI, full year 2025 (left-hand chart), year to 31 August 2026 (right-hand chart). USD gross return
Shareholder-friendly governance reforms in markets such as Japan and Korea are improving return profiles, while India and ASEAN benefit from strong domestic demand and the multiplier effects of infrastructure and supply‑chain investment. The region also underpins global AI and energy transition manufacturing, supported by a solid spine of materials extraction and processing running through Australia, Indonesia and China.
Valuations provide a second important pillar for the Asia-Pacific investment thesis (see Figure 2). Earnings revisions across Asia-Pacific are turning positive, supported by corporate reforms, strengthening domestic demand and later cycle benefits from AI, infrastructure build-outs and higher defense spending. Dividend yields have also historically been more attractive in Asia, giving investors an additional component of total return.
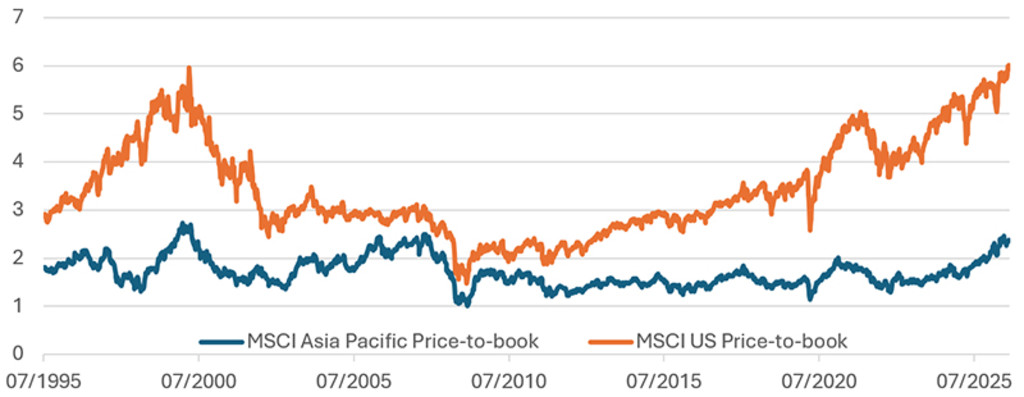
Past performance is no guarantee of future results. The value of your investments may fluctuate.
Source: Robeco, MSCI, 31 August 2026.
訂閱我們的電子報,時刻把握投資資訊和專家分析。
Asia ex-Japan remains a common institutional building block for allocating to the region, reflecting a long-standing practice of treating Japan as a separate allocation because of its large, liquid equity market and distinct economic profile. The MSCI AC Asia ex-Japan Index (USD gross return, 31 August 2026) is concentrated in North Asia: Taiwan represents 30.7%, Korea 23.3% and China 23.0%, so roughly three-quarters of the index is allocated to those three markets. By contrast, the MSCI AC Asia-Pacific Index (USD gross return, 31 August 2026) incorporates Japan and Australia alongside Asian emerging markets: Japan accounts for 29.6%, Taiwan 18.9%, Korea 14.4%, China 14.2%, Australia 8.4% and India 7.8%. The balance is spread across Hong Kong, Singapore, ASEAN markets
and New Zealand, resulting in a broader country mix.
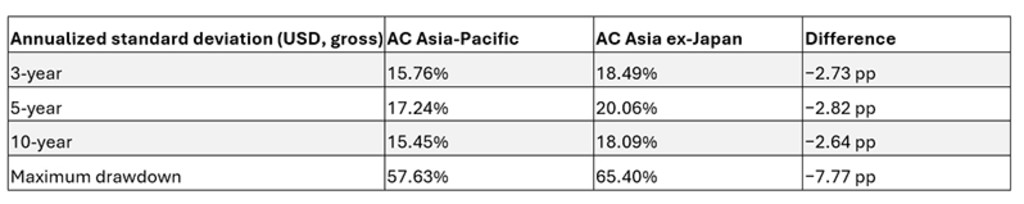
The indices also differ materially in sector composition and historical risk characteristics. Information technology represents 46.4% of Asia ex-Japan, compared with 33.9% of the broader Asia-Pacific index, reflecting Asia ex-Japan’s greater exposure to Taiwanese and Korean technology and semiconductor companies. That distinction may be relevant for investors assessing aggregate exposure to the global technology cycle, including alongside US equity holdings. The MSCI AC Asia-Pacific Index recorded annualized volatility more than two percentage points lower than the MSCI AC Asia ex-Japan Index over the three-, five- and ten-year periods, while its maximum drawdown was 7.77 percentage points smaller. These are historical differences rather than indications of future risk or return, and the appropriate benchmark depends on whether Japan and Australia are intended to sit within, or alongside, an investor’s Asia allocation.
Past performance is no guarantee of future results. The value of your investments may fluctuate.
Source: MSCI AC Asia-Pacific Index and MSCI AC Asia ex-Japan Index factsheets, 31 August 2026. Calculations are based on monthly gross USD returns.
Broad Asia-Pacific works as a diversifier for some investors because it blends developed and emerging exposure with genuinely different return drivers.
Japan’s domestic corporate governance reforms have helped re-rate Japan’s stock market in the past 2 years, but there is significant progress still to make. Pressure on sub-book-value companies has produced four consecutive record years of buybacks, with fiscal 2026 projected to surpass USD 100 billion1 and Corporate Governance Code reforms now pushing remuneration and capital-efficiency disclosures. Japan’s market breadth and depth have provided a great hunting ground for alpha opportunities, so our Asia-Pacific Equities strategy has consistently held an overweight position in Japan. Despite JPY weakness in the first half of 2026, our view remains that firmer inflation and ongoing policy normalization in Japan are supportive of a more balanced currency and interest-rate environment over time.
To complement North Asia’s dominance in industry and tech, Australia brings resources, financials and high-payout defensives: iron ore, copper, gold and lithium exposure that is tied to the commodity and energy-transition cycle, rather than purely tech, plus a governance culture that caters to long-term institutional investors.
Asia-Pacific’s emerging-market growth engine is not lost in the process. India's domestic consumption story, ASEAN's manufacturing relocation beneficiaries and Korea and Taiwan's technology leadership all remain present, simply at lower weights.
Asia-Pacific encompasses economies at very different stages of development, with varied growth rates, income levels, industry structures, cultures and currencies, creating a complex landscape rich in potential alpha. In such a diverse and heterogeneous region, we believe active management is advantageous.
Within the Asia-Pacific equities universe, we continue to identify companies whose share prices do not reflect their true potential. We seek to avoid overvalued growth stocks and value traps. On-the-ground research across Asia provides differentiated local insights that support a high-conviction, bottom-up portfolio with a high active share. By integrating valuation discipline, earnings momentum and a long-term investment horizon, the strategy seeks to generate differentiated alpha across market cycles.
With exposure to fast growing economies and a blend of developed and emerging markets, we continue to believe an allocation to Asia-Pacific in 2026 is an appropriate way to diversify from concentrated positioning in the US.
1Japan share buybacks soar past $100bn, driven by Sony, Hitachi – Nikkei 24 June 2026
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。
警告 — 有不法分子在網站及社交媒體上冒用荷寳 了解更多