Portfolio Manager

• 市場觀點
Pharma and life science tools: A quality growth revival
Pharmaceuticals sector equities are emerging from an extended period in which capital has chased hyperscalers and AI infrastructure instead. That rotation has left healthcare stocks still trading at a discount to the broader market, even as a clearer tariff and drug pricing framework, alongside a robust innovation cycle, sets up a strong fundamental outlook.
作者
熱門關鍵詞
概要
- Global investors are underweight healthcare
- Re-rating on solid fundamentals is our base case for the pharma sector
- Ongoing regulatory and tariff risks demand careful stock selection
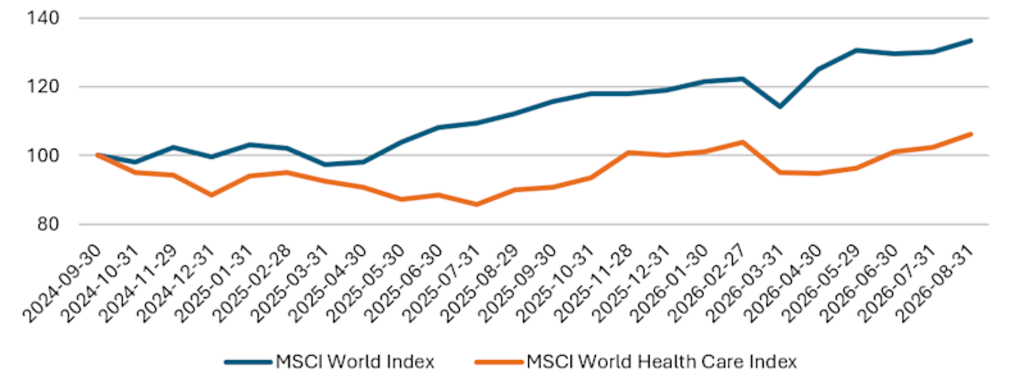
It has been an unusually painful period to own healthcare stocks. In the year to end-August, the MSCI World index has returned 11.3%, against 6.7% for the MSCI World Healthcare index. That gap is not about deteriorating fundamentals in pharmaceuticals or life science tools companies; it is almost entirely a story of capital rotation: trillions of dollars of incremental investment poured into hyperscalers and AI-infrastructure names, while healthcare, historically one of the market's largest and most defensive sectors, became a source of funds, even as the sector's underlying earnings kept compounding. That is a very different setup from prior healthcare corrections, which were typically driven by fears about the sector's own growth or regulatory outlook
Figure 1: Healthcare stocks have lagged the broad market for two years
Past performance is no guarantee of future results. The value of your investments may fluctuate.
Source: MSCI, Robeco, Data from 1 September 2024 to 31 August 2026, indexed to 100, USD price return.
That performance gap has started to close with investors rotating beyond tech, and for a reason that goes beyond healthcare's own fundamentals.
The Trump slump
Pharmaceuticals bore the sharpest edge of that rotation. The sector went through a post-US-election slump that finally bottomed in August 2025, with a 39% discount to the market – its deepest underperformance in 35 years – as investors priced in worst-case outcomes on drug pricing and tariffs. Sentiment has since improved as the most severe policy headwinds have cleared, allowing the sector to return to only a modest discount to the market – broadly back to its normal historical range. The revival was sharp and broad-based, but in our view it has still left the sector's better growth stories significantly mispriced.
Pharma's formula for growth
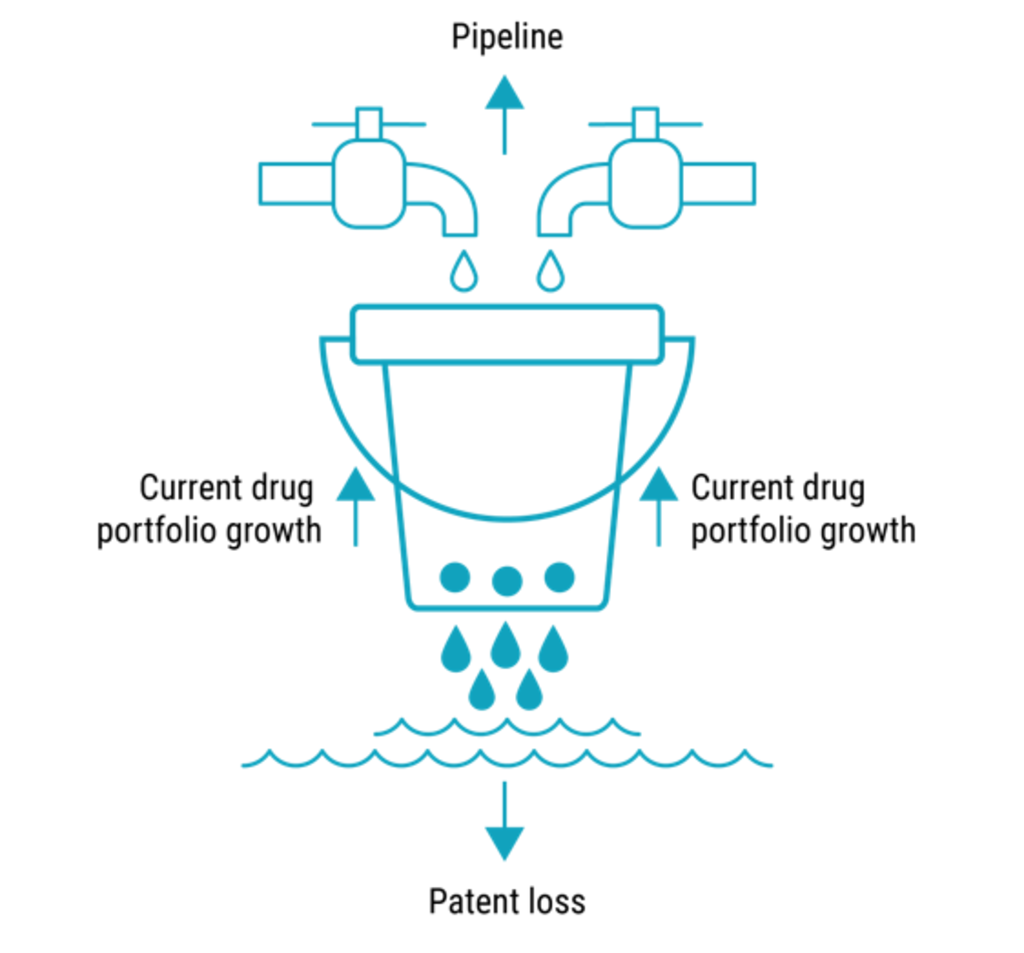
Growth cycles in the pharmaceutical industry are typically long, often lasting 10-13 years, and most are unrelated to wider macroeconomic cycles. Growth instead comes from revenue gains generated by innovative new drugs emerging from pipelines, net of revenue losses from patent expirations.
Figure 2: The pharmaceutical business model
Source: Robeco.
The novel drugs driving growth in the current cycle span many therapeutic areas – from the much-discussed GLP-1 drugs in the diabetes/obesity segment, to new disease-modifying treatments for historically untreatable neurodegenerative diseases, innovative cancer therapies, and new classes of drugs for a growing number of chronic inflammatory and cardiovascular diseases.
A story of haves and have-nots
What is unusual in this particular cycle is that many of the companies with the lowest patent-expiry burdens (positive for growth) also have the most compelling late-stage pipelines (also positive for growth). Companies with the largest patent-expiry burdens (negative for growth) tend to have the weakest pipelines (also negative for growth). The spread between the three highest-growth companies and the three lowest-growth companies in the sector is especially wide over the period 2025-30, with an estimated EPS CAGR differential of 19.3%. That spread is more than double historical levels and, in our view, represents a compelling opportunity for long-only portfolio strategies – particularly following a sector re-rating that has largely ignored these significant differences in medium-term outlook.
As a result, the sector's top three growth stories now trade at an average 1-year forward P/E of 16.9x, just below their average 5-year compound annual EPS growth of 17.2%. Historically, such an undervaluation of quality-growth compounders in a long-cycle sector with high visibility and relatively low correlation to macro cycles is rare and usually short-lived but may have been prolonged by the dominance of the AI theme in the recent past.
The tariff and US pricing fog clears
The biggest overhang on pharma valuations through 2025 was the possibility of cuts to US drug pricing as well as the threat of blanket tariffs on branded medicines. That fog has now largely lifted. In April 2026, the administration imposed a 100% tariff on imported patented pharmaceuticals,1but built in wide exemptions: a 0% rate for companies signing Most-Favored-Nation pricing and US-onshoring agreements (which most large & mid-cap pharmaceutical companies have now signed), 20% for onshoring-only commitments, and full exemptions for generics and biosimilars. Combined with Medicare's first negotiated prices taking effect in January 2026 under the IRA,2 the policy picture for large-cap pharma is now clearer in the mid term in our view.
That clarity, together with the patent cliff ahead, has unlocked one of the stronger M&A cycles the sector has seen in years. Pharma faces more than USD 200 billion of global branded-revenue exposure through 2032, with the patent problems peaking in 2028, concentrated in oncology, immunology and cardiometabolic franchises.3 As a result, large-cap pharma companies are redeploying balance-sheet capacity into pipeline replenishment with Biopharma M&A reaching USD 106 billion across 201 deals in the first five months of 2026 alone – on pace to be the strongest year since 2019.4 GLP-1 and obesity-adjacent assets remain the biggest single draw, but dealmakers have broadened into antibody-drug conjugates, radiopharmaceuticals and next-generation immunology. For long-only investors, this is a second leg of the pharma thesis: companies with clean pipelines are being rewarded twice – once by organic growth, and again as scarce assets that peers are willing to pay up for.
Life science tools quiet reset
As well as serving hospitals and some industrial segments, a majority of the life science tools sector’s revenue base sits along the pharmaceutical sector’s value chain and is hence leveraged with a time lag to the R&D investment and production cycles of the global pharmaceuticals industry. This healthcare sub-segment had enjoyed an exceptional double boost during the pandemic with Covid testing revenue added to vaccine production revenue but since the end of 2021 these tailwinds had reversed into growth headwinds with the sub-segment hitting an all-time low multiple vs the market as recently as May 2026, with much of the debate focused on whether life science tools would ever return to its historic mid-single digit growth dynamic. Many of these concerns have since begun to abate through what turned out to be a positive beat-and-raise Q2 2026 reporting season for most companies in the sector. Interestingly, however, despite the recent rally in the Tools space, it still only sits near the average of its 20-year multiple relative to the market. Given the strong recovery in the pharmaceutical industry’s R&D investment as well as continuing growth in its production facilities (boosted by US re-shoring in 2027-28) following the recent MFN deal signings, we remain confident in the growth outlook for the Life Science Tools industry.
What could still go wrong
The setup is not without risk. Oral GLP-1 formulations, if they launch successfully and cannibalize injectable share, could unsettle both the obesity-drug leaders and medtech names levered to bariatric and cardiometabolic procedure volumes. Pipelines themselves always carry clinical development risk. Proposed Medicaid reductions, expiring Affordable Care Act subsidies and the run-up to the 2026 US midterm elections could all reintroduce some policy uncertainty. And within healthcare, single-company shocks – as Boston Scientific and Zoetis5 illustrated in Q2 2026 when both companies cut guidance – show that a re-rating thesis for the sector still requires careful stock selection.
Re-rating scenario
None of these risks strike us as sufficient to derail the broader re-rating case. Healthcare is increasingly showing up as a rotation destination rather than a defensive afterthought, as institutional investors remain structurally underweight the sector after two years of AI-led flows. Consensus estimates point to an acceleration in healthcare earnings growth in 2027, at a time when the sector still trades at a discount to its own history and to the broader market.
Improving fundamentals that are resilient to economic cycles, alongside still modest valuations relative to the market and history, provide a compelling rationale for the Robeco Global Stars strategy overweight position in the sub-segments of healthcare that we view most positively – pharmaceuticals and tools. The strategy’s focus on owning high-quality growth compounders that remain attractively valued is the basis of our stock selection, and we continue to find substantial opportunity in the healthcare sector.
Footnotes
1 Drugmakers face 100% tariff unless they cut prices or produce drugs in US – Reuters – 2 April 2026
2 Drug companies sign “Most Favored Nation” deals, then raise prices anyway – Drug Discovery & Development – 2 January 2026
3 The 2026–2032 patent cliff by the numbers: 11,000 patents, $200 billion at risk – Pharmadossier – 10 June 2026
4 ‘Buying stuff like it’s going out of fashion’: Biotech M&A on track for best year since pre-Covid – CNBC – 4 June 2026
5 The companies shown here are for illustrative purposes only. No inference can be made on the future development of the company. This is not a buy, sell, or hold recommendation.
獲取最新市場觀點
訂閱我們的電子報,時刻把握投資資訊和專家分析。
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。