Head of Fixed Income Asia

• 市場觀點
Finding alpha in emerging markets’ sustainable transition
Emerging markets lie at the forefront of the low-carbon transition – and it could bring some amazing opportunities if you know where to look.
作者
Sustainable Investing Specialist
Portfolio Manager
概要
- Asia requires almost half the USD 125 trillion needed for net-zero transition
- Emerging markets lag behind developed world for clean energy investments
- New mindset along with the right tooling is needed to find potential opportunities
Tackling global warming requires some serious investment, with Asia alone requiring almost half of the USD 125 trillion needed to meet the Paris Agreement temperature goals and achieve net zero by 2050.
Yet, the funding of decarbonization has tended to focus on developed market economies, rather than in the emerging markets where it is most needed. A change in mindset is essential if investors are to not only play their role in net zero, but also find the best opportunities in the transition, Robeco’s latest research has found.
“This decade is make or break for climate change. The battleground is in emerging markets and developing economies,” says Thu Ha Chow, Head of Fixed Income in Asia and co-author of a special report on the issue, ‘Finding alpha in emerging markets’ sustainable transition.’
“In the past ten years, these emerging economies have accounted for 93% of the rise in carbon emissions. In the next ten years, they will account for 98% of global population growth. This makes them a key part of the global transition story, where the greatest impact is needed, and can be made, if we are going to reach our global net-zero targets.”
Even though emerging markets have largely been ignored – or even excluded – by mainstream investors when it comes to pursuing net zero, the financial odds remain in their favor. “Cutting emissions in these economies is estimated to cost half as much as in advanced economies due to the relative ease of purchasing clean technologies,” Chow says.
“In a study of ten developing economies, Standard Chartered reported that every dollar spent on adaptation in these countries in this decade would result in USD 12 of economic benefit. This supports a greater allocation of resources in emerging markets, where decarbonizing investments will ‘get more bang for the buck’.” 1
Insufficient data and terminology
One problem has been a lack of reliable data; research by Mobilising Institutional Capital Through Listed Product Structures (Mobilist) shows that mainstream ESG screening has actually diverted funds away from emerging economies because vital information is lacking.2
“Another key issue has been the lack of a clear definition for ‘transition’ which goes beyond strict adherence to ‘green’ activities against a backdrop of greenwashing fears,” says Chow. “Although emerging economies (excluding China) account for over two-thirds of the global population, they currently represent only one-third of global energy investment and a mere 20% of clean energy investment. Further, only about 3.6% of global pension funds are invested in these economies.”
This lack of definitions is being addressed by regional regulators such as the Monetary Authority of Singapore, which has launched the Singapore-Asia Taxonomy. This is the first in the world to include a ‘transition’ category that accounts for the needs of Asia as it seeks to position itself as a transitional financing hub for the region, alongside Hong Kong and Japan.
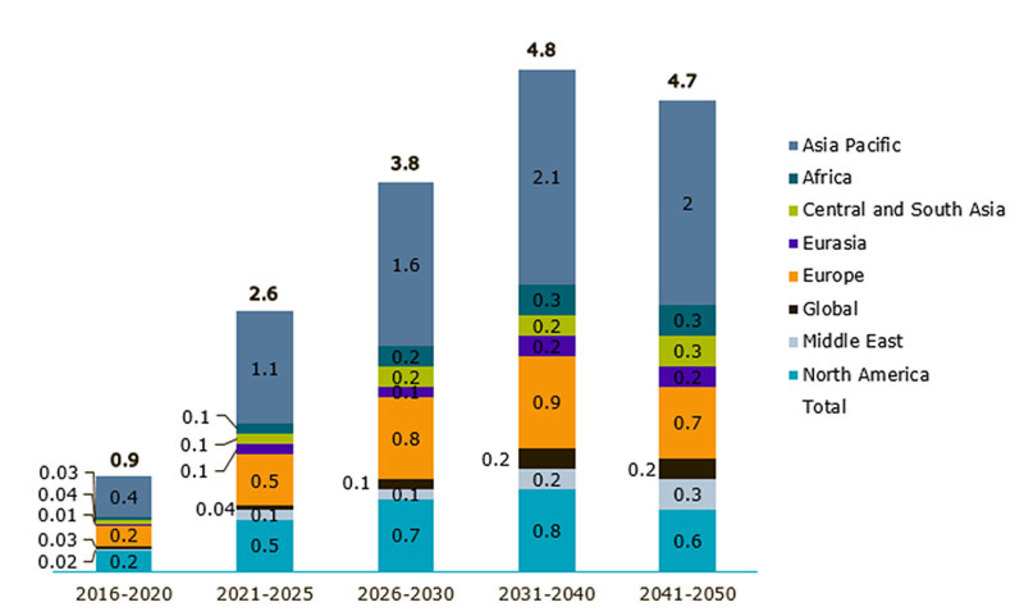
Annual average investment (USD trillions) required for decarbonization across regions, 2021-2050. Source: GFANZ. 3
可持續轉型
在實現可持續轉型目標的公司中尋找阿爾法
Two ways to find potential opportunities
So, how can investors address the problem? It lies in two areas: using this imperfect data to actually play markets at their own game rather than shying away from them, and having the right tools to identify the best corporate opportunities, Chow says.
“Imperfect information and market bias can offer attractive alpha opportunities for investors who find ways to bridge what the market lacks,” she says. “These research-driven investors aim to understand what is beyond the numbers, moving beyond the known facts to seek what the market may have missed. This applies just as much to sustainability and transition assessments as it does to financial analysis.”
“In the high-emitting sectors, the ability to transition is fundamental to an investment case, and the conclusion should not be to avoid the sectors, but to invest in the winners and the solution providers. It means creating frameworks that will allow us to establish credible transition candidates.”
Using the right frameworks
You therefore need the right frameworks. Robeco has developed tools that allow a 360-degree view of the potential emerging market investment landscape through the lens of the Sustainable Development Goals, using our proprietary SDG Framework for both companies and countries. This can view industries more reliant on fossil fuels as a solution waiting to happen, rather than as a current problem.
“For example, in emerging markets, vital activities like power generation are often tied to carbon-intensive assets,” Chow says. “Here we should be looking at the companies that have credible transition plans, as they will be main beneficiaries of decarbonization. This requires tooling such as our geographical Sector Decarbonization Pathways (SDPs) and our Traffic Light credibility assessment.”
“Meanwhile, Robeco’s wider stewardship and active engagement strategy ensures that we can keep a close eye on material sustainability issues that go beyond simple decarbonization. This can improve the transparency that is sometimes lacking in emerging markets, overcome inaction caused by greenwashing fears, and better channel investments to where impact can be maximized.”
Why you should increase allocation to EM in 2024
On-demand webinar
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。