
Portfolio Manager

概要
- We test factor premiums in government bond markets over 200+ years
- Value, momentum, low risk offer attractive and persistent premiums
- A multi-factor bonds portfolio adds value, whether yields rise or fall
Several studies show factor premiums are persistent phenomena in markets.1 Many of these studies examine equity factors; however, more recently, several research papers also show individual factors work well in credit markets and across asset classes. Despite these developments, not that much is known about factor premiums in government bond markets, where investors have been slower to adopt factor investing. This while government bonds represent about 30% of total market capitalization across asset classes.
We studied factor premiums in global government bond markets using a deep sample of 221 years of data between 1800 and 2020. Existing bond factor studies cover only the recent 20 to 30 years, which has a big potential pitfall: yields structurally declined over this period. Moreover, 20 to 30 years of data can be short in the light of the ‘p-hacking’2 concerns that plague backtesting and research. In a nutshell, our findings reveal that bond factors (value, momentum, low risk) offer attractive premiums that do not decay across samples, are persistent over time, and are consistent across various market or macroeconomic scenarios.
A multi-factor bonds strategy that combines value, momentum and low risk provides the strongest risk-adjusted returns and has a stable performance over time. This performance is strong regardless of being in ‘good’ or ‘bad’ states as characterized by expansions and recessions, non-crises or crises, positive or negative equity returns, or low or high inflation. Further, the factor premiums diversify to each other, as well as to bond or equity market risks, and consistently add value over traditional bond portfolios. Overall, a multi-factor bonds portfolio is interesting for bond investors, as it robustly adds value over a passive government bond portfolio.
To date, relatively few studies have examined government bond factor premiums. These studies typically research government bond factors over a limited sample, focus on one particular factor, or only consider a long-short perspective. For example, they generally cover the 30-year period 1982-2012. However, this sample has been a rather unique period in history, with few major episodes of bond market crises, economic recessions and inflationary episodes. Since 1980, yield levels in most markets experienced a secular decline. As a result, a key question is how bond factor premiums are influenced by falling or rising yield levels, and other episodes that typically are a concern for investors. In addition, several studies argue that published factor premiums could be influenced by p-hacking, which means that published findings might reflect a type I error in testing (i.e., falsely discovering predictability) and may fail to hold out of sample. This would be a big concern, as our focus is on achieving the best performance going forward, rather than seeking results that may apply in the past only.
To address these concerns, we use an extensive historical sample that spans all major government bond markets from developed countries, over a 221-year period. In total, our sample has 35,784 monthly return observations, which gives us sizable testing power to examine bond factor premiums. Moreover, over our sample period, global bond yields displayed several secular rates cycles, as illustrated in Figure 1 by the development of the global average 10-year yield based on France, Germany, Japan, the UK and the US. Generally speaking, post-1980 global government bond yields displayed a secular decline across the world. Before that period, though, yields behaved differently, and also experienced times of secular rises. Our study therefore also provides a natural robustness test of the influence of secular yield trends on bond factor premiums.
Figure 1 | Average 10-year yields 1800-2020
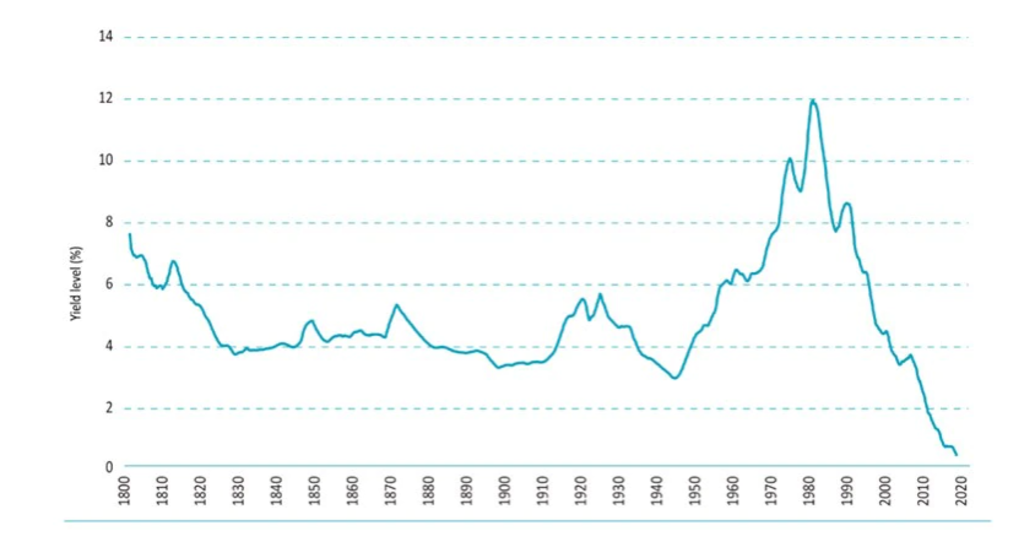
Note: 3-year rolling average of the 10-year yields for France, Germany, Japan, the UK and the US, from January 1800 to December 2020
Source: Baltussen, Martens and Penninga, 2021.
信貸投資的新動態
訂閱我們的電子報,緊跟最新的信貸投資趨勢。
Consistently attractive factor premiums, over long periods
We focus in our study on three key bond factors: value, momentum and low risk. These are applied either across developed market bonds, or within a market on the bond yield curve. The industry typically considers these to be key factors; they have been documented in previous studies, and have sufficient coverage over a substantial part of our sample period and across the markets we study.
We find that value, momentum and low risk offer attractive factor premiums. Moreover, these factor premiums are consistent over time, being positive in 72% (momentum) to 92% (value) of 10-year rolling periods. Combining the factors into a simple multi-factor portfolio gives a highly significant Sharpe ratio of 0.56 from 1800 to 2020. The premium is positive in 89% of the 10-year rolling periods. In other words, factor strategies in government bonds offer attractive returns and diversify each other.
Next, we show a multi-factor bonds portfolio gives robust performance over various macroeconomic states that typically are a concern for investors. As yields have displayed a secular decline over the past 40 years, and investors are concerned that we might be entering a period of a secular rise in yields, this insight is very important.
Figure 2 | Return and risk for the bond market portfolio and bond factor premiums
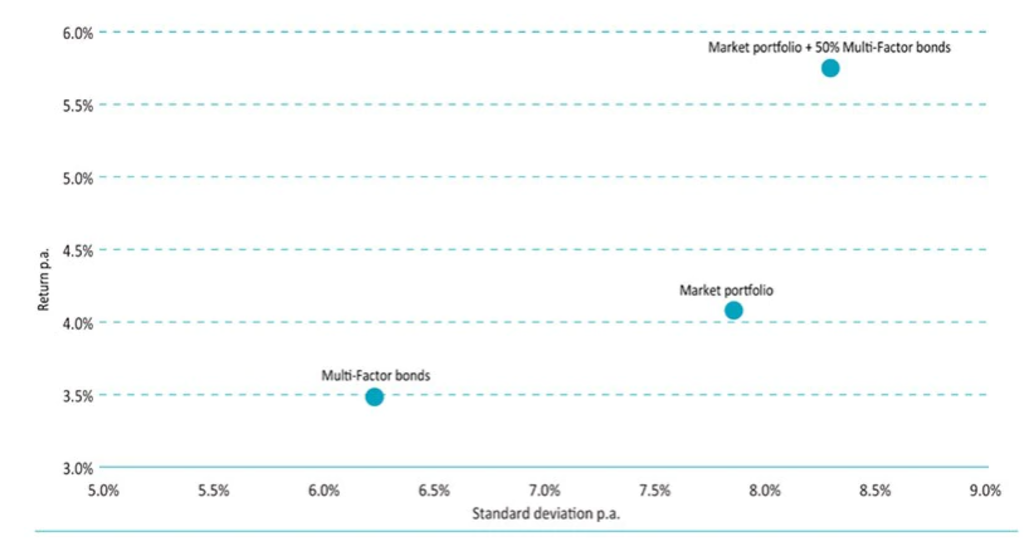
Note: The figure shows the average annualized returns and standard deviations for the global bond market portfolio (‘Market portfolio’), the global Multi-Factor bonds portfolio (‘Multi-Factor bonds’) – which combines the momentum, value and low-risk factors – and a combination of the bond market portfolio and 50% multi-factor bonds. The sample period is 1800-2020.
Source: Baltussen, Martens and Penninga, 2021.
For a long-only bond or multi-asset investor that considers adding bond factor premiums, we find there is strong evidence of value addition in a multi-factor bonds portfolio. Figure 2 summarizes the benefits. A multi-factor bonds portfolio has an average return of 3.48% a year, at a correlation of -0.05 with the bond market; adding a multi-factor bonds strategy to a passive global government bond portfolio increases returns substantially, with little impact on risk.
The findings show that, overall, a multi-factor bonds portfolio presents an interesting opportunity for bond investors, robustly adding value over a passive bond portfolio.
Footnotes
1This article is based on an academic paper entitled “Factor Investing in Bond Markets: Deep Sample Evidence”.
2P-hacking refers to the conscious or unconscious misuse of data analysis to find patterns in data.
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。