Portfolio Manager

• Visión
How to invest in resource scarcity, AI and industrial innovation
AI, electrification and industrialization are driving structural demand while straining resources and supply chains. At the same time, innovation across materials and manufacturing is creating new opportunities. By investing across the value chain, the Smart Materials strategy seeks to benefit from supply constraints, trade shifts and industrial breakthroughs.
Autores/Autoras

Co-Portfolio Manager
Resumen
- Structural trends are converging, intensifying demand for critical minerals
- Scarcity, bottlenecks and innovation continually shift sources of growth
- Capturing value from scarcity and innovation creates a competitive edge
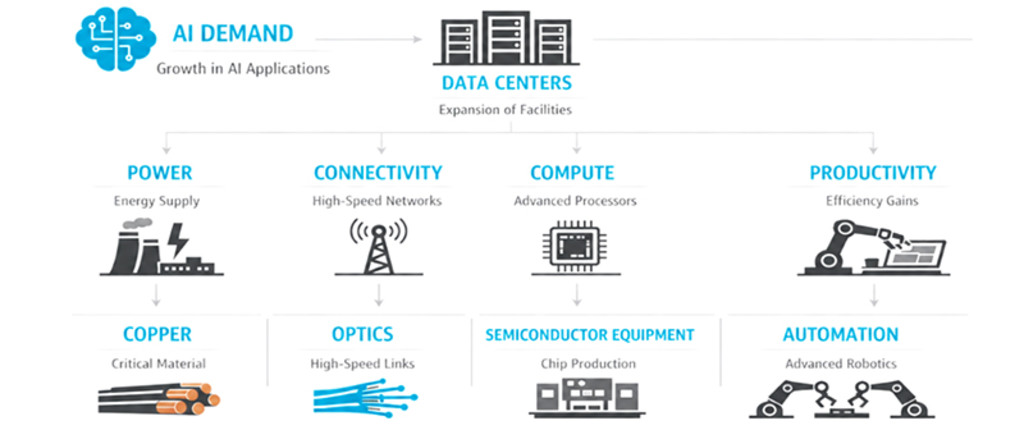
The global economy is entering a more material-intensive phase as the AI boom drives investment into data centers and digital infrastructure. These facilities require vast amounts of copper for power distribution, cabling, circuit boards and networking equipment, along with aluminum and steel for structural and electrical components. Cooling systems also rely on copper, stainless steel and other specialty alloys, while servers consume silicon semiconductors and smaller quantities of tin, silver and gold.
The sheer scale of volumes is unprecedented. Large AI hyperscaler campuses can contain up to 50,000 metric tons of copper and 200,000 metric tons of steel, roughly three to ten times the material intensity of a traditional data center.1
Figure 1 - Artificial intelligence meets ‘material’ demand
Source: Robeco
The metals behind electrification
Electrification is creating a second powerful source of materials demand. As transportation, industry and buildings shift from fossil fuels to electricity, investment is flowing into transmission lines, transformers, grid infrastructure, batteries, electric vehicles and charging networks. Basic metals like copper, aluminum and steel remain central to this buildout.
Copper wiring is critical for conducting electricity from grids to an exploding data center boom. Aluminum is increasingly used in transmission networks and electrical steel is essential for transformers and motors. Meanwhile, battery storage systems which complement renewable energy generation require substantial quantities of lithium, nickel, cobalt, graphite and manganese.
Over the long term, the energy transition should reduce resource use. Yet, ironically, building the infrastructure required to achieve it will be more material intensive. Experts project global copper demand to rise by around 50% by 2040.2 Supply, however, is projected to fall far short, creating a significant demand-supply deficit of nearly 25%.3
Figure 2 - Energy technologies are driving structural demand for critical minerals
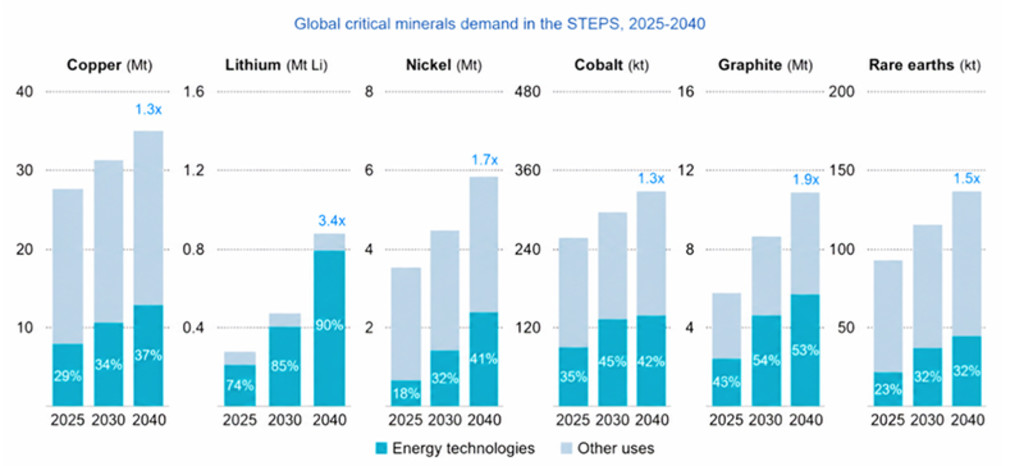
Global critical minerals demand in the IEA’s stated policy scenario (STEPS). Notes: kt = kilotonnes, Mt=million tons, STEPS = Stated Policies Scenario. The figures for copper are based on refined copper demand (excluding direct-use scrap). Rare earths refer to magnet rare earth elements only. Growth rate multiples (in blue) are between 2024-2040.
Source: Robeco, IEA, Global Critical Minerals Report, 2026.
Tiny volumes, significant impact
While copper, aluminum and steel account for the bulk of material volumes, a smaller group of specialty metals are stealing headlines and investor attention. Rare earth elements such as neodymium and praseodymium are essential for the high-performance permanent magnets in EVs, drones, industrial automation systems as well as humanoids – the next manufacturing revolution.
Meanwhile, strategic minerals like gallium are used in advanced power semiconductors and radio-frequency technologies, while germanium supports fiber-optic networks, infrared systems and specialized semiconductor applications. Tungsten also merits mention. Its hardness and thermal properties make it important for aerospace, defense and industrial tooling applications.
Although these materials represent only a small proportion of overall metal demand, they’re essential for many industries including national defense, which only amplifies their economic and strategic value.
Smart Materials D USD
- performance ytd (31-8)
- 42,88%
- Performance 3y (31-8)
- 19,50%
- morningstar (31-8)
- SFDR (31-8)
- Article 9
- Pago de dividendos (31-8)
- No
Rentabilidades pasadas no garantizan resultados futuros. El valor de las inversiones puede fluctuar.Anualizado (para periodos superiores a un año). Las rentabilidades son netas de comisiones, basadas en los precios de transacción.
More scarcity and imbalances create price swings
The consequences of scarcity and demand-supply imbalances are already visible in pricing. This year, copper and aluminum reached record highs, while steel prices have climbed 25% over the past year.4,5 In addition, lithium prices more than doubled as energy-storage demand strengthened and supply tightened. Prices for tungsten increased six-fold, and European import prices for gallium and the heavy rare earths dysprosium and terbium rose around five times relative to Chinese domestic price levels.6
Figure 3 - Copper prices hit record highs in 2026 in response to supply shortages
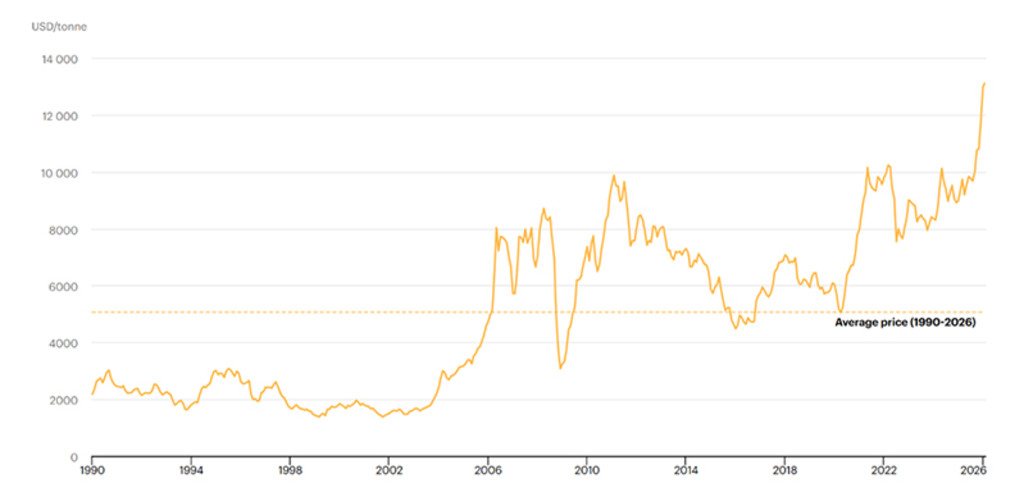
Copper monthly average price vs historic average price (1990-2026).
Source: IEA analysis based on SP Capital IQ data, 2026.
No ordinary cycle
Anyone who follows commodity price markets can attest to their highly cyclical nature. Shortages can drive up prices and stimulate additional production capacity. But they can eventually become tomorrow’s surpluses which put downward pressure on prices. What makes today’s cycles different is that demand is simultaneously surging, driven by overlapping structural drivers as far-ranging as AI and data centers, national defense and industrial policy, electrification and the energy transition.
New mines are time- and capital-intensive, taking years to permit, finance and build. And getting a mine operational is the first hurdle; finding high-quality raw materials is another. Declining ore grades mean that more rock may have to be mined, crushed and processed to produce the same quantity of metal. Supply will eventually expand but not immediately, meaning bottlenecks could mean persistently elevated prices.
Leave a bottleneck, enter a chokepoint
Even when natural production bottlenecks are resolved, chokepoints create another risk. China’s control over processing and refining means it dominates large parts of the critical mineral supply chain, and it has repeatedly applied export controls for political leverage. These have led to squeezed supplies, price surges and production delays in diverse sectors around the globe.7 The IEA estimates that if fully implemented, export controls could endanger USD 6.5 trillion in downstream production across automotive, semiconductors, aerospace, defense and energy sectors.8
For the Smart Materials strategy, this creates opportunities to invest in companies using innovative solutions to circumvent chokeholds. Those include refiners outside of China as well as companies focused on recovering and recycling scrap metal.
Figure 4 - China continues to impose export controls on strategic minerals
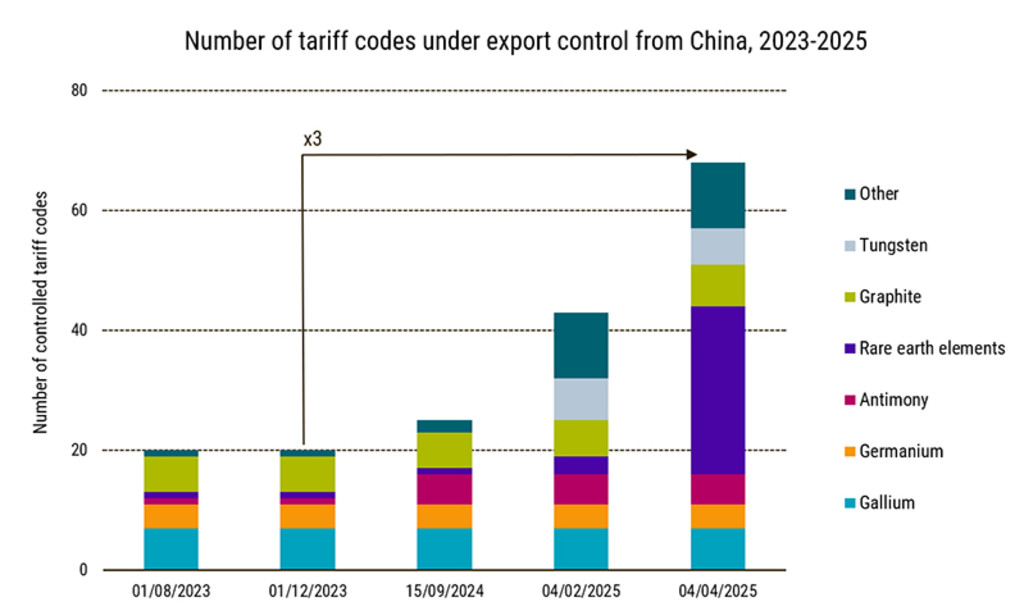
Number of tariff codes under export control from China, 2023-2025.
Source: Robeco, IEA analysis based on Chinese Customs data. IEA Global Critical Minerals Outlook, 2026.
Solutions to reduce dependence
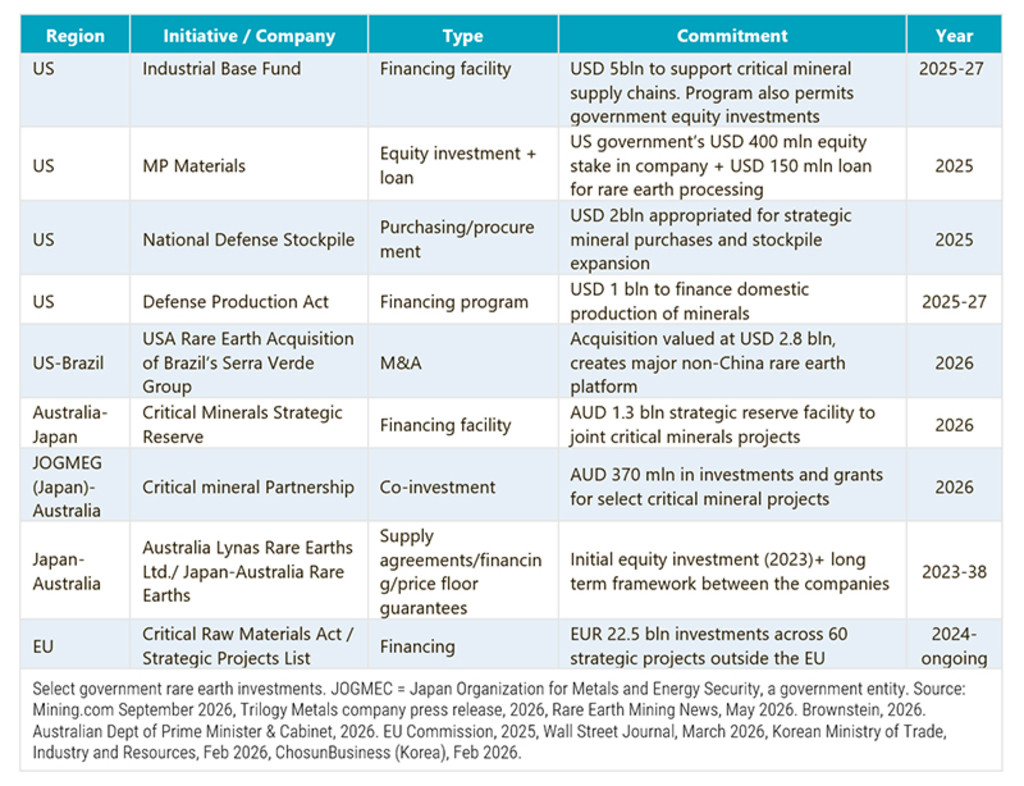
Minerals are being heralded as the new oil and governments are feverishly working to secure access to these critical resources. The EU Critical Raw Materials Act sets 2030 targets to mine 10%, process 40% and recycle 25% of the EU’s needs, while capping reliance on any single foreign supplier at 65%.
Across the Atlantic, private and public partnerships are also building. In 2025, Apple and MP Materials announced a USD 500 million deal to create a US rare-earth magnet supply chain using recycled feedstock, with the blessing of the Defense Department which has a 15% equity stake.
The Department of Energy also established the Office of Critical Minerals and Energy Innovation with several billion earmarked for FY 27 to help bolster domestic mining, refining and recycling for copper, rare-earths and allied metals.9
Table 1 – Illustrative examples of governments’ significant investments to secure and reshore strategic minerals (list is not exhaustive)
Scarcity often creates its own solutions
Higher costs encourage material substitution, recycling and greater processing efficiencies. A well-known episode is when automakers switched to platinum for catalytic converters after a period of sustained palladium deficits and high prices (2010-2020).10 More recently, major EV makers are adopting lithium-iron-phosphate batteries to reduce dependence on nickel and cobalt. And a recent price surge in silver is pushing PV manufacturers to reduce silver with more copper in solar panels. 11
And scarcity of know-how and skilled labor can create bottlenecks just as powerful as those of materials. We’ve seen this in semiconductors as chip architectures become more complex. Manufacturers increasingly rely on inspection, metrology and testing systems to improve yields and reduce waste. Meanwhile, labor shortages and supply-chain regionalization are driving investment in factory automation and warehouse robotics.
For the Smart Materials strategy, productivity-enhancing technologies are an important investment channel, as they represent another way to benefit from scarcity.
¿Cuáles son las tendencias actuales?
Suscríbase a nuestro newsletter para tener toda la información sobre las últimas tendencias de inversión temática al alcance de la mano.
Investing in resource constraints, innovation and disruption
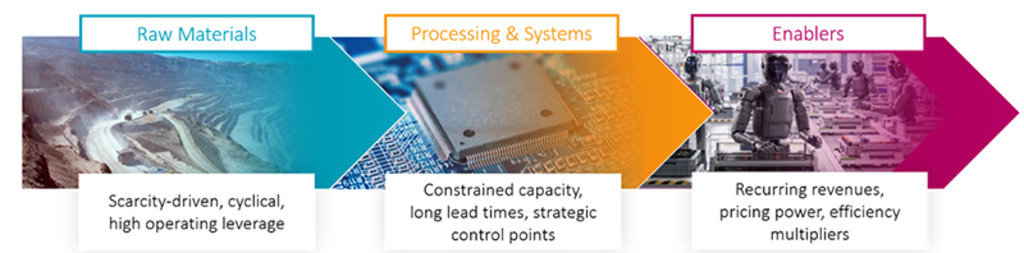
Robeco’s Smart Materials strategy is not based solely on rising demand for scarce resources or higher commodity prices; it also rests on how industries respond to scarcity. As resource constraints, bottlenecks and chokepoints emerge, capital shifts toward new supply, recycling, alternative materials and yield-enhancing technologies.
The strategy invests in a broad opportunity set, combining exposure to upstream companies supplying raw, refined, recovered and recycled materials with companies further downstream which provide specialized manufacturing equipment, software, automation systems and industrial technologies. By investing across these adjustment mechanisms, the Smart Materials strategy seeks to capture value and growth wherever it develops along the materials and manufacturing supply chain.
Figure 5 - The Smart Materials strategy invests in scarcity and innovation
Source: Robeco
Footnotes
1 Aviva Metals, ‘Data Center Copper: Meeting AI-Era Demand’, accessed September 2026.; World Economic Forum, ‘Metals at scale for AI at scale: Securing the data centre materials backbone’, December 2025.
2 S&P Global Energy & Market Intelligence, ‘Copper in the age of AI: Challenges of Electrification, January 2026.; S&P Global Press Release, ‘Substantial shortfall in Copper supply widens…’, January 2026.
3 S&P Global Energy & Market Intelligence, Copper discoveries: Expansion over addition as new discoveries lag.’ September 2026.
4 IEA, Global Critical Minerals Outlook 2026; Bloomberg, ‘Aluminum Hits $3,000 for First Time Since 2022 on Supply Concern’, January 2026.
5 Construction Dive, ‘Data centers are eating up steel…’, September 2026
6 IEA, Global Critical Minerals Outlook 2026
7 The impact of China’s new critical mineral export controls. Wood Mackenzie, October 2025.; ‘With new export controls, supply concentration risks become reality.’ IEA Commentary October 2025.
8 IEA, Global Critical Minerals Outlook, 2026.
9 US Dept. of Energy, Energy Department announces realignment of critical minerals and energy innovation programs.’ January 2026.
10 Bloomberg, ‘Carmakers May Wean Off Dependence on Palladium With Breakthrough’, March 2020.;
Asia Commodity Exchange, ‘Platinum vs. Palladium: The Battle of Precious Metals. January 2025.
11 Mining.com, ’Solar thrifting not enough to curb demand.’ June 2026