Head of Credits

• Fixed Income Quarterly Outlook
Higher bond yields in an era of abundant supply
Higher yields have strengthened the case for fixed income, even as abundant bond supply, inflation and tight spreads complicate the outlook. Our first integrated Fixed Income Quarterly Outlook brings together Robeco’s macro, rates and credit views to explore where opportunities remain and why selectivity matters.
作者

Head of Global Macro and Portfolio Manager
CIO High Yield, Portfolio Manager
新興市場債券主管
概要
- High starting yields provide a strong base for future fixed income returns
- Higher rates are increasing pressure on risk assets and leveraged borrowers
- AI investment and rising issuance are reshaping fixed income markets
AI is usually discussed as a technology or equity market story. For fixed income investors, however, it is increasingly becoming a supply story. Consensus expectations for hyperscaler capital expenditure in 2027 now exceed USD 1 trillion, while expected bond issuance from the largest technology companies has risen sharply as more of that investment is financed through debt.
The funding requirement also extends well beyond the hyperscalers. Data centers require a substantial and reliable supply of electricity, drawing utilities and grid operators into the same investment cycle. As this infrastructure expands, financing needs are spreading across the wider AI ecosystem.
Higher yields have strengthened the case for fixed income, but this is not a market for large directional bets
This new corporate borrowing arrives at a time when governments and supranational issuers already have substantial funding requirements. Fiscal deficits remain large and sovereign issuance is elevated, while public investment needs are growing. This means governments, technology companies and utilities are increasingly competing for the same pool of long-term capital.
This represents a reversal from recent years, when companies borrowed less, shortened maturities and reduced net issuance in response to higher rates. Limited bond supply, combined with persistent investor demand, provided powerful technical support for credit spreads. That scarcity is now giving way to greater bond abundance.
For investors, greater supply is not simply a risk. It should also create more choice and potentially better entry points into high-quality issuers. But it strengthens the case for active selection across sectors, maturities and currencies rather than relying on scarcity to keep spreads compressed.
Table 1 - Fixed income views at a glance
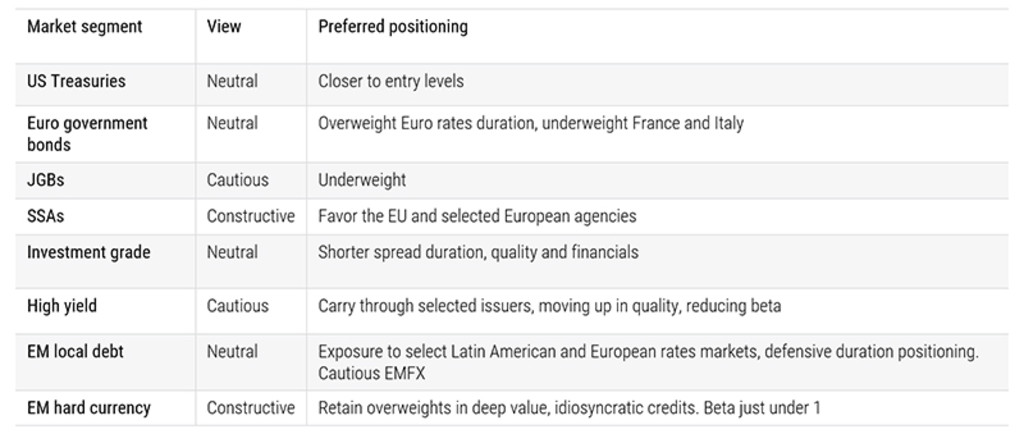
For illustrative purposes only. This is the current overview as of the date stated above and not a guarantee of future developments. It should not be assumed that any investments in sectors/markets/regions/themes/market cap/country identified were or will be profitable.
Source: Robeco, October 2026
For our detailed views on rates, credit and emerging market debt, including the developments that could make us more constructive, read the full Fixed Income Quarterly Outlook, or explore the key messages and positioning implications in Fixed Income Quarterly Outlook in Brief.
信貸投資的新動態
訂閱我們的電子報,緊跟最新的信貸投資趨勢。
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。