Client Portfolio Manager

概要
- Attractive yields but tight spreads and uncertain rates demand selectivity
- Global flexibility helps uncover income opportunities across credit markets
- Quality, shorter duration and active management help balance income and risk
Credit yields remain attractive,1 but accessing them has become more complicated. Spreads are tight, inflation uncertainty persists and longer-dated bonds remain vulnerable to shifts in rate expectations. For investors, returns are increasingly likely to come from the income available in credit markets and careful issuer selection, rather than from falling rates or further spread compression.
This puts a premium on a flexible approach that can adjust allocations as market conditions shift.
With demand coming from several directions, cash investors are considering moving beyond money market funds in search of higher income, while traditional bond investors want to limit long-term interest rate exposure. Although their starting points differ, the objective is similar: consistent income without taking more credit or duration risk than necessary.
Inflation remains difficult to predict, while fiscal and geopolitical developments add to uncertainty around interest rate policy. Rising government borrowing and bond supply may also put upward pressure on longer-term yields. At the same time, tight credit spreads provide less of a cushion against market setbacks, reinforcing the need to manage credit and duration risk carefully.
The Robeco Credit Income strategy is positioned accordingly. Duration is actively managed within a range of approximately three to five years and currently stands slightly below four years as at 8 September 2026. The strategy favors the short and intermediate parts of yield curves, reducing sensitivity to movements in longer-term rates. Credit beta is also modestly below one relative to the broader credit market, consistent with a cautious stance on broad market risk.
Using flexibility to find income globally
Relative value varies across credit markets as economic and financing conditions diverge between regions and issuers. A flexible mandate allows the strategy to allocate across global investment grade, high yield and emerging market credit. This flexibility is particularly important when index-level valuations are tight.
Current positioning favors subordinated financials and short-dated BB-rated credit. The team also sees selective value among B-rated issuers where the additional spread adequately compensates for the risk.
With the outlook for inflation and monetary policy still unsettled, investors need an approach that can adapt
The team remains constructive on its preferred HALO sectors (communications, utilities and mining), where resilient business models and favorable sector dynamics provide support. The strategy is more cautious on regions that are net importers of energy and therefore more vulnerable to higher energy costs and renewed inflationary pressure. Beyond the US, the strategy has found attractive opportunities in European and emerging credit, providing diversification across different economic and interest rate cycles.
Separating AI’s credit winners from its losers
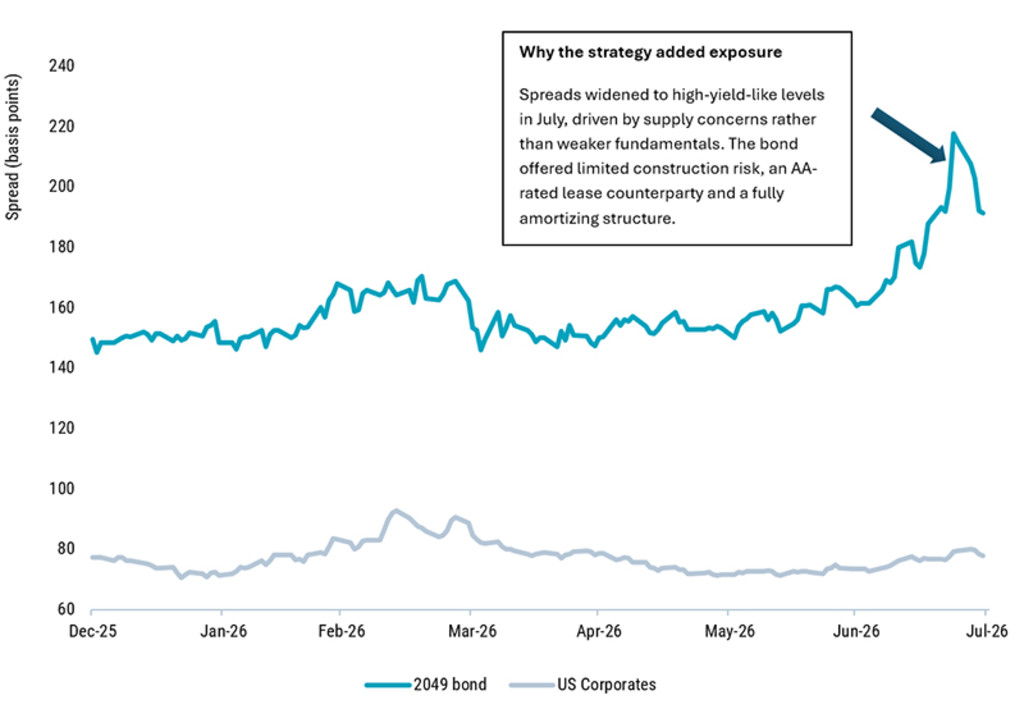
The expansion of artificial intelligence is another example of why bottom-up selection matters. AI investment may create significant long-term opportunities, but it also requires substantial capital expenditure. For bondholders, future growth needs to be weighed against the financing and execution risks. Figure 1 shows how supply-driven spread widening in an A-rated data center bond allowed the strategy to add exposure.
Figure 1 – Supply concerns widen spread on a A-rated data center bond. Spread of 2049 bond versus US investment grade corporate index (basis points).
All expressions of opinion are subject to change. This information is intended for educational purposes, and it is not to be construed as an offer, solicitation, recommendation, or endorsement of any particular security, products or services. The positions shown on this slide are for illustrative purposes only in order to demonstrate the investment strategy on the date stated. No inference can be made on the future development of the issuer/issue. This is not a buy, sell, or hold recommendation. Source: Robeco, Bloomberg. Data as of July 2026.
Despite this individual opportunity, the strategy maintains an overall cautious stance on technology, where the potential upside for creditors appears limited relative to the risks. The focus is on distinguishing companies that can comfortably fund AI-related investment from those whose credit quality could deteriorate as spending rises. The same discipline applies elsewhere with limited exposure to cyclical or lower-quality companies where spreads do not adequately compensate for risk.
Income without depending on a single market outcome
With the outlook for inflation and monetary policy still unsettled, investors need an approach that can adapt. Credit Income’s flexible approach allows the strategy to reposition as conditions change, guided by bottom-up research on where risk is worth taking. This adaptability makes the strategy particularly relevant today: able to pursue income where it is best rewarded while remaining disciplined when risks rise.
Footnote
1Past performance is no guarantee of future results. The value of your investments may fluctuate.
信貸投資的新動態
訂閱我們的電子報,緊跟最新的信貸投資趨勢。
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。