Strategist

• 市場觀點
Warsh's wishful thinking
Kevin Warsh has been portrayed as an inflation hawk, but the picture is much more nuanced. His views actually suggest room for lower (not higher) rates, and his goal of shrinking the Fed’s balance sheet may turn out to be more wishful thinking than reality.
作者

Strategist
Strategist
概要
- Warsh looks less like a hawk and more like a pragmatic rate-cutter
- Shrinking the Fed’s balance sheet may prove harder than the rhetoric suggests
- The Treasury curve still has steepening potential
During his time as Federal Reserve Governor, Fed Chair-pick Kevin Warsh fretted about the inflationary risks emanating from Quantitative Easing (QE) and emerged as one of its most vocal internal critics. We now know QE primarily as a policy that has boosted the Fed’s balance sheet. Hence, it is of little surprise that in a Wall Street Journal op-ed in November 2025, he argued that “the Fed's bloated balance sheet… can be reduced significantly”. This view has cemented his recent portrayal as an inflation hawk.
However, he has also clarified that “if we would run the printing press a little quieter, we could then have lower interest rates”. Not a pure hawk then. What is more, back in July, he criticized the Fed’s “hesitancy” to cut rates during an interview with CNBC – which hardly sounds hawkish. As for Warsh’s view that the Fed’s balance sheet should decline, this could be perceived by investors as detrimental to the support of the longer-dated segments of the US Treasury market – something the current Treasury Secretary Scott Bessent would surely not cheer.
There’s also another practical difficulty to consider: aggressively shrinking the Fed’s balance sheet could re-ignite tensions in US money markets. A rapid decline in reserves risks pushing the system back toward scarcity, increasing volatility in overnight funding rates and repo markets. Indeed, to prevent this, the Fed has recently decided – after several years of Quantitative Tightening (QT) – to expand its balance sheet again mainly through increased Treasury bill purchases.
In short: we believe that the portrayal of Kevin Warsh as a hawk is overstated and expect that he will support a further reduction in policy rates by June, which would likely be his first meeting as Chair. Regarding his view that the Fed’s balance sheet may be excessively large, we believe it will be difficult in practice to shrink it meaningfully without regulatory adjustments to the ample-reserves regime in the banking system.
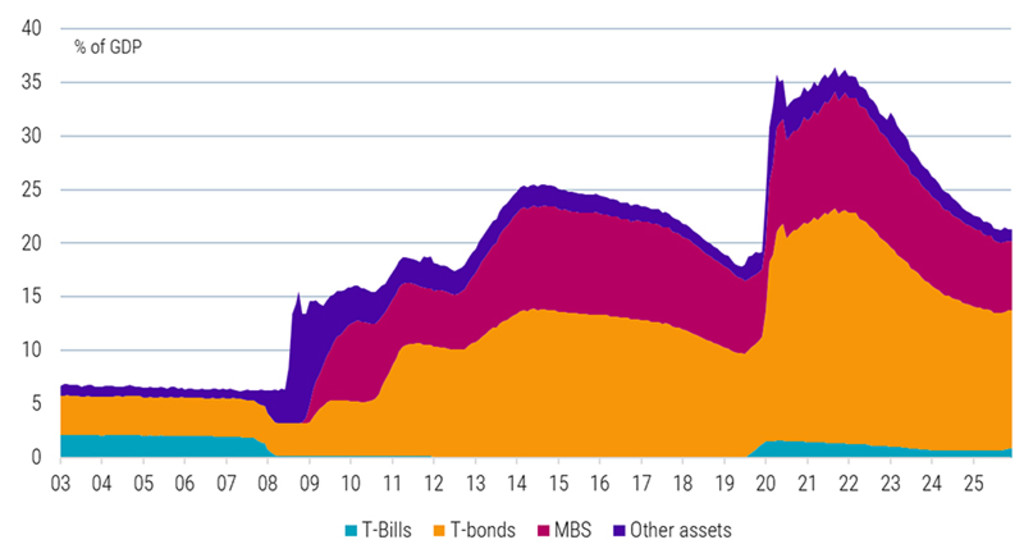
A plausible outcome is that the balance sheet – currently around 20% of GDP (see chart below) – expands more slowly than the US economy in the coming years, and/or that Warsh advocates for a faster shortening of the average maturity of the Fed’s bond portfolio. This should make our preference for the 2 to 5 year segment of the Treasury curve relative to 10 year maturities far from wishful thinking, and instead a logical outcome of a Fed that, under Warsh, is likely to favor pragmatism over ideology.
Federal Reserve assets, as % of GDP
Source: Bloomberg, Robeco, 6 February 2025
獲取最新市場觀點
訂閱我們的電子報,時刻把握投資資訊和專家分析。
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。