Global Head of Fundamental Equity

• 季度展望
Equity outlook: Building on momentum
The proverbial ‘wall of worry' looks less daunting as we enter Q2 with the US economy continuing to show resilience and Europe’s economy appearing to have bottomed and inflation down, if not out.
作者


Head of Emerging Markets team
概要
- Developed markets are overexuberant, but we see pockets of value
- Emerging markets are primed to perform with central banks easing
- European equities are under-owned despite hitting record highs
At the end of last year this seemed to be an equity bull market running on euphoria over AI but this quarter broader strength has developed, as we hoped it would, with record index highs being hit in Europe also.
The view that there will be a sting-in-the-tail of higher rates or that the weak commercial property sector will drag the financial system, and then the wider economy, into a slump, is now a minority one. It’s so far, so good in 2024, and the market is raising year-end targets. We are now about to move into the dovish period of the cycle, albeit it at a slower pace than anticipated by investors. The recent interest rate cut by the Swiss central bank confirms that view.
In emerging markets, many central banks are lowering interest rates. Brazil for instance passed its sixth cut already. With inflation falling in tandem, it allows even more room for policy relaxation. Is this all too good to be true? We don’t think so, and believe emerging markets can do really well this year.
Looking at the global election cycle from a financial markets’ point of view, it’s all been smooth so far and in Q2 we don’t expect any surprise from India either. Of course the big one all investors are watching is in November in the US. Whoever wins, the stock market promises a good place to be with both Biden and Trump likely to pursue expansionary fiscal policies into a monetary easing cycle. That makes any coming correction, even a steep one, look like an opportunity.
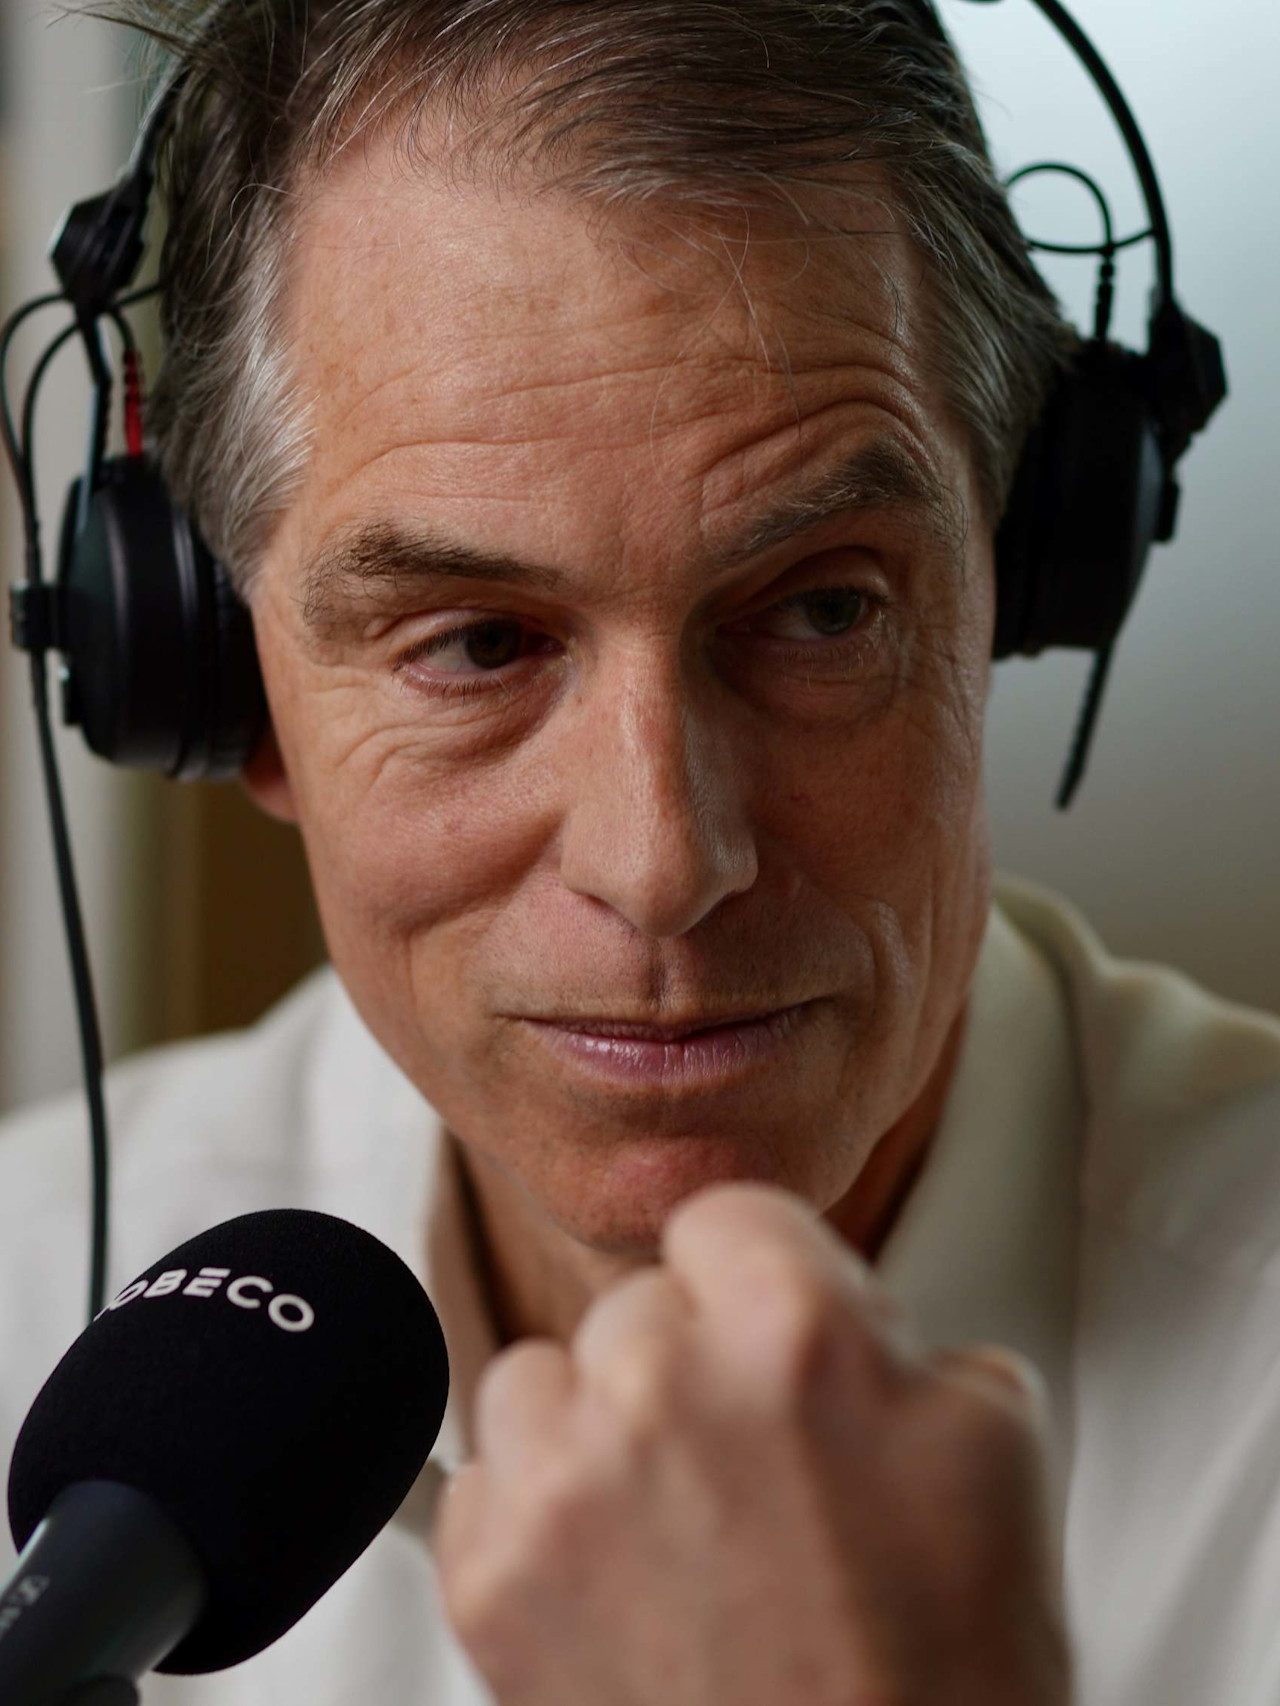
In this edition of our Quarterly we give you our outlook for developed and emerging markets, an interview with our European Stars strategy lead Mathias Büeler, perspective on two Industrials conferences in Miami, a primer on transition finance, a contrarian view on Japan real estate, and we introduce our new Emerging Markets ex-China strategy. Enjoy!
下載刊物
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。