Engagement Specialist

• 市場觀點
The uphill struggle in tackling commodity-linked deforestation
Progress has been made in managing deforestation risks, though traceability remains a challenging issue for companies, Robeco’s engagement has found.
概要
- Effective engagement with around two-thirds of companies in the program
- More companies set zero deforestation targets for suppliers
- Yet traceability and monitoring remains an uphill battle for some
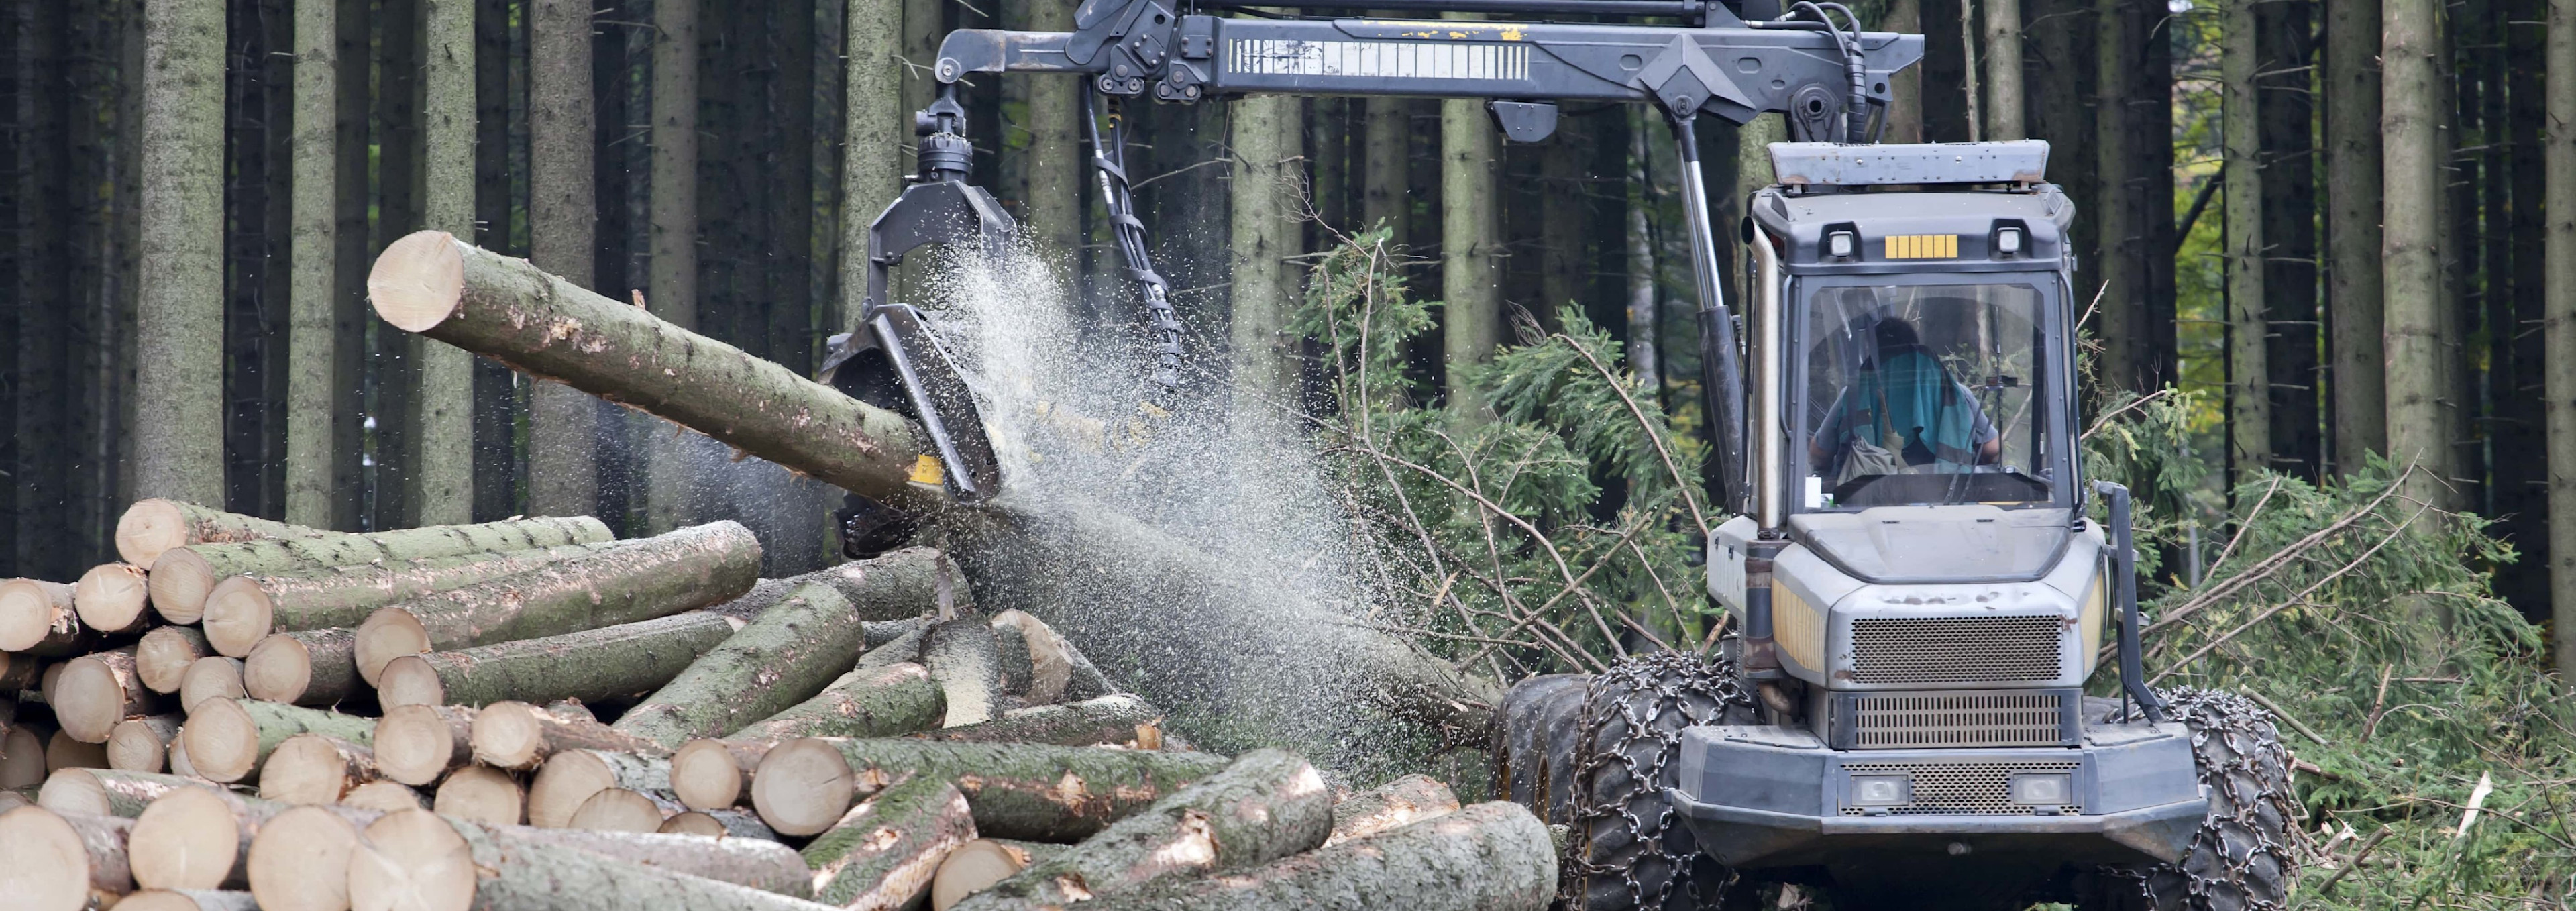
The Active Ownership team is winding down an engagement program launched in 2019 focused on addressing biodiversity loss linked to deforestation driven by production of five key commodities – cocoa, pulp and paper, natural rubber, beef and soy. All are extensively used in the food, materials and consumer goods sectors in which Robeco invests.
Investee companies who sourced these commodities were asked to set credible zero deforestation commitments, conduct robust biodiversity impact assessments, and address the social challenges in their supply chains that amplify power imbalances and further incentivize deforestation. All were expected to actively work towards reverting nature loss no later than 2030.
The engagement, which came to an end in June, has produced mixed results. We successfully closed around two-thirds of engagement dialogues under the engagement theme. “In the last three years, we have seen more companies setting zero deforestation targets and strengthening their monitoring systems to map how their suppliers are exposed to deforestation risks,” says engagement specialist Laura Bosch.
“However, challenges remain around the scope of some of these policies and the overall monitoring efforts to prevent and manage deforestation risks upstream in their value chains. Some companies sourcing soy and beef still struggle to include illegal deforestation and native vegetation under such commitments.”
“Pulp and paper companies tend to be vertically integrated and source smaller volumes from external suppliers, and so have better traceability and monitoring systems in place. They are also able to rely on well-established certification schemes such as the Forest Stewardship Council (FSC) and the Programme for the Endorsement of Forest Certification (PEFC).”
“For companies sourcing cocoa and rubber, the challenge around traceability and monitoring remains an uphill battle. These soft commodities rely heavily on smallholder farmers and have several intermediaries involved in the value chain, making the overall visibility across the supply chain more challenging.”
了解最新的可持續性市場觀點
訂閱我們的電子報,探索塑造可持續投資的趨勢。
Biodiversity impact assessments
Land use change remains the biggest driver for biodiversity loss, led by deforestation to make way for livestock or high-value cash crops such as palm oil – the subject of a separate engagement campaign that has been running since 2018. Aside from the destruction of natural habitats, often also adversely affecting indigenous populations, forests are major carbon sinks that can help reduce global warming.
It is therefore essential for companies to embrace ecosystem conservation and restoration in areas where commodity sourcing has had a negative impact. “In our engagement, we asked companies to implement adequate ecosystem restoration and conservation efforts next to improved disclosures on locations in high carbon stock areas,” Bosch says.
“Most companies have restoration and conservation projects in place, but these tend to be implemented on an ad-hoc basis without being strategically set to mitigate the negative impact of their sourcing strategies. Few were able to commit a sizable level of investments to advance their work on this front. We have seen companies issuing green bonds or fund pilot schemes which aim to restore or conserve landscapes where they source the soft commodities from.”
Risk assessments
Biodiversity loss is a risk that needs to assessed by investors and companies alike. Regulators across the globe are placing more importance on encouraging the private sector to manage this risk. For example, the EU’s Sustainable Finance Disclosure Regulation (SFDR) now requires investors to report the Principal Adverse Impacts of their investments, one of which refers to the direct biodiversity impact of companies.
Standardized disclosures on how to manage biodiversity-related risks and opportunities will be supported by the launch of the Taskforce for Nature-related Financial Disclosures (TNFD) in September 2023.
The EU Deforestation Regulation (EUDR) similarly requires companies importing products linked to high-risk soft commodities to prove that these are not linked to deforestation. “In our engagements, we have asked companies to enhance the traceability of the raw materials they source and conduct a risk assessment to understand where the risks lie across their supply chains,” says Bosch.
“When it comes to analyzing the biodiversity impacts and dependencies of companies, few are checking their reliance on different species of plants, or trying to calculate their impact on nature with the Integrated Biodiversity Assessment Tool (IBAT) or similar tools.”
“We hope the integration of the new Taskforce for Nature-related Financial Disclosures (TNFD) framework will help in streamlining a holistic approach towards how companies carry out their biodiversity impact assessments.”
Greater disclosure
What is also encouraging is the raised levels of disclosures of corporate activity on biodiversity. “We recognize that some companies are starting to disclose their deforestation-free volumes and Scope 3 emissions in sourcing of raw materials – something which was not publicly disclosed few years ago,” says Bosch.
“The adoption of certification schemes has also increased over time, with companies in the pulp and paper industry achieving a relatively high level of FSC and PEFC certifications throughout their supply chain.”
“Other soft commodities such as natural rubber or soy still lack a credible certification scheme adopted across the industry. Key disclosure challenges relate to divergent definitions used by companies to report their deforestation efforts, lack of independent verification for some of their efforts, and overall lack of disclose of the hectares linked to land use change.”
Ongoing engagement efforts
While the deforestation engagement theme is closing, work will continue on reducing biodiversity loss. The Nature Action 100 investor group will collaboratively target engagement efforts on those companies and sectors with the highest negative impact on nature. It will work in a similar way to the Climate Action 100+ group which has seen success in tackling the world’s biggest carbon emitters.
“Moreover, we continue our sovereign engagement work focused on supporting government agencies in their efforts to reduce deforestation rates in Brazil and Indonesia,” Bosch says. “We cannot afford another decade of nature loss if we are serious about tackling climate change.
“Increased momentum on the topic of mitigating biodiversity loss in the next decade is undeniable. Both companies and investors are directly exposed to soft and hard law requiring more transparency on how nature impacts and dependencies are accounted for across their organizations.”
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。