探索量化價值
訂閱我們的電子報,獲取尖端的量化策略和見解。

The debate on whether investors should tactically time their factor exposures is almost as old as the discovery of factors. Given the cyclical nature of factor premiums, successful timing could, in theory, yield very attractive returns. In practice, however, things often turn out to be much more complicated.
As we mentioned in the first article of this series, factor premiums vary over time. Single-factor portfolios can experience periods of relative underperformance or outperformance lasting several years. For instance, small cap and value stocks performed dismally in the second half of the 1990s, while growth-like tech stocks reached stratospheric heights.
These large swings create the temptation to indulge in factor timing. Yet, success in this field of active management is far from easy. For one, the exact causes of these fluctuations remain a moot point. While factor performance seems to depend on macroeconomic conditions, the relationships between factor premiums and many key economic indicators have proven to be unstable over longer periods of time.1
Moreover, other elements may also have an influence. For instance, supply and demand considerations could play a role, as some single-factor strategies may be very popular at one in point in time, while others fall out of favor. Many empirical studies have documented widespread herding behavior, both into popular factor strategies and away from unloved ones.2
The academic literature reveals both a positive autocorrelation in the time series of factor premiums – in other words, factor momentum – and large fluctuations in the valuation of single-factor strategies over time.3 These two well-documented phenomena could, in theory, be used to tactically time factor exposures.
Arguably, however, one of the most popular timing approaches is to look at the relative valuation of different single-factor portfolios, usually using classic measures of valuation such as price-to-book or price-earnings ratios. The idea is to increase exposure to factors that trade at a discount compared to their historical norms and to reduce exposure to those exhibiting historically high valuations.4
Critics of this approach have argued that the simulated investment results obtained through this kind of strategy are not particularly strong and too highly correlated with conventional value factor strategies.5 Moreover, different measures of valuation often lead to conflicting conclusions. As a result, investors should generally refrain from timing factors, except on very rare occasions.
Heated arguments between Rob Arnott from Research Affiliates and Cliff Asness from AQR are the most obvious case in point.6 While Arnott has long been advocating for factor timing based on relative valuations of different factors, Asness has been consistently warning about the dangers and uncertain benefits of such tactical endeavors.
Timing factors based solely on their own past returns also appears to be challenging.7 However, recent studies take a fresh perspective and do report strong results for factor momentum. The key new insight is to consider a very short look-back period of just one month, and to apply it to many dozens of factors.8
Robeco research confirms these results but finds that the successful exploitation of this kind of factor momentum requires full integration into the bottom-up stock selection process of the factor strategies themselves.9 A naive approach to factor momentum – using momentum signals to rotate across a handful of single-factor portfolios – is too crude and costly to be worthwhile.
Of course, things are never completely black or white and, after months of intense public debate, leading voices from both camps – for and against factor-timing – have shown signs of appeasement. While some acknowledge that timing only works part of the time, others concede that timing could make sense in some rare cases.10
訂閱我們的電子報,獲取尖端的量化策略和見解。
Amidst the opposing views of supporters and adversaries of tactical factor timing, other academics and practitioners have advocated a halfway house: timing factors, but only to a limited extent – and with fair dose of caution.11 The idea is to use variables such as factor valuations, short-term factor momentum and macroeconomic indicators to predict short-term factor returns.
Based on these predictions, investors can tilt their portfolios towards the factors with the best prospects and away from the less promising ones. Some refer to this as factor rotation; others call it factor tilting. But while this may sound tempting, it requires two preconditions: sufficient prediction accuracy to deliver significant returns and relatively low costs of implementation to justify the effort.
Unfortunately, the academic literature on this topic leads to the conclusion that, for most investors, timing factor premiums is even more challenging than traditional market timing – which is already a notoriously difficult exercise.12 For sure, many empirical studies on general market timing contradict most of those experts who claim they can achieve it.13
In the case of factor premiums, the fact that factor strategies are dynamic and that portfolios need to be regularly rebalanced adds an additional layer of complexity to the problem. One way to overcome this would be to use low-fee generic smart beta products. But as we have seen in previous articles in this series, such products tend to be far from ideal and subject to numerous pitfalls.
Simulations by Robeco researchers also show that, on top of the technical challenges implied by factor timing, investors need quite accurate predictions of which factor will outperform in the short term – say, on a monthly or a quarterly basis – in order to beat a naive equal-weight allocation to various time-tested factors.
Investors would need to select the correct factor more than 50 to 60% of the time to outperform an equal-weight allocation to various factors. But our analysis ignored the fees investors would have to pay to their asset manager to deliver such timing accuracy. Once these fees are taken into account, the added value of factor timing becomes really dubious for the end investor.14
While factor timing may sound tempting, it requires two preconditions: sufficient prediction accuracy to deliver significant returns and relatively low costs of implementation
Systematic tactical factor timing must therefore be taken with a dose of caution. A better option is often to opt for broad diversification across different factors, or for one particular factor of strategic interest, bearing in mind one or several factors could experience short-term underperformance, as illustrated by Figure 1. The graph shows the performance of generic factors across decades.
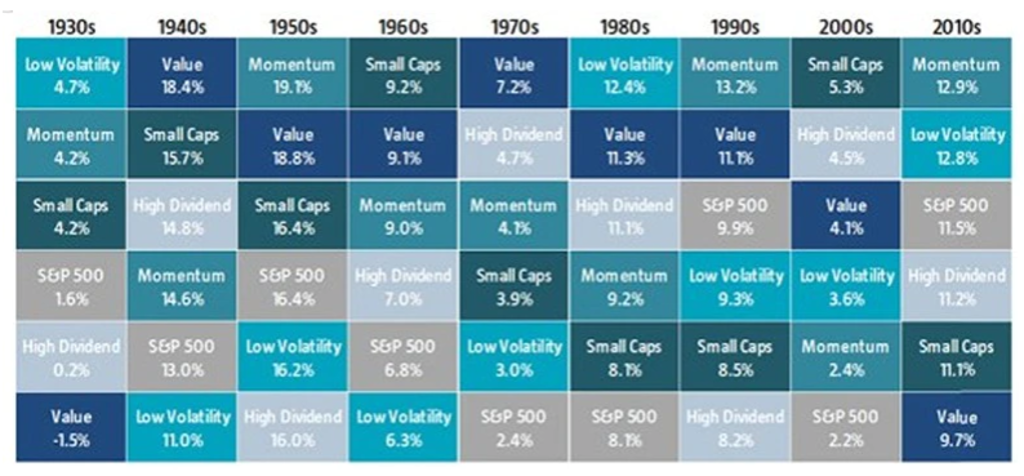
Source: Robeco, based on Kenneth French Database and Paradoxinvesting.com
Ultimately, it is our view that patient investors who trade little and stick to their factor exposures are more likely to outperform the market in the long run. Sustainable investing is one way to ensure this, as investors often tend to be more committed to strategies that reflect their values, even when these temporarily underperform. That said, combining factor and sustainable investing is easier said than done. The debate on the role that sustainability should play in securities selection will be addressed in the following article in this series.
1This is one of the major pitfalls of factor timing raised in: Bender, J., Sun, X., Thomas, R. and Zdorovtsov, V., 2018, “The Promises and Pitfalls of Factor Timing”, The Journal of Portfolio Management.
2See: Gelderen, E., Huij, J. and Kyosev, G., 2019, “Factor Investing from Concept to Implementation”, The Journal of Portfolio Management. See also: Hsu, J. C., Myers, B. W. and Whitby, R. J., 2016, “Timing Poorly: A Guide to Generating Poor Returns While Investing in Successful Strategies”, The Journal of Portfolio Management. See also: Arnott, R. D., Beck, N., Kalesnik, V. and West, J., 2016, “How Can ‘Smart Beta’ Go Horribly Wrong?”, working paper. See also: Barberis, N., and Shleifer, A., 2003, “Style investing”, Journal of Financial Economics.
3See: Ilmanen, A., Israel, R., Moskovitz, T. J., Thapar, A. and Wang, F., 2019, “How Do Factor Premia Vary Over Time? A Century of Evidence”, working paper. [1]Asness, C., 2016, “The Siren Song of Factor timing”, Journal of Portfolio Management.
4Arnott, R. D., Beck, N. and Kalesnik, V., 2016, “Timing ‘Smart Beta’ Strategies? Of Course! Buy Low, Sell High!”, working paper.
5Asness, C., 2016, “The Siren Song of Factor timing”, Journal of Portfolio Management.
6See for example: Asness, C., 2016, “My Factor Philippic”, working paper.
7See for example: Arnott, R. D., Beck, N. and Kalesnik, V., 2017, “Forecasting Factor and Smart Beta Returns (Hint: History Is Worse than Useless)”, working paper.
8See, for example: Ehsani, S., and Linnainmaa, J., 2019, “Factor momentum and the momentum factor”, working paper. See also: Gupta, T., and Kelly, B., 2019, “Factor momentum everywhere”, Journal of Portfolio Management., See also: Arnott, R. D., Clemens, M., Kalesnik, V., and Linnainmaa, J., 2019, “Factor momentum”, working paper.
9Hanauer, M., Honarvar, I., Swinkels, L. and Zhou, W., 2020, “Exploiting short-term factor momentum”, Robeco client note.
10Asness, C., November 2019, “It’s Time for a Venial Value-Timing Sin”, article.
11See: Hodges, P., Hogan, K., Peterson, J. R. and Ang, A., 2017, “Factor Timing with Cross-Sectional and Time-Series Predictors”, The Journal of Portfolio Management.
12Asness, C., Ilmanen, A. and Maloney, T., 2017, “Market Timing: Sin a Little”, Journal of Investment Management.
13For a seminal paper on the subject, see for example: Sharpe, F. W., 1975, “Likely Gains from Market Timing”, Financial Analysts Journal.
14Blitz, D. C., Lansdorp. S., Roscovan, V. and Vidojevic, M., 2018, “The promises and challenges of factor timing”, Robeco client note.
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。
警告 — 有不法分子在網站及社交媒體上冒用荷寳 了解更多