

Portfolio Manager

• 市場觀點
More than meets the factor eye: Hidden depths in next-gen quant investing
At Robeco, we go beyond generic factors by continuously innovating factor themes and developing unique signals using short-term and alternative data. Recent research shows that generic factor scans can make corresponding investments appear unbalanced, while factor scans based on relevant factor definitions reveal these same portfolios to be actually well-balanced and profitable when it comes to exposure, risk, and performance.

概要
- Our Quant Equity strategies balance enhanced factor and proprietary signal exposure
- Generic factor scans may fail to capture true nature of portfolios
- Our 20-year track record is largely unexplainable through generic factors
Measuring factor exposure can be ambiguous if generic factor definitions are used instead of enhanced versions which are designed to earn superior risk-adjusted returns. In our recent white paper, we show that factor investments may appear unbalanced when viewed through a generic factor lens. However, these same investments can represent a well-balanced and profitable combination in terms of exposure, risk, and performance when considered through a relevant factor lens.
Factors have become a staple in the portfolio constructor’s toolkit, where the goal is typically to maintain a consistent balance between factors to manage risk while harvesting the associated alpha. The majority of these successful factors can be grouped under value, momentum, quality, and low risk. At Robeco, we have continuously enhanced these core factor themes, as ongoing innovation helps sustain an alpha edge over generic factors; see Swade et al. (2024)1.
This edge is further amplified by going beyond traditional factor themes and bringing in proprietary signals that exploit short-term dynamics and/or alternative data sources2. To illustrate the efficacy of this combination, Blitz (2024) highlights that around 80% of the outperformance of the Robeco model cannot be explained by generic academic factors3.
Active Quant: finding alpha with confidence
Blending data-driven insights, risk control and quant expertise to pursue reliable returns.
Measuring factor exposure
Robeco Quant Equities’ unique factor differentiation has consistently placed it among the top performers in peer group performance comparisons (Blitz, 2024). However, prospects and clients are sometimes puzzled when they try to investigate our factor exposure using market factor analysis tools. For instance, they may diagnose what appears to be a factor imbalance, raising questions about the overall portfolio diversification. In our new paper, we shed light onto this very puzzle.
Specifically, we dive deeper into questions such as: How does one best measure factor exposure? Does it really matter how these factors are defined, or are they all the same? And most importantly, are these the ‘right’ factors for producing alpha?
To explore these questions, we use the Robeco Developed Markets Enhanced Indexing (DM EI) strategy, a global equity factor portfolio, and explore the current state of factor definitions. Figure 1 compares the factor exposures calculated using the z-score methodology on Robeco’s proprietary factor definitions and those of three market-leading providers of factor analysis tools. The comparison reveals that while Robeco’s factors share some common DNA with generic factors, they offer distinctive insights that enhance portfolio outcomes.
Figure 1 – Factor exposures of the Robeco Enhanced Indexing strategy
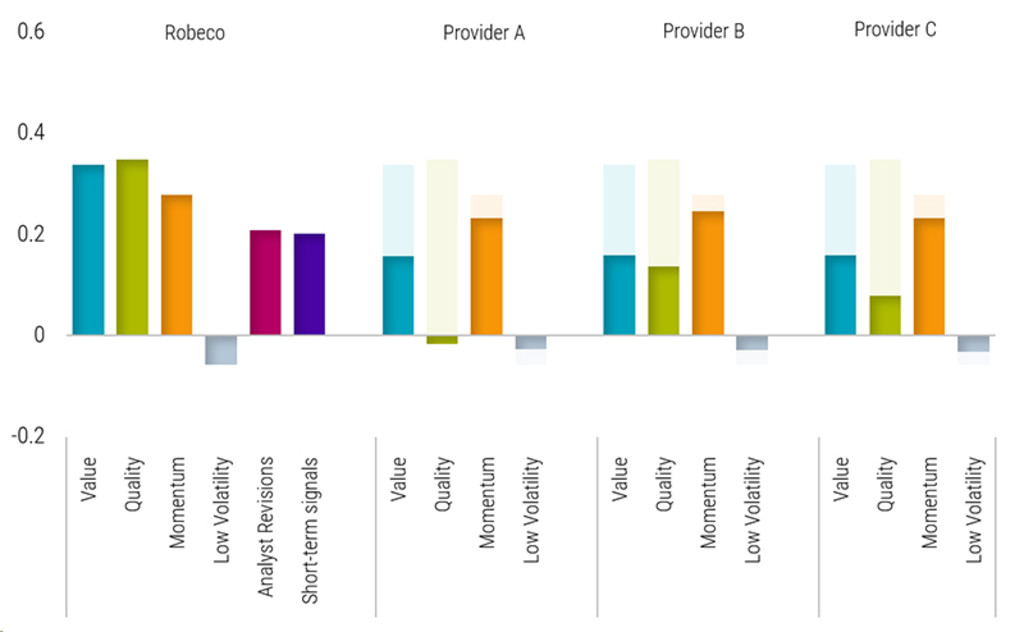
Source: Robeco Quantitative Investments. Robeco Enhanced Indexing Developed Markets strategy through factor scan methodology of provider A, B and C, and through Robeco’s proprietary factors, as of July 2024. The y-axis shows factor exposure, measured using the z-score methodology.
Importantly, generic factor scans typically do not feature analyst revision factors (let alone short-term or alternative alpha signals), thus missing a crucial part of the overall picture. In the white paper, we further discuss the value of third-party factor scans for evaluating portfolios but also highlight some of their pitfalls. Lastly, we emphasize the importance of diversified and balanced portfolio construction to mitigate unrewarded risk and enhance long-term performance.
More than meets the factor eye
The evolution of factors in both academia and industry is unlikely to slow, let alone stop, and there is no one-size-fits-all approach to measuring factors, exposure to factors, or evaluating the risk and performance contribution from them. While the market offers powerful tools to analyze portfolios based on factor lenses, these tools are primarily designed to explain well-known risks. For asset managers focused on generating alpha, ongoing innovation within factor themes is essential – this includes integrating alternative data and short-term signals to capture unique return-enhancing exposures that might be missed by standard, generic scans.
Effective portfolio construction stems from a comprehensive understanding of how exposures manifest as portfolio risks. And although factor scans remain an important tool in a well-researched investment process, variations observed in factor scans should only be a concern if they are not well understood. Two decades on, the success of our Enhanced Indexing portfolios in both developed and emerging markets supports this stance – showing there is surely more than meets the factor eye.
Footnotes
1 Swade, A., Hanauer, M. X., Lohre, H., & Blitz, D. (2024). Factor Zoo (.zip). The Journal of Portfolio Management, Quantitative Special Issue 2024, 50(3), 11-31.
2 Harvesting short-term alpha factors brings some challenges and Blitz et al. (2024) allude to how these can be tackled in practice.
3 Blitz, D., 2024, “The unique alpha of Robeco Quant Equity strategies”. Robeco client note
獲取最新市場觀點
訂閱我們的電子報,時刻把握投資資訊和專家分析。
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。