
Chief Researcher

獲取最新市場觀點
訂閱我們的電子報,時刻把握投資資訊和專家分析。





Machine learning (ML) models predicting stock returns have been widely celebrated for their high full-sample gross alphas. However, their performance net of costs has significantly dwindled post-2004 for the U.S. market. A recent paper demonstrates that ML models can still be lucrative by employing longer prediction horizons and incorporating efficient portfolio construction rules. While longer-horizon strategies focus more on traditional asset pricing factors and slower signals, we believe they still have the potential to unlock distinctive alpha.
The study by David Blitz, Matthias Hanauer, Tobias Hoogteijling and Clint Howard on ‘The term structure of machine learning alpha’ emphasizes the importance of design choices in the effectiveness of ML models in real-world applications. Previously, the focus of the majority of studies and strategies was centered around predicting stock returns over one-month horizons. Although these short-horizon strategies exhibited impressive gross alphas, they were mainly profitable before 2004. Their performance deteriorated significantly after 2004 due to high transaction costs resulting from their higher turnover.
In contrast, our research shows that ML models trained on longer prediction horizons (e.g., three, six, or twelve months) performed considerably better in generating net positive returns, especially in the more recent period from 2004 to 2021. The longer-horizon strategies required less frequent trading, thereby drastically reducing transaction costs. These strategies also loaded more on slower signals, such as quality and value, which proved to be more resilient and profitable in the long term.
Furthermore, applying efficient portfolio construction rules – akin to a buy-hold cost mitigation approach – proved to be beneficial across all prediction horizons. This technique significantly reduced turnover, thus compensating for the reduced raw portfolio returns.
Our study’s findings have critical implications for both academia and investment practitioners. For researchers, the paper highlights the need to broaden the focus beyond one-month return predictions and to understand the behavior of ML models across various prediction horizons. For investment practitioners, the findings advocate for aligning ML model training with the intended application and portfolio holding period. By doing so, investors can capitalize on the reduced turnover and improved net performance offered by strategies based on longer prediction horizons.
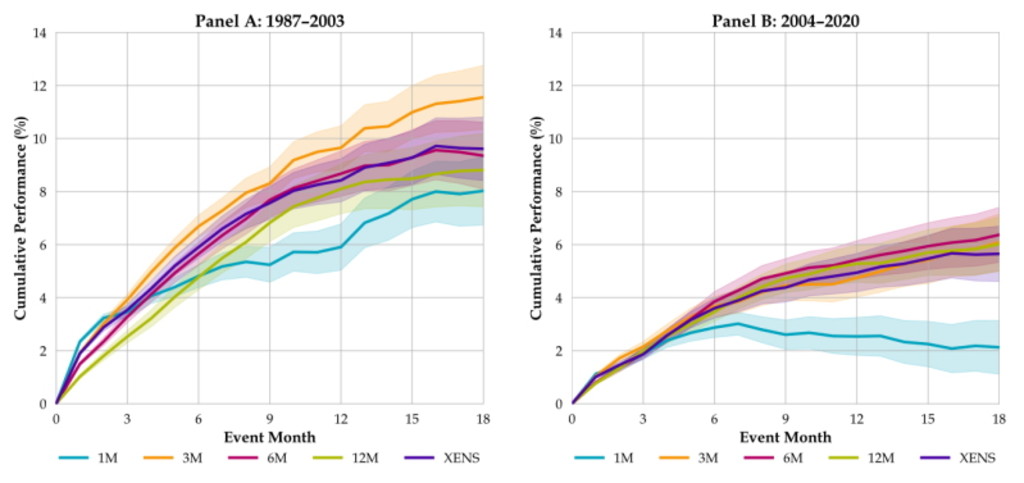
Source: CRSP, Open Source Asset Pricing, Robeco. Note: This figure plots the hypothetical cumulative average performance of the top-minus-bottom value-weighted decile portfolios for an ensemble of machine learning models trained on different prediction horizons, when holding the portfolios without rebalancing.
To summarize, although ML models focused on short-term predictions have lost their edge in recent years, we believe that by adopting longer prediction horizons and efficient portfolio construction rules there is potential to unlock significant net returns. These findings underscore the importance of design choices and call for more extensive research on various prediction horizons to optimize investment strategies using ML models.
訂閱我們的電子報,時刻把握投資資訊和專家分析。
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。
警告 — 有不法分子在網站及社交媒體上冒用荷寳 了解更多