Head of Multi Asset & Equity Solutions, Co-Head Investment Solutions

• Monthly outlook
The central bank divergence: inflation vs. growth
The world’s major central banks are facing differing abilities to tackle inflation, due to the danger of rate rises undermining growth, says multi-asset investor Colin Graham.
Authors
Summary
- Inflationary pressures are different in the US, UK, Eurozone and Japan
- Raising rates has knock-on effects for economic growth and bond prices
- ECB has less flexibility while the Fed relies on support from the US Treasury
Raising interest rates to tackle inflation that has been sticky since Russia invaded Ukraine in 2022 has long been the principal tactic, since higher borrowing costs limit public and corporate spending and ease pressure on prices. But this also threatens economic growth, and has knock-on effects for government bond markets, at a time when longer-term yields are already seeing new cycle highs.
It’s now a mixed picture in the giant economies of the US, Eurozone, UK and Japan, where the Fed, European Central Bank, Bank of England and Bank of Japan are each facing their own, differing, dilemmas, says Graham, Head of Multi Asset and Equity Solutions at Robeco.
“The annual symposium hosted by the US Federal Reserve at Jackson Hole showed the growing divergence between the way the world’s central banks are seen tackling inflation and economic growth,” he says. “Fed Chairman Kevin Warsh used his 28 August address to talk tough on inflation, raising expectations that rates will have to rise, or at least, not fall.”
“But while this materially changed the US policy narrative, it highlighted an increasing divergence with other central banks in Europe, Japan and around the world that are also trying to combat inflation, but with differing abilities to use interest rates as the primary weapon.”
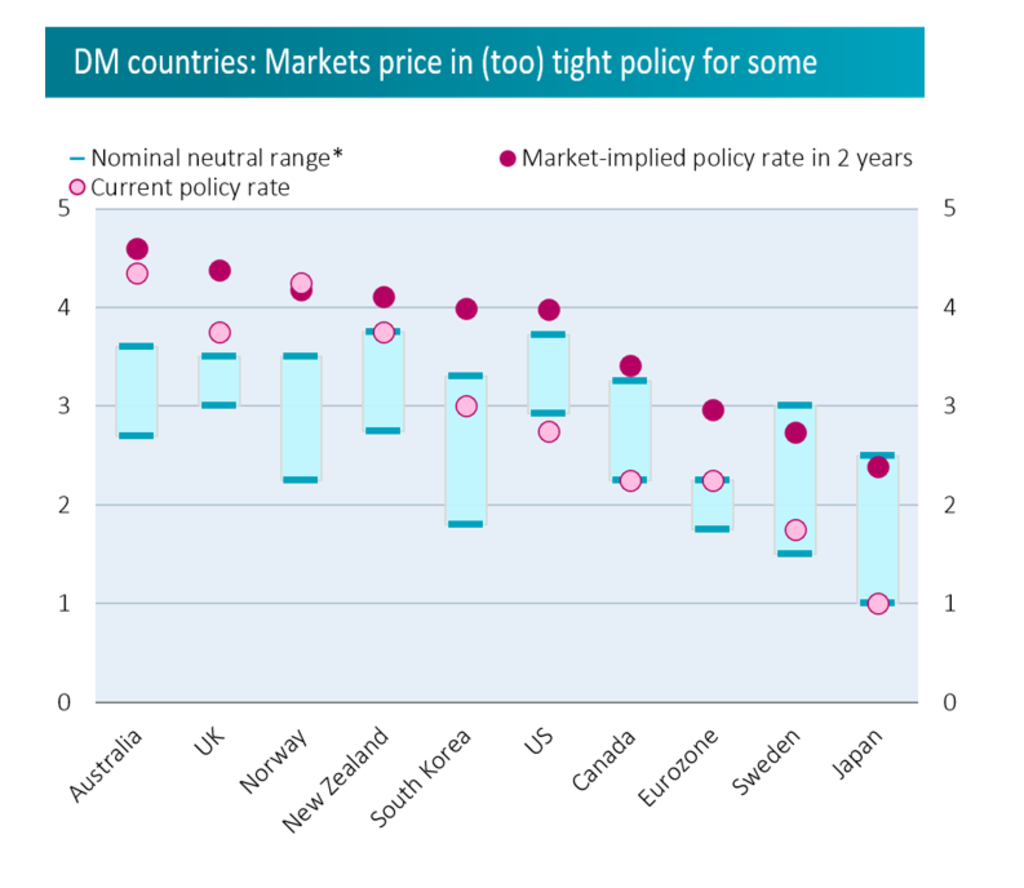
One way of trying to forecast future rate hikes, and their attendant effect on asset prices, is to calculate the ‘neutral’ rate that would neither negatively nor positively impact the local economy. This 'nominal neutral’ rate range is highest for the UK and lowest for Japan, the US and Canada, as shown in the chart below.
Figure 1: The rate ranges for the world’s main central banks
Source: Bloomberg, Robeco, September 2026.
Get the latest insights
Subscribe to our newsletter for investment updates and expert analysis.
“It means Japan has the most room to raise rates without worrying about causing headwinds for economic growth,” Graham says. “The US has some room to raise, but the Eurozone, Australia and UK risk setting interest rates too high and negatively impacting economic growth.”
Inflation problems are not the same
Part of the reason for the divergence is that the inflationary drivers differ between the US, Eurozone and Japan, so responses by central banks would have differing effects. Aside from threatening growth, rate rises also raise bond yields, increasing borrowing costs for governments which are already struggling with rising budget deficits and record national debt piles.
“For the US, inflation pressures reflect tariffs, resilient demand and investment,” Graham says. “The Fed has turned more hawkish, while the US Treasury remains the more visible market operator through bond buybacks and market stability measures.”
“This interaction effectively gives the Fed room to keep rates neutral while talking tough on inflation, without losing control of the long end of the US Treasury bond yield curve. It reminds me of ‘Operation Twist’ (where the Fed buys long-term bonds).”
Energy cost dilemma
“In the Eurozone, inflation is principally a price shock from higher imported energy costs due to the Middle East conflict. The ECB can tighten in line with its inflation mandate, but a lack of domestic drivers makes the economy more vulnerable to higher rates. We have seen this play out before in 2008, and again in 2011, when the ECB raised rates into a commodity shock.”
“Japan appears to be in the best position – unlike its previous experience over the past 40 years – because inflation reflects structural reflation and domestic growth. The Bank of Japan can normalize rates without creating a headwind for its economy. In addition, higher rates can increase the attractiveness of the yen, which has been in a structural downtrend.”
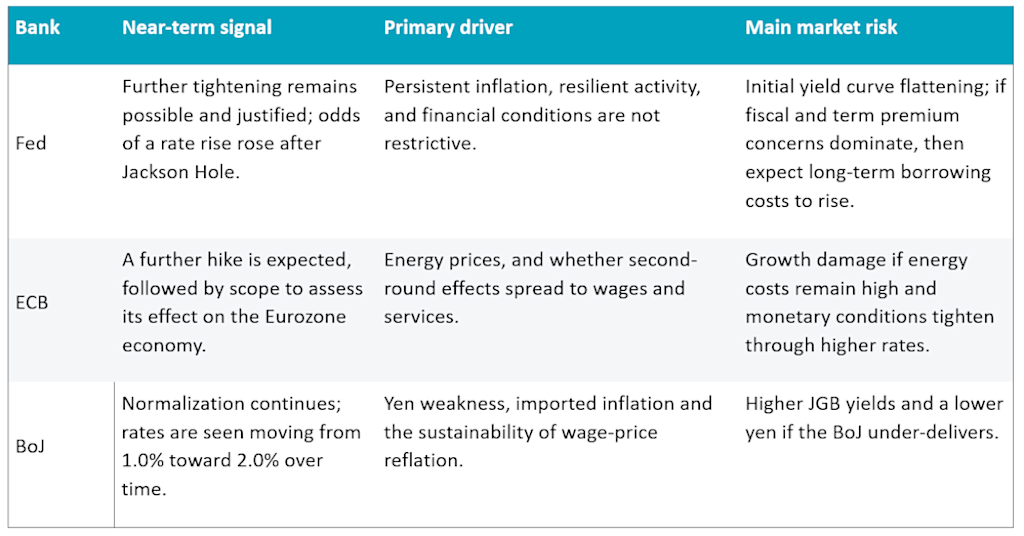
The potential repercussions are summarized in the table below.
Table 1: Signals, drivers and risks for the three biggest central banks
Source: Robeco Investment Solutions research, September 2026.
Effects on stocks and bonds
Higher rates also have implications for asset values. “Overall, risk assets (credit and equities) have coped well with higher rates over the last five years, mainly because the second-round effects of inflation have been muted, and we continue to believe this narrative,” Graham says.
“We recognize, though, that this optimistic outlook faces more headwinds as US exceptionalism crumbles, and that ‘risk-free’ rates are no longer risk free as government debt burdens balloon, and as supply shocks continue in the form of oil and tariffs.”
“So, the near-term impulse for all the central banks will be a synchronized tightening. However, the outcomes in the three regions could be very different in the medium term. The ECB would be raising rates in response to the energy shock, but without the economic buffer we see in Japan or the US. The Bank of Japan has additional room to raise rates without impacting the domestic economy.”
“And the Fed is confronting a high-pressure economy, and the front-end of the Treasury bond yield curve may remain reactive to these pressures. So, the US term premium is vulnerable to upward pressure, inferring continued cooperation between the Fed and the Treasury to prevent loss of control of longer-term rates.”