Strategist

• Insight
US Treasury steps in as long-end yields rise
The US Treasury’s expanded buybacks signal growing concern over rising long-end yields and a shift towards a more activist approach. But without addressing the underlying fiscal pressures, its ability to contain yields may prove short-lived.
Authors
Strategist
Summary
- Expanded buybacks signal a more activist Treasury
- Shortening the average maturity of Treasury funding comes at a cost
- Fiscal pressures should keep long-end yields elevated
The US Treasury Department yesterday (19 August) announced that it would double the size of its liquidity-support buyback operation for longer-dated Treasury securities. The maximum size of each operation will increase from USD 2 bln to at least USD 4 bln. If operations continue at the current pace, purchases could amount to around USD 66 bln on an annual basis. These numbers are not insignificant, as the expansion of US Treasury purchases would effectively equate to roughly 15% of gross 20- to 30-year US Treasury supply.
Buyback operations are not new. They have been an active policy tool to improve the liquidity in older bonds for some time. The purpose is to improve liquidity with the aim of facilitating trade and lowering the yield premium. However, the timing of the announcement is notable. Yield premiums of older ‘off-the-run’ bonds have recently not been elevated, and only two weeks ago the Treasury confirmed its existing funding plans.
Clearly, the announcement should be seen as a response to rising US Treasury yields, as the 30-year Treasury bond recently closed at its highest yield since 2007 (see Figure 1). This suggests that the Treasury Department wants to send the message that it cares about the level of long-end yields and is willing to respond to limit the yield rise. Going forward, we are likely to continue to see a more activist Treasury Department.
In response to the announcement, longer-maturity bonds rallied and the US Treasury yield curve flattened significantly, with the spread between 30- and 2-year bonds decreasing by 10 bps on the day, from 112 bps to 102 bps.
Figure 1: US Treasury 30-year yield
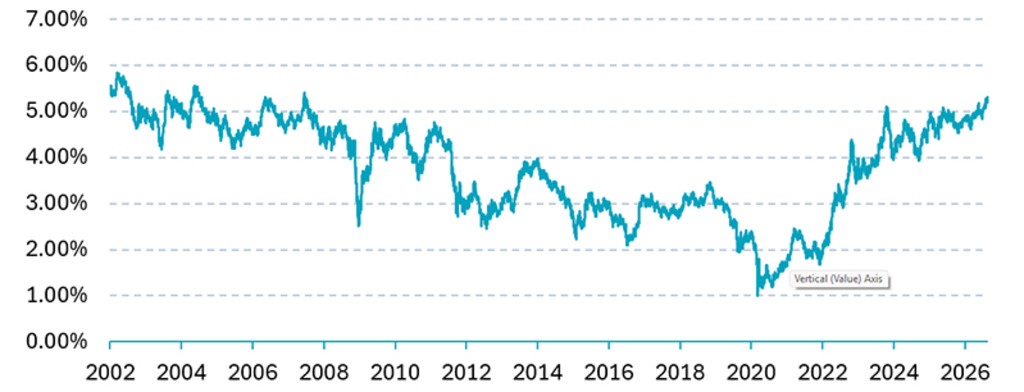
Past performance is no guarantee of future results. For illustrative purposes only. Source: Bloomberg, August 2026
What else could the Treasury do?
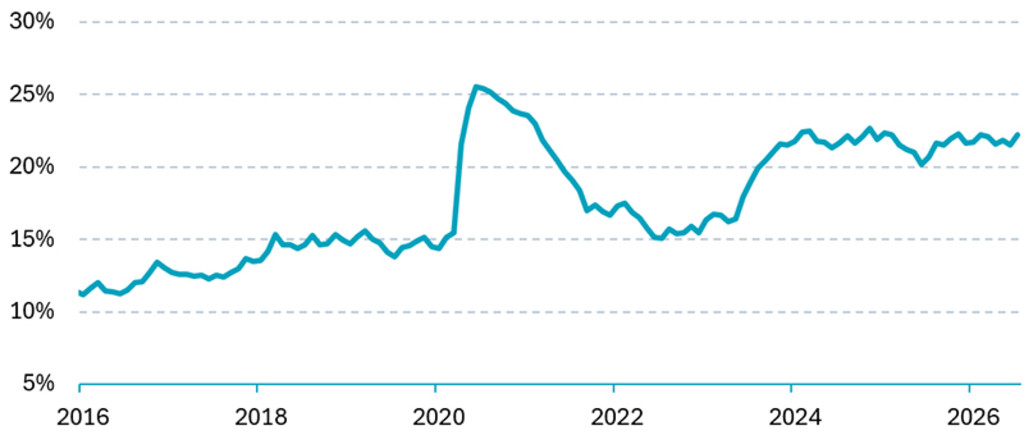
One important limitation is that the Treasury must finance these purchases in some way, most likely through additional T-bill issuance. This is a strategy the Treasury has been pursuing since 2023 (see Figure 2).
The question, then, is what else could the Treasury do to dampen the rise in long-dated yields? One potential next step would be to adjust the composition of newly issued debt. The Treasury determines how much government debt is issued across different maturities and could reduce the supply of longer-dated bonds. Any such change could be announced when it updates its issuance plans at the quarterly refunding in November.
Shortening the average maturity of its funding would come at a cost. A shorter maturity profile would make the Treasury’s interest payments more sensitive to Fed policy rates. It could also be perceived as adding pressure to the Fed to pursue a lower-rate policy. In addition, it would increase the rollover risk of the debt.
Figure 2: US T-bills as % of US debt outstanding
Source: US Treasury, Bloomberg, August 2026
Euro Government Bonds D EUR
- performance ytd (31-8)
- -1.71%
- Performance 3y (31-8)
- 1.95%
- morningstar (31-8)
- SFDR (31-8)
- Article 8
- Dividend Paying (31-8)
- No
Past performance is no guarantee of future results. The value of the investments may fluctuate. Annualized (for periods longer than one year). Performances are net of fees and based on transaction prices.
Buybacks are not Operation Twist
At first glance, Treasury buybacks may appear similar to ‘Operation Twist’1. However, there are some significant differences. First, the size of the Fed’s Operation Twist was significantly larger. At more than USD 600 bln, the Fed’s purchases and sales across different maturities dwarfed the Treasury’s current purchases. Second, the Treasury Department does not have the ability to create liquidity, unlike the Fed, and must finance these purchases as previously discussed.
There also appears to be some dissonance between the policy preferences of new Fed Chair Warsh and the actions of the Treasury Department. Warsh is known to prefer shortening the duration of the Fed’s balance sheet and has started a task force to re-examine balance sheet policy. A possible outcome of this task force could be to decrease the maturity profile of the Fed’s Treasury holdings on the balance sheet by shifting reinvestments to shorter-dated government bonds.
The underlying pressures remain
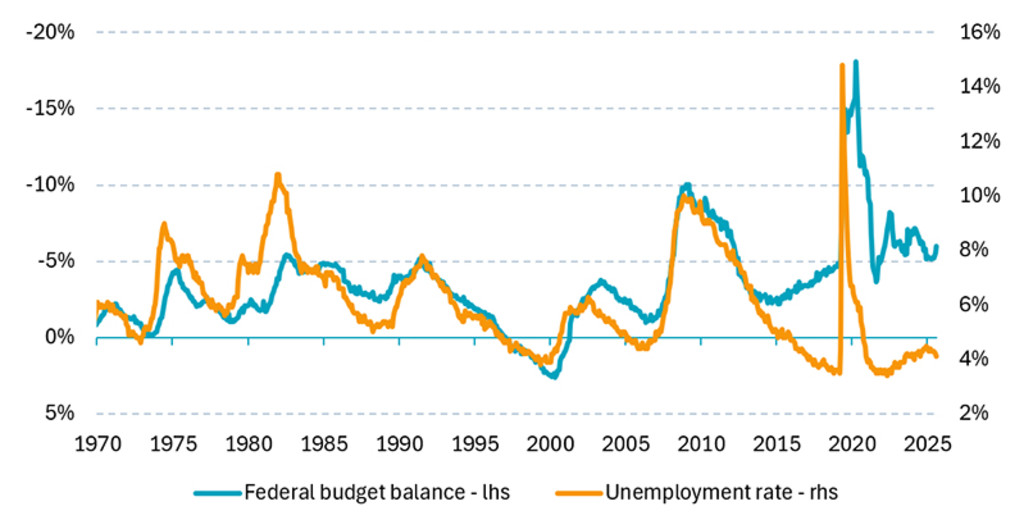
We believe that an activist Treasury can impact yields in the short term. However, its actions fail to address the underlying reason why long-end Treasury yields are high in the first place. Inflation uncertainty has increased and the US government is running a large deficit, estimated at 6.3% of GDP in 2026, even though the economy and labor market are relatively strong. There are no indications that these high deficits are likely to decrease any time soon. US government debt has just passed USD 40 tln (123% of GDP) and is expected to continue to rise for the foreseeable future.
For our positioning, this means we remain cautious on longer-maturity government bonds, with potential spillover effects from US yields on other bond markets. We have steepener positions in markets such as UK gilts and German government bonds.
Figure 3: Exceptionally high deficits given the state of the labor market
Source: US Treasury, BLS, Bloomberg, August 2026
Footnote
1 Operation Twist was a Federal Reserve program conducted from 2011 to 2012 in which the Fed sold shorter-dated Treasury securities and bought longer-dated securities to lower long-term interest rates without expanding its overall balance sheet.
What’s new in credits?
Stay ahead with our newsletter on the latest in credit investing.