Portfolio Manager

• 月度展望
In sickness and in wealth – opportunities in health care for active investors
It’s a sector that accounts for 9% of global GDP, and uniquely will be used by everyone at some point in their lives. And as the population ages and technology advances, health care is set to become one of the most interesting arenas for stock pickers, says analyst Alyssa Cornuz.
概要
- Health care to benefit from aging and rising burden of chronic conditions
- Pipelines remain crucial for profits but patent cliffs hamper progress
- AI is assisting development of new cures as digitalization trends grow
Spending on health care in the US alone reached USD 4.5 trillion in 2023, an amount greater than the GDP of Japan. Priorities within the sector have changed since the Covid pandemic, though it remains the ultimate long-term theme as the global population gets older and sicker.
“Globally, several structural factors are driving this trend, including an aging population, with projections indicating that by 2050, one in every six individuals worldwide will be over 65, compared with one in 11 currently,” says Cornuz, healthy living analyst with Robeco’s thematic equity team.
“Then there is the rising burden of chronic conditions, such as cardiovascular diseases, cancer or diabetes, and increased demand for health care services in emerging markets. This provides an opportunity for investors to discover companies that can apply new AI technologies, develop new cures, and improve the effectiveness of health care spending generally.”
“However, there remain some challenging headwinds, including reduced revenues for health care suppliers post-Covid, drug price controls, and regulatory uncertainty; rebates for Medicare in the US created a challenging backdrop for parts of the sector in 2023.”
“On top of that, the launch of GLP-1 drugs for obesity led to massive dispersion in performance between Big Pharma, MedTech and other health care sub-sectors. While more dispersion and macro uncertainty are likely in 2024, this provides the active stock picker with more opportunities than seen in recent years, with valuation support and more divergence between winners and losers.”
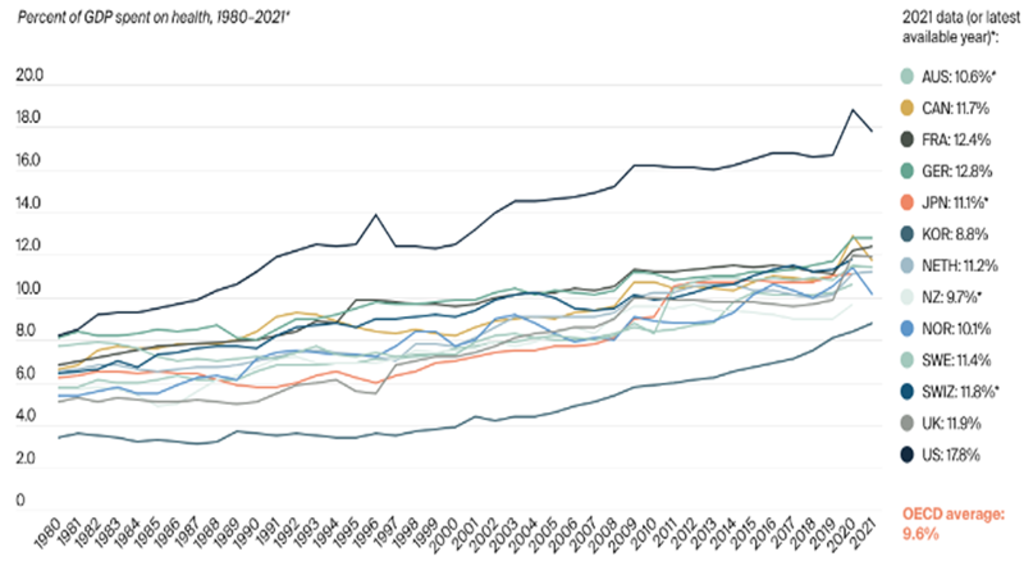
The percentage of GDP spent on health care; the US leads the pack at 17.8%.
Source: Morgan Stanley
Cornuz says three factors stand out, led by recovery in the biotech and life sciences sectors, the prospect of no upsets in the upcoming US Presidential and Congressional elections, and a refocus on attractive therapeutic areas beyond GLP-1.
“M&A activity in biotech has seen a pick-up in the year to date that is likely to persist, albeit with a shift towards acquiring later-stage assets, as Big Pharma replenishes its pipelines,” she says.
“Health care is not expected to be a central theme in the US elections. Although large cap pharma and managed care remain exposed to headwinds such as repeal of the Affordable Care Act, other sub-sectors such as life sciences tools or contract research organizations (CROs) or contract manufacturing organizations (CMOs) involved in making new drugs should remain insulated.”
“Finally, the market focus is moving past drugs for obesity to other product cycles such as tackling Alzheimer’s disease or developing respiratory vaccines.”
Pipelines, patents and profits
Cornuz says the pipeline of new drugs underpins growth in the sector, particularly as patents expire for blockbuster products. Patents provide immunity from competition while they are active, making them into de facto monopolies, but other companies can manufacture the same product once they expire.
“The race to discover a Covid-19 vaccine put a spotlight on the industry’s ability to rapidly innovate, but the patent cliff is always a drag on Big Pharma that is set to cost the industry USD 180 billion in lost revenue by the end of the decade,” Cornuz says.
“So, building on the acceleration of innovation through faster product cycles or M&A is a key theme for the sector. Notable therapeutic areas offering growth opportunities include oncology, immunology, diabetes/obesity, and neurology, particularly for tackling Alzheimer's disease.”
AI lends a helping hand
Pipelines are a risky business, since developing a new drug typically takes eight to ten years and costs USD 1-2 billion per product, with only one out of every ten candidates ever reaching the market with regulatory approval. So, can artificial intelligence help?
“AI has the potential to shorten product development by contributing to faster drug discovery and the reduction of clinical trial failure rates,” Cornuz says. “With data integration, trend recognition and predictive modeling, AI can speed up the understanding of diseases and help to identify future winners in the traditional drug discovery process, while machine learning algorithms can optimize clinical trial designs.”
“Beyond drug development, data-driven digital health care tools have the potential to improve patient outcomes while reducing inefficiencies. In a sector plagued with shortages of skilled labour, AI can help facilitate patient care from pre-appointment to diagnostics, and reduce hospitals’ administrative burdens.”
Spending on digitalization
Digitalizing the sector – the subject of a past engagement theme at Robeco – is also both a long-term cost and opportunity for a sector that relies on accurate medical records and the ability to track the effectiveness of doctors’ prescriptions. Investments in digital health totalled USD 45 billion during the pandemic, ranging from clinical trials technology to home health and wellness.
“From 2020-2022, health care was the sector with the highest capital invested in AI after IT,” Cornuz says. “Funding since the pandemic ended has steeply declined, pressured by rising interest rates.”
“The headwinds facing the sector are well understood; what is not is how investments in digital and AI tools are providing clear productivity gains. That is yet to come, and will be an issue for investors to consider in this vibrant but always challenging sector.”
獲取最新市場觀點
訂閱我們的電子報,時刻把握投資資訊和專家分析。
重要資料
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。