
Portfolio Manager
獲取最新市場觀點
訂閱我們的電子報,時刻把握投資資訊和專家分析。




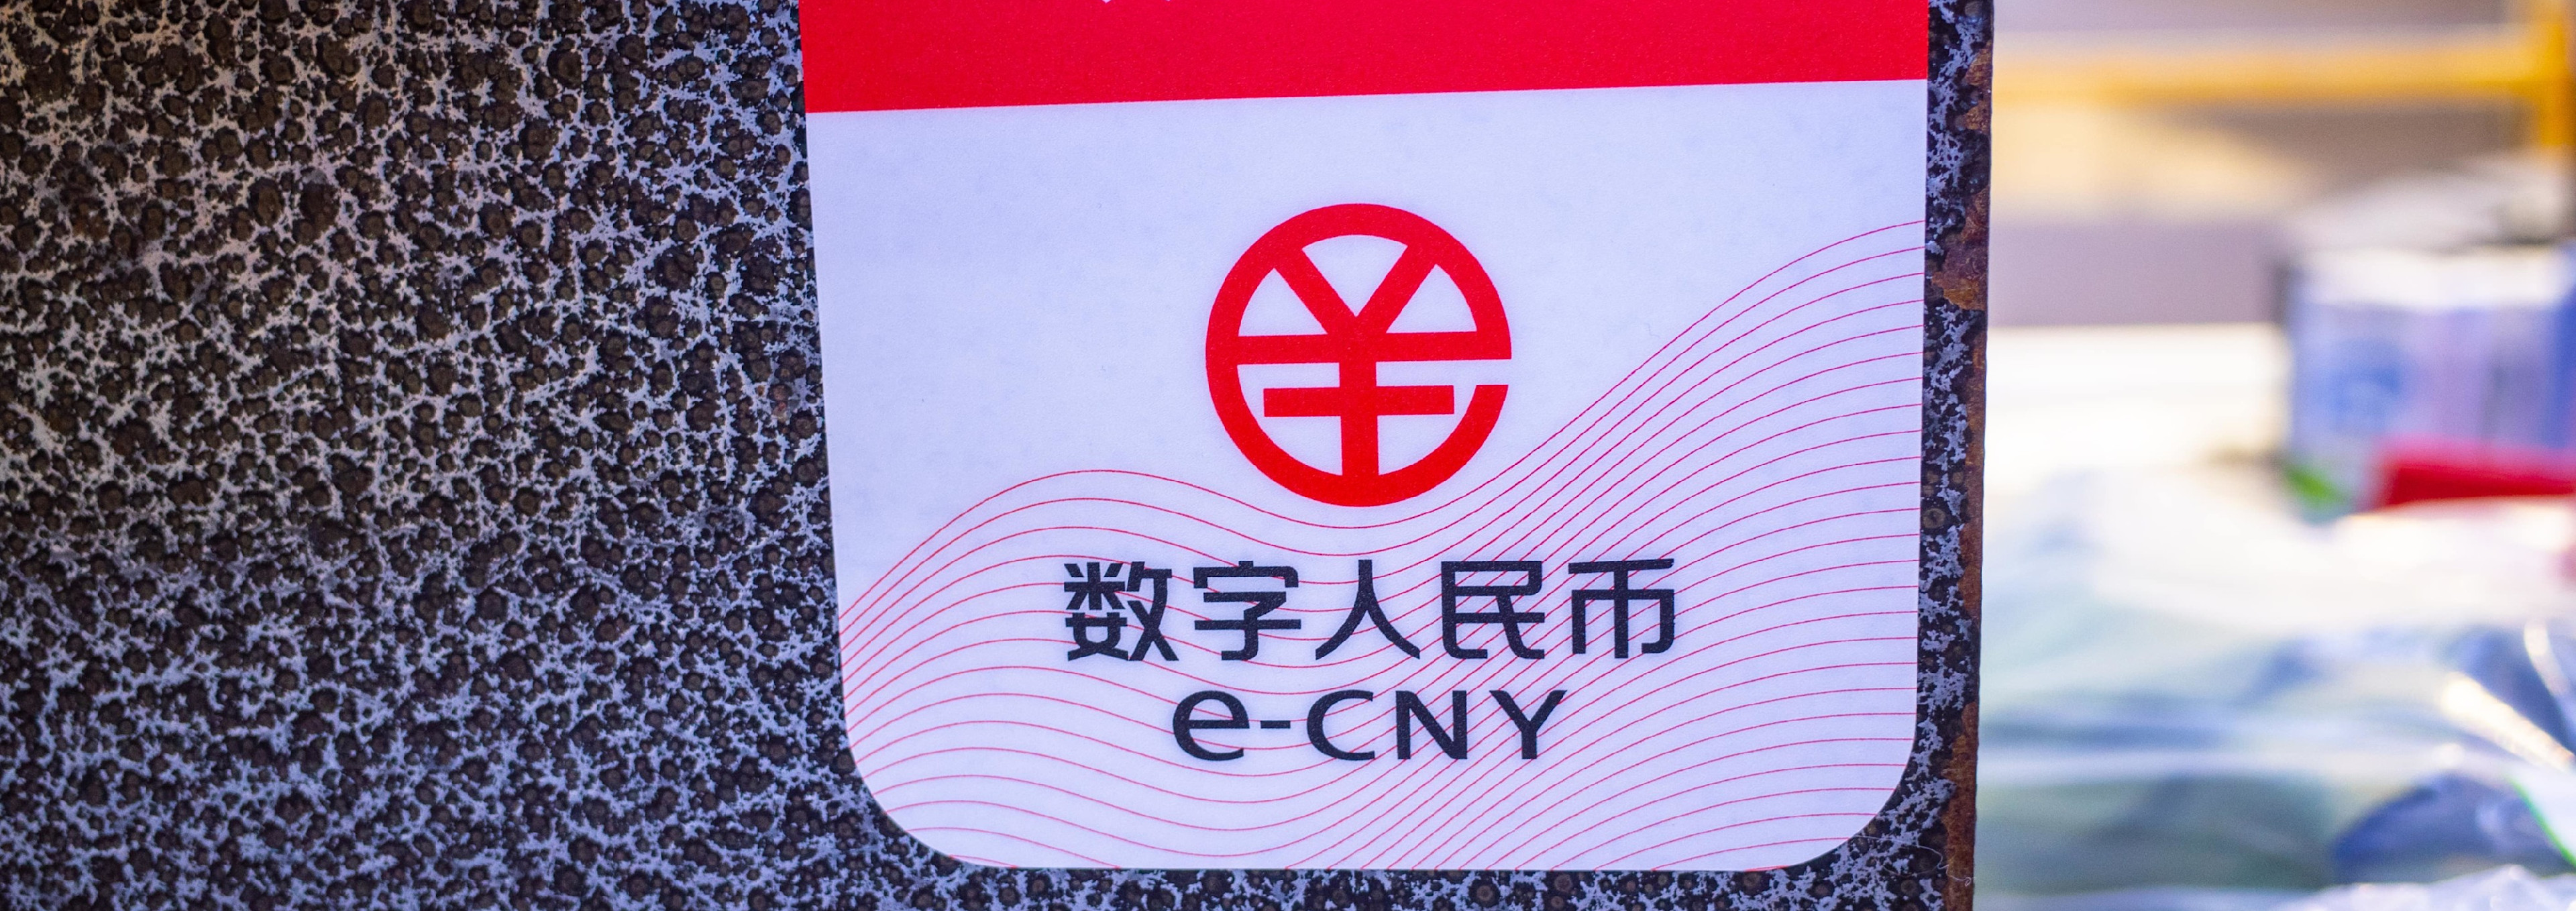

Digitalization is everywhere. And money is no exception. While most media attention around digital money has focused on cryptocurrencies – mainly bitcoin – over the past couple of years, other more discreet but equally transformational developments have been taking place in the background. This is the case for so-called central bank digital currencies (CBDCs).
The rapid rise of digital finance has pushed many central banks to mull over launching their own digital currencies. In fact, central banks from more than 70 countries, representing the bulk of global GDP, have been or are currently exploring the idea of setting up CBDCs, although a few of them have also decided not to proceed further for the time being.1
China’s PBoC seems to be currently the most advanced in this field among the world’s major central banks. The PBoC has already deployed its so-called DCEP system in various Chinese cities. With this digital cash, individuals can carry out transactions with selected merchants, without using Chinese yuan coins and banknotes, nor the QR code-based payment systems offered by Alibaba and Tencent.
China’s PBoC seems to be currently the most advanced in this field among the world’s major central banks
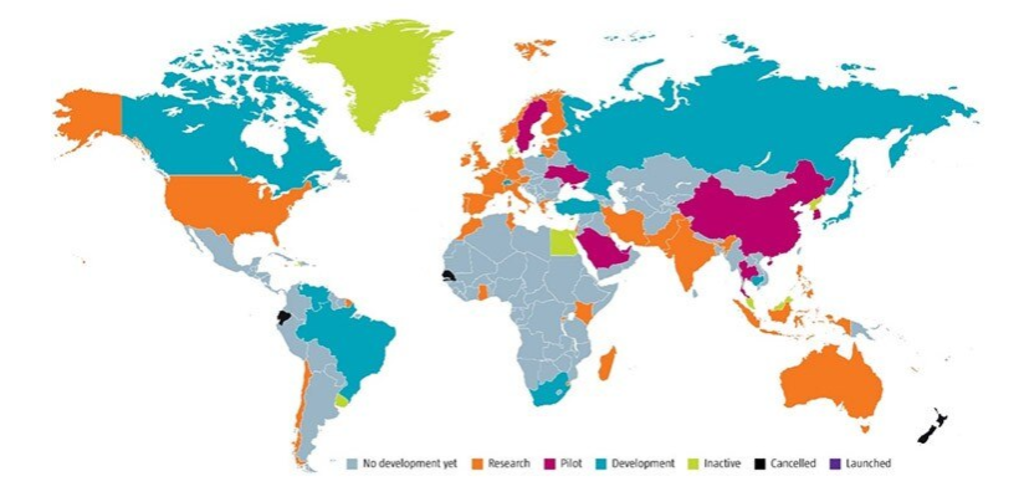
Source: Atlantic Council, Robeco, April 2021.
For now, most central banks seem to be considering CBDCs mainly as a potential replacement of physical cash. While existing infrastructures of commercial bank accounts and digital payments systems already provide relatively accessible and cost-efficient financial services in many countries around the world, CBDCs could also offer important advantages.
The first reason to consider CBDCs is that they would be a liability of a central bank and would therefore not require any deposit insurance. CBDCs would be issued and maintained by a central bank, which would provide the underlying technical architecture. Commercial bank deposits, on the other hand, are the liability of fallible entities and must be backed by reserves.
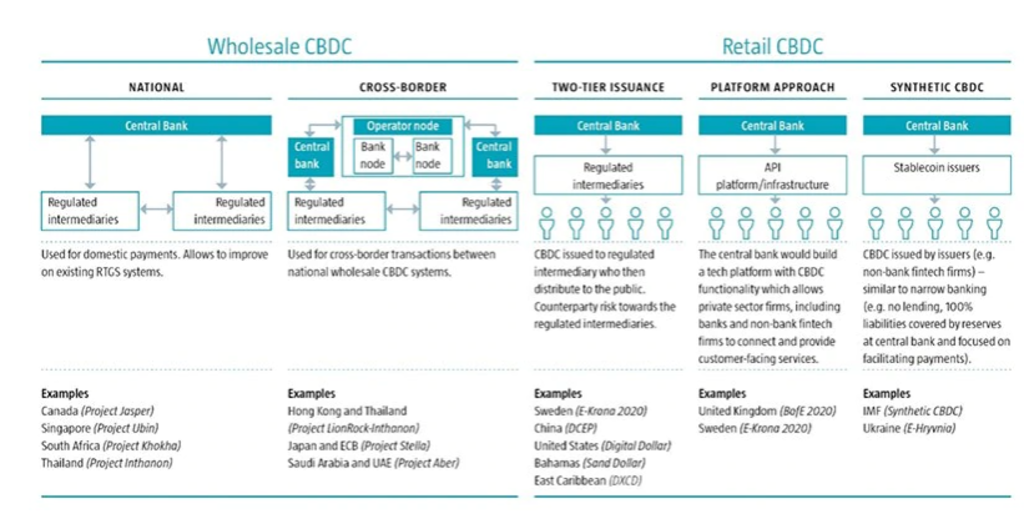
A second important reason to consider CBDCs is that they could reduce the need for financial intermediaries. This could lead to lower friction costs for users. However, it would also depend on the type of CBDC chosen, with the main distinction being made between wholesale and retail CBDCs, and whether regulated financial intermediaries should be part of the issuance of CBDCs.
Source: Henri Arslanian/Twitter, Robeco, August 2020.
訂閱我們的電子報,時刻把握投資資訊和專家分析。
Figure 2 describes in detail the different types of CBDCs considered around the world and provides concrete examples of countries exploring them. One fundamental difference between CBDCs and existing traditional currencies is that with retail CBDCs, individuals could have an account directly with a central bank.
As a consequence, central banks opting for this model would need to perform ‘know-your-customer’ (KYC) and ‘anti-money-laundering’ (AML) checks. These grueling tasks are currently performed by heavily regulated financial institutions, typically commercial banks, many of which have been heavily fined for their shortcomings.
This crucial choice between setting up direct retail accounts at the central bank, or still using commercial banks as regulated financial intermediaries, brings us to the third important reason for central banks to consider CBDCs: improving financial inclusion.
This is relevant not only in emerging countries but also in developed ones, where a non-negligible share of the population still doesn’t have access to a bank account. According to the World Bank, 1.7 billion adults across the world, or 31% of all adults, did not have a basic transaction account in 2017, even after 1.2 billion people opened a bank account between 2011 and 2017.2
In the absence of credible technological solutions to ensure digital identification, as well as KYC and AML duties, commercial banks will remain much needed
As central banks continue to investigate CBDCs launches, one would almost forget their potential impact on banking systems. In our view, the economic damage could be significant if central banks were to launch retail and wholesale CBDCs that would squeeze out most of the commercial banking system.
For one, despite challenger banks, fintech companies and tech giants encroaching on the most profitable segments of financial services, incumbent commercial banks still fulfill very important roles. Yet, in the absence of credible technological solutions to ensure digital identification, as well as KYC and AML duties, traditional commercial banks will remain much needed.
The Aadhaar project sponsored by the government of India, for digital identification, provides a good example. Aadhaar is a 12-digit unique identity number based on biometric and demographic data. But its status has become less powerful since September 2018, after the Supreme Court of India declared its mandatory linking with bank accounts or mobile phone SIM cards as unconstitutional.
The ruling came after several Indian civil rights groups voiced privacy concerns. The Indian government is clearly frustrated about the ruling, as it hampers financial inclusion which had greatly improved with the help of Aadhaar. As a result of the Court’s ruling, Aadhaar remains in use, although it is not mandatory to open bank accounts.
Another key function of commercial banks is that they take deposits and lend money to individuals and companies. CBDCs could change those dynamics. Potential funding issues could be ‘solved’ by offering direct central bank funding. But that would increase the power of central banks, while many of them – due to their independent status – are not subject to any significant external control.
Finally, the potential economic impact resulting from central banks deciding to play a more important role in cross-border money transfers, through wholesale digital currencies, could also be material. On the positive side, such currencies could replace existing and less efficient international money transfer systems, such as SWIFT. But wholesale digital currencies could also challenge, and potentially kill, other more efficient commercial initiatives, thus restricting potential innovation.
All in all, we believe that most large central banks will therefore be very cautious when they eventually implement CBDCs. For example, they might restrict individuals to limited deposits with them. This would curtail potentially destabilizing deposit flights from commercial banks to central banks once retail CBDCs are introduced.
From this perspective, the disruption in the financial industry, that can be expected from the rise of CBDCs, should remain relatively limited for the foreseeable future.
1Source: Atlantic Council, April 2021.
2See: “The global Findex Database 2017” report, The World Bank.
本網站僅供《證券及期貨條例》(香港法例第571章)及其附屬法例所界定之專業投資者瀏覽及使用。 投資涉及風險。過往表現並不代表未來表現。本網站所載資料僅供參考之用,並不構成任何投資建議,亦非作出買賣任何證券或採納任何投資策略之要約或招攬。投資者不應僅憑本網站提供之資料作出投資決定,在作出任何投資決定前,應徵詢獨立意見(包括有關稅務影響之意見)。投資者應確保完全理解投資產品的相關風險,亦應考量自身投資目標及風險承受水平。投資乃閣下之個人決定。除非銷售投資產品的中介人已向閣下告知該投資產品適合閣下,並已解釋其符合閣下投資目標之原因,否則閣下不應投資。請參閱相關發售文件或其他法律文件,以獲取包括風險因素在內的進一步詳情。 本網站由荷寶投資管理香港有限公司發布,該公司受香港證券及期貨事務監察委員會(「證監會」)規管(中央編號:APU851)。本網站未經證監會審閱。 無法保證任何投資產品可實現其投資目標。概不就任何投資產品之表現或投資回報作任何聲明或承諾。投資的價值或會波動。本網站所載過往表現、推算或預測,均不應視作未來表現之保證或指標,且概不提供任何明示或暗示之保證。本網站內容建基於相信為可靠之來源,惟因應資料傳遞技術特性及須採用多項數據來源(包括第三方內容),故概不保證其準確性。所述觀點僅乃截至上述日期,或會隨市況變化而改變,可予更改而毋須另行通知。該等意見可能有別於其他荷寶投資專業人士之意見。因使用本材料或當中所載任何評論、意見或估算而引致之直接、間接或相應損失,荷寶概不承擔法律責任。荷寶並無責任更新本網站或任何網站內容。未經荷寶事先書面許可,不得複製、分發或刊發本網站任何材料。 除非另有說明,資料來源:荷寶。
警告 — 有不法分子在網站及社交媒體上冒用荷寳 了解更多