
Sector Lead

• Insight
Energy security: How AI and electrification are driving infrastructure investment
Robeco’s lead Energy and Utilities sector analyst, Farahnaz Pashaei Kamali, argues that energy security is evolving beyond access to affordable oil and gas. It now increasingly depends on the resilience of the networks, infrastructure, trade routes, supply chains and raw materials that underpin the global energy system.
Summary
- Geopolitical shocks have re-focused energy security from cost efficiency to system resilience
- AI and electrification are powerful catalysts for energy system investments
- Resilience spending supports infrastructure, hard assets and commodities in portfolio allocations
Pashaei Kamali labels this evolution as ‘Energy Security 2.0’ and characterizes the transition as a shift from a ‘just-in-time’ globalized system toward a more resilient ‘just-in-case’ model. In this new era, governments and corporations are prioritizing strategic reserves, backup capacity, diversification and strategic autonomy over pure efficiency optimization. For investors, this shift matters because resilience is becoming an increasingly important driver of capital expenditure, earnings visibility and long-term returns.
Energy Security 2.0 is a transition from a ‘just-in-time’ globalized system toward a more resilient ‘just-in-case’ model Farahnaz Pashaei Kamali
Farahnaz Pashaei Kamali
Sector Lead
Recent geopolitical shocks have accelerated this transition. Europe’s energy crisis following the loss of Russian gas supply exposed the macroeconomic costs of concentrated dependencies. More recently, tensions in the Middle East and disruptions around the Strait of Hormuz and Bab el-Mandeb have highlighted the vulnerability of global shipping lanes and energy chokepoints.
In parallel, artificial intelligence (AI), industrial reshoring, and electrification trends are accelerating the need for dependable power systems, creating a new phase of capital investments across grids, storage, generation and energy infrastructure. The result is a structural repricing of resilience, redundancy and dependable energy systems after decades in which efficiency dominated corporate and policy decision-making.
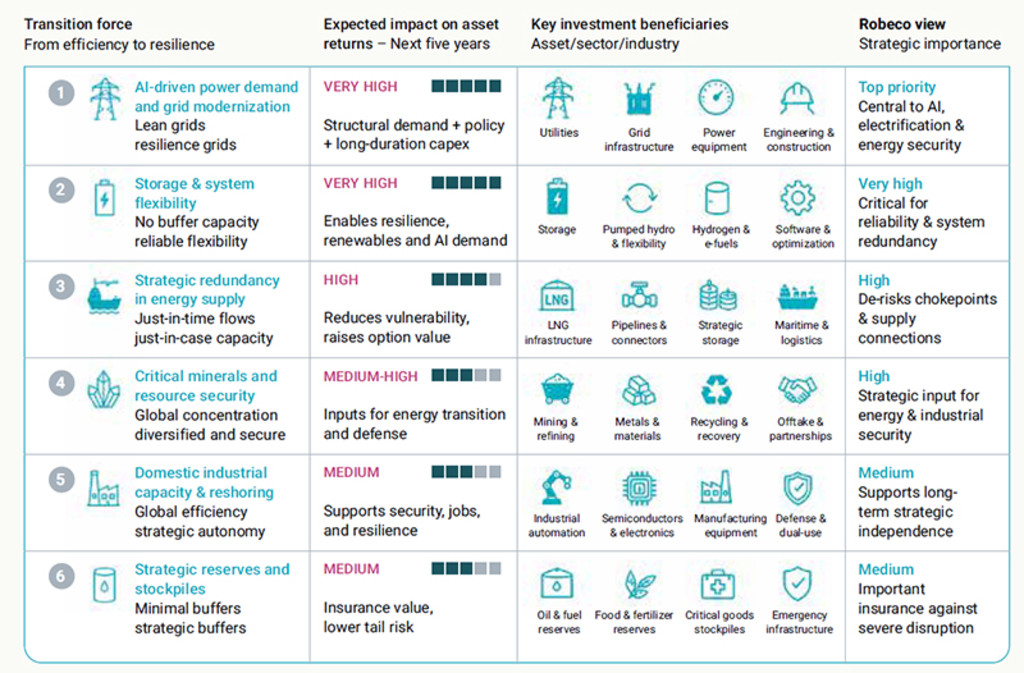
Figure 1: The structural shift from efficiency to resilience
Source: McKinsey Global Institute, Morgan Stanley Research, Robeco, June 2026.
Note: The estimated impact reflects our assessment of the potential effect on asset class returns over the next five years.
Power security becomes the new energy security
Historically, energy markets were characterized by globally integrated trade flows that optimized efficiency and minimized costs. Yet energy insecurity is often experienced locally. The Strait of Hormuz, Bab el-Mandeb and the Suez Canal remain critical chokepoints for oil, LNG and broader commodity trade. Building resilience is inherently more capital-intensive than efficiency. Strategic reserves, redundant infrastructure, domestic manufacturing and grid reinforcement require substantial investment. As this continues to play out, the disinflationary impulse associated with established trade routes and globalization is likely to weaken and inflation volatility may remain structurally higher.
AI-driven electricity demand and grid modernization are acting as powerful catalysts in this process and appear likely to have the greatest impact on asset returns over the next five years because they combine structural demand growth with strong policy support and long-duration investment requirements. This should support the strategic role of not only oil and other commodities but also infrastructure and real assets within diversified portfolios.
Governments globally are investing in resilience
Governments and corporations are increasingly responding through investments in strategic infrastructure. The IEA also estimates that global energy investment has already surpassed USD 3 trillion annually, which likely understates the real investment need. Natural gas, LNG infrastructure, nuclear power, storage systems, and transmission networks will be the primary beneficiaries of capital deployment.
Because capital expenditure remains highly selective, and because investment in upstream oil and gas and parts of the commodity supply chain has lagged projected demand growth, spare capacity in several key markets will remain limited. This increases the probability of supply-driven price shocks.
Get the latest insights
Subscribe to our newsletter for investment updates and expert analysis.
Sovereignty and security in the age of AI
Over the next five years, energy security will increasingly be defined as power security. As transport, heavy industry, and data systems electrify, power shortages transform from localized disruptions into systemic macroeconomic risks. AI serves as the primary structural accelerator of this trend. AI data centers are exceptionally energy-intensive and forward-looking estimates indicate that future AI-related infrastructure investment could rival or exceed traditional energy investment in the years ahead.
Over the next five years, energy security will increasingly be defined as power security Farahnaz Pashaei Kamali
Farahnaz Pashaei Kamali
Sector Lead
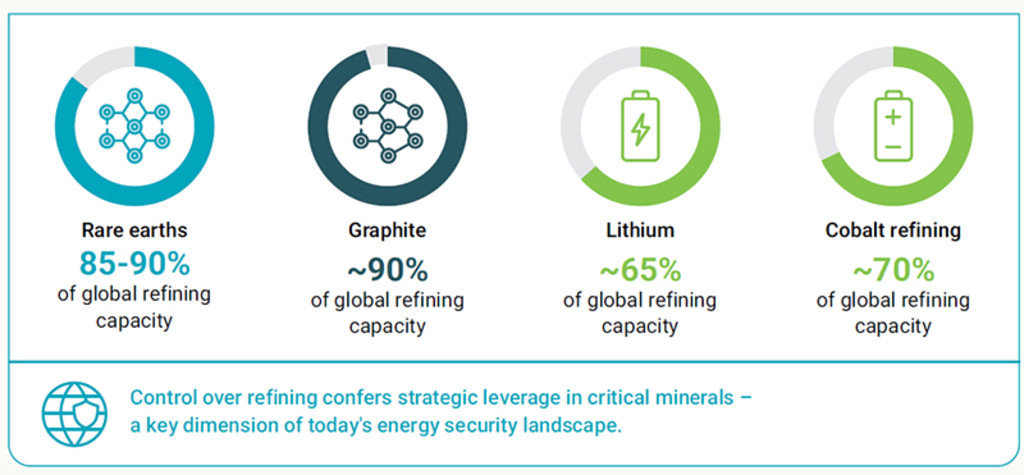
Renewable generation alone cannot bridge this compounding demand gap. This structural demand deficit cements the long-term cash-flow visibility and return profiles of regulated grids, battery storage, and dispatchable generation. Grid infrastructure, in particular, will benefit from strong political support, higher regulated returns, and robust earnings visibility as utilities race to solve emerging bottleneck constraints. Modern energy systems are underpinned by copper, lithium, graphite, nickel and rare earth elements, supply chains where China plays a dominant role.
Figure 2: Global critical-mineral processing remains highly concentrated
Source: IEA Critical Minerals Outlook, USGS, May 2025.
As a result, governments are placing greater emphasis on domestic mining, strategic reserves, recycling technologies and friendshoring arrangements. Hence, commodities, technology sovereignty and energy security are increasingly intertwined.
The implications of Energy Security 2.0 differ materially across regions. The US appears relatively well positioned due to abundant domestic energy resources, expanding LNG export capacity and deep industrial ecosystems. Europe remains more vulnerable from an import perspective, although recent shocks have accelerated investment in LNG infrastructure, renewables and storage. Asia faces the greatest exposure to imported energy flows, but also represents the largest source of future investment growth.
Figure 3: Ranking the highest conviction beneficiaries of Energy Security 2.0
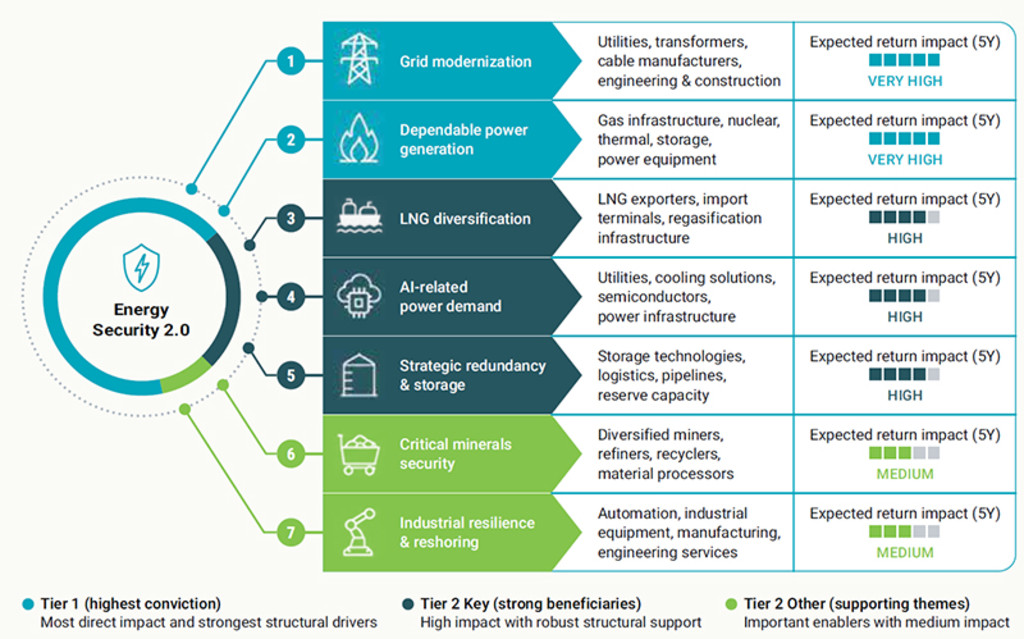
Source: Robeco, June 2026.
Note: Ranking reflects Robeco's assessment of the expected influence of each theme on asset and sector returns over the next five years.
Our base case, to which we assign a 50% probability, is a regime in which disruption effects dominate the supply-side benefits of resilience investment. Persistent geopolitical fragmentation, climate-related disruptions and strategic competition are likely to keep inflation more volatile, despite substantial investment aimed at strengthening energy and infrastructure resilience.
In this environment, we expect commodities and infrastructure to be the clearest beneficiaries, reflecting the increasing strategic value of secure energy supplies, critical resources and resilient infrastructure networks. The implications for equities are more mixed, as companies benefiting from higher resilience investment coexist with those facing higher input costs, financing costs and supply-chain pressures.
This article is an excerpt of a special topic in Robeco’s 5-year Expected Returns publication.
Expected Returns 2027-2031
Important information
THIS WEBSITE IS SOLELY INTENDED FOR PROFESSIONAL INVESTORS, WHICH HAS THE MEANING ASCRIBED TO IT IN THE SECURITIES AND FUTURES ORDINANCE (CAP. 571 OF THE LAWS OF HONG KONG) AND ITS SUBSIDIARY LEGISLATION. Investment involves risks. Past performance is not indicative of future performance. The information contained in this website is provided for reference only and does not constitute investment advice or an offer or solicitation to buy or sell in any securities or to adopt any investment strategy. Investors should not base their investment decisions solely on the information provided on this website and are advised to seek independent advice (including advice on tax implications) before making any investment decisions. Investors should ensure they fully understand the risks associated with the investment products and should also consider their own investment objectives and risk tolerance level. The investment decision is yours. You should not invest unless the intermediary who sells you the investment products has advised you that it is suitable for you and has explained how it is consistent with your investment objectives. Please refer to the relevant offering documents or other legal documents for further details including the risk factors. This website is published by Robeco Hong Kong Limited which is regulated by the Hong Kong Securities and Futures Commission (“SFC”) (CE No. APU851). This website has not been reviewed by the SFC. No assurance can be given that the investment objective of any investment products will be achieved. No representation or promise as to the performance of any investment products or the return on an investment is made. The value of investments may fluctuate. Past performance, projections, or forecasts included in this website should not be regarded as guarantees or indications of future performance, and no express or implied warranty is provided. The contents of this website are based on sources believed to be reliable, but due to the nature of information delivery technology and the necessity of using multiple data sources, including third party content, their accuracy is not guaranteed. The opinions expressed are as of the date shown above and may change as market conditions evolve, and are subject to change without notice. These opinions may differ from those of other Robeco investment professionals. Robeco accepts no liability for any direct, indirect, or consequential loss arising from the use of this material or any comments, opinions, or estimates contained herein. Robeco has no duty to update this website or any website content. Materials on this website may not be reproduced, distributed, or published without prior written permission from Robeco. Unless otherwise specified, Source: Robeco.