Client Portfolio Manager
• Insight
Credit income amid interest rate uncertainty
A flexible credit approach can help investors capture income without relying on falling interest rates.
Authors
Summary
- Attractive yields but tight spreads and uncertain rates demand selectivity
- Global flexibility helps uncover income opportunities across credit markets
- Quality, shorter duration and active management help balance income and risk
Credit yields remain attractive,1 but accessing them has become more complicated. Spreads are tight, inflation uncertainty persists and longer-dated bonds remain vulnerable to shifts in rate expectations. For investors, returns are increasingly likely to come from the income available in credit markets and careful issuer selection, rather than from falling rates or further spread compression.
This puts a premium on a flexible approach that can adjust allocations as market conditions shift.
With demand coming from several directions, cash investors are considering moving beyond money market funds in search of higher income, while traditional bond investors want to limit long-term interest rate exposure. Although their starting points differ, the objective is similar: consistent income without taking more credit or duration risk than necessary.
Inflation remains difficult to predict, while fiscal and geopolitical developments add to uncertainty around interest rate policy. Rising government borrowing and bond supply may also put upward pressure on longer-term yields. At the same time, tight credit spreads provide less of a cushion against market setbacks, reinforcing the need to manage credit and duration risk carefully.
The Robeco Credit Income strategy is positioned accordingly. Duration is actively managed within a range of approximately three to five years and currently stands slightly below four years as at 8 September 2026. The strategy favors the short and intermediate parts of yield curves, reducing sensitivity to movements in longer-term rates. Credit beta is also modestly below one relative to the broader credit market, consistent with a cautious stance on broad market risk.
Using flexibility to find income globally
Relative value varies across credit markets as economic and financing conditions diverge between regions and issuers. A flexible mandate allows the strategy to allocate across global investment grade, high yield and emerging market credit. This flexibility is particularly important when index-level valuations are tight.
Current positioning favors subordinated financials and short-dated BB-rated credit. The team also sees selective value among B-rated issuers where the additional spread adequately compensates for the risk.
With the outlook for inflation and monetary policy still unsettled, investors need an approach that can adapt
The team remains constructive on its preferred HALO sectors (communications, utilities and mining), where resilient business models and favorable sector dynamics provide support. The strategy is more cautious on regions that are net importers of energy and therefore more vulnerable to higher energy costs and renewed inflationary pressure. Beyond the US, the strategy has found attractive opportunities in European and emerging credit, providing diversification across different economic and interest rate cycles.
Credit Income IH GBP
- performance ytd (30-9)
- -0.52%
- Performance 3y (30-9)
- 7.17%
- morningstar (30-9)
- SFDR (30-9)
- Article 8
- Dividend Paying (30-9)
- No
Past performance is no guarantee of future results. The value of the investments may fluctuate. Annualized (for periods longer than one year). Performances are net of fees and based on transaction prices.
Separating AI’s credit winners from its losers
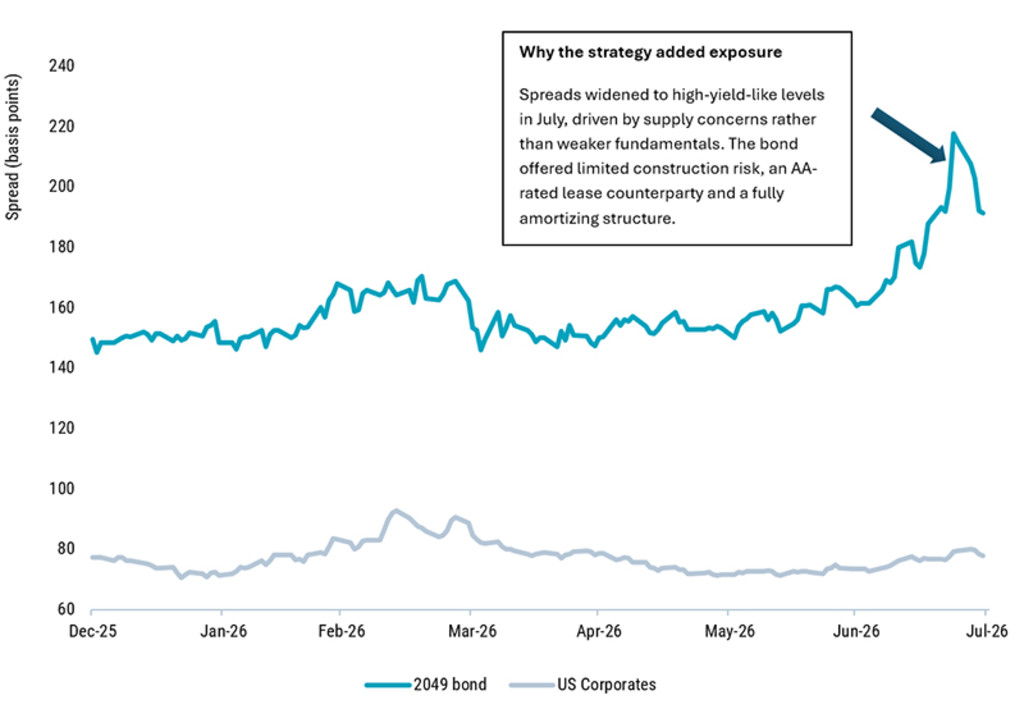
The expansion of artificial intelligence is another example of why bottom-up selection matters. AI investment may create significant long-term opportunities, but it also requires substantial capital expenditure. For bondholders, future growth needs to be weighed against the financing and execution risks. Figure 1 shows how supply-driven spread widening in an A-rated data center bond allowed the strategy to add exposure.
Figure 1 – Supply concerns widen spread on a A-rated data center bond. Spread of 2049 bond versus US investment grade corporate index (basis points).
All expressions of opinion are subject to change. This information is intended for educational purposes, and it is not to be construed as an offer, solicitation, recommendation, or endorsement of any particular security, products or services. The positions shown on this slide are for illustrative purposes only in order to demonstrate the investment strategy on the date stated. No inference can be made on the future development of the issuer/issue. This is not a buy, sell, or hold recommendation. Source: Robeco, Bloomberg. Data as of July 2026.
Despite this individual opportunity, the strategy maintains an overall cautious stance on technology, where the potential upside for creditors appears limited relative to the risks. The focus is on distinguishing companies that can comfortably fund AI-related investment from those whose credit quality could deteriorate as spending rises. The same discipline applies elsewhere with limited exposure to cyclical or lower-quality companies where spreads do not adequately compensate for risk.
Income without depending on a single market outcome
With the outlook for inflation and monetary policy still unsettled, investors need an approach that can adapt. Credit Income’s flexible approach allows the strategy to reposition as conditions change, guided by bottom-up research on where risk is worth taking. This adaptability makes the strategy particularly relevant today: able to pursue income where it is best rewarded while remaining disciplined when risks rise.
Footnote
1Past performance is no guarantee of future results. The value of your investments may fluctuate.
What’s new in credits?
Stay ahead with our newsletter on the latest in credit investing.