Portfolio Manager


• Insight
Duration management is key to bond returns
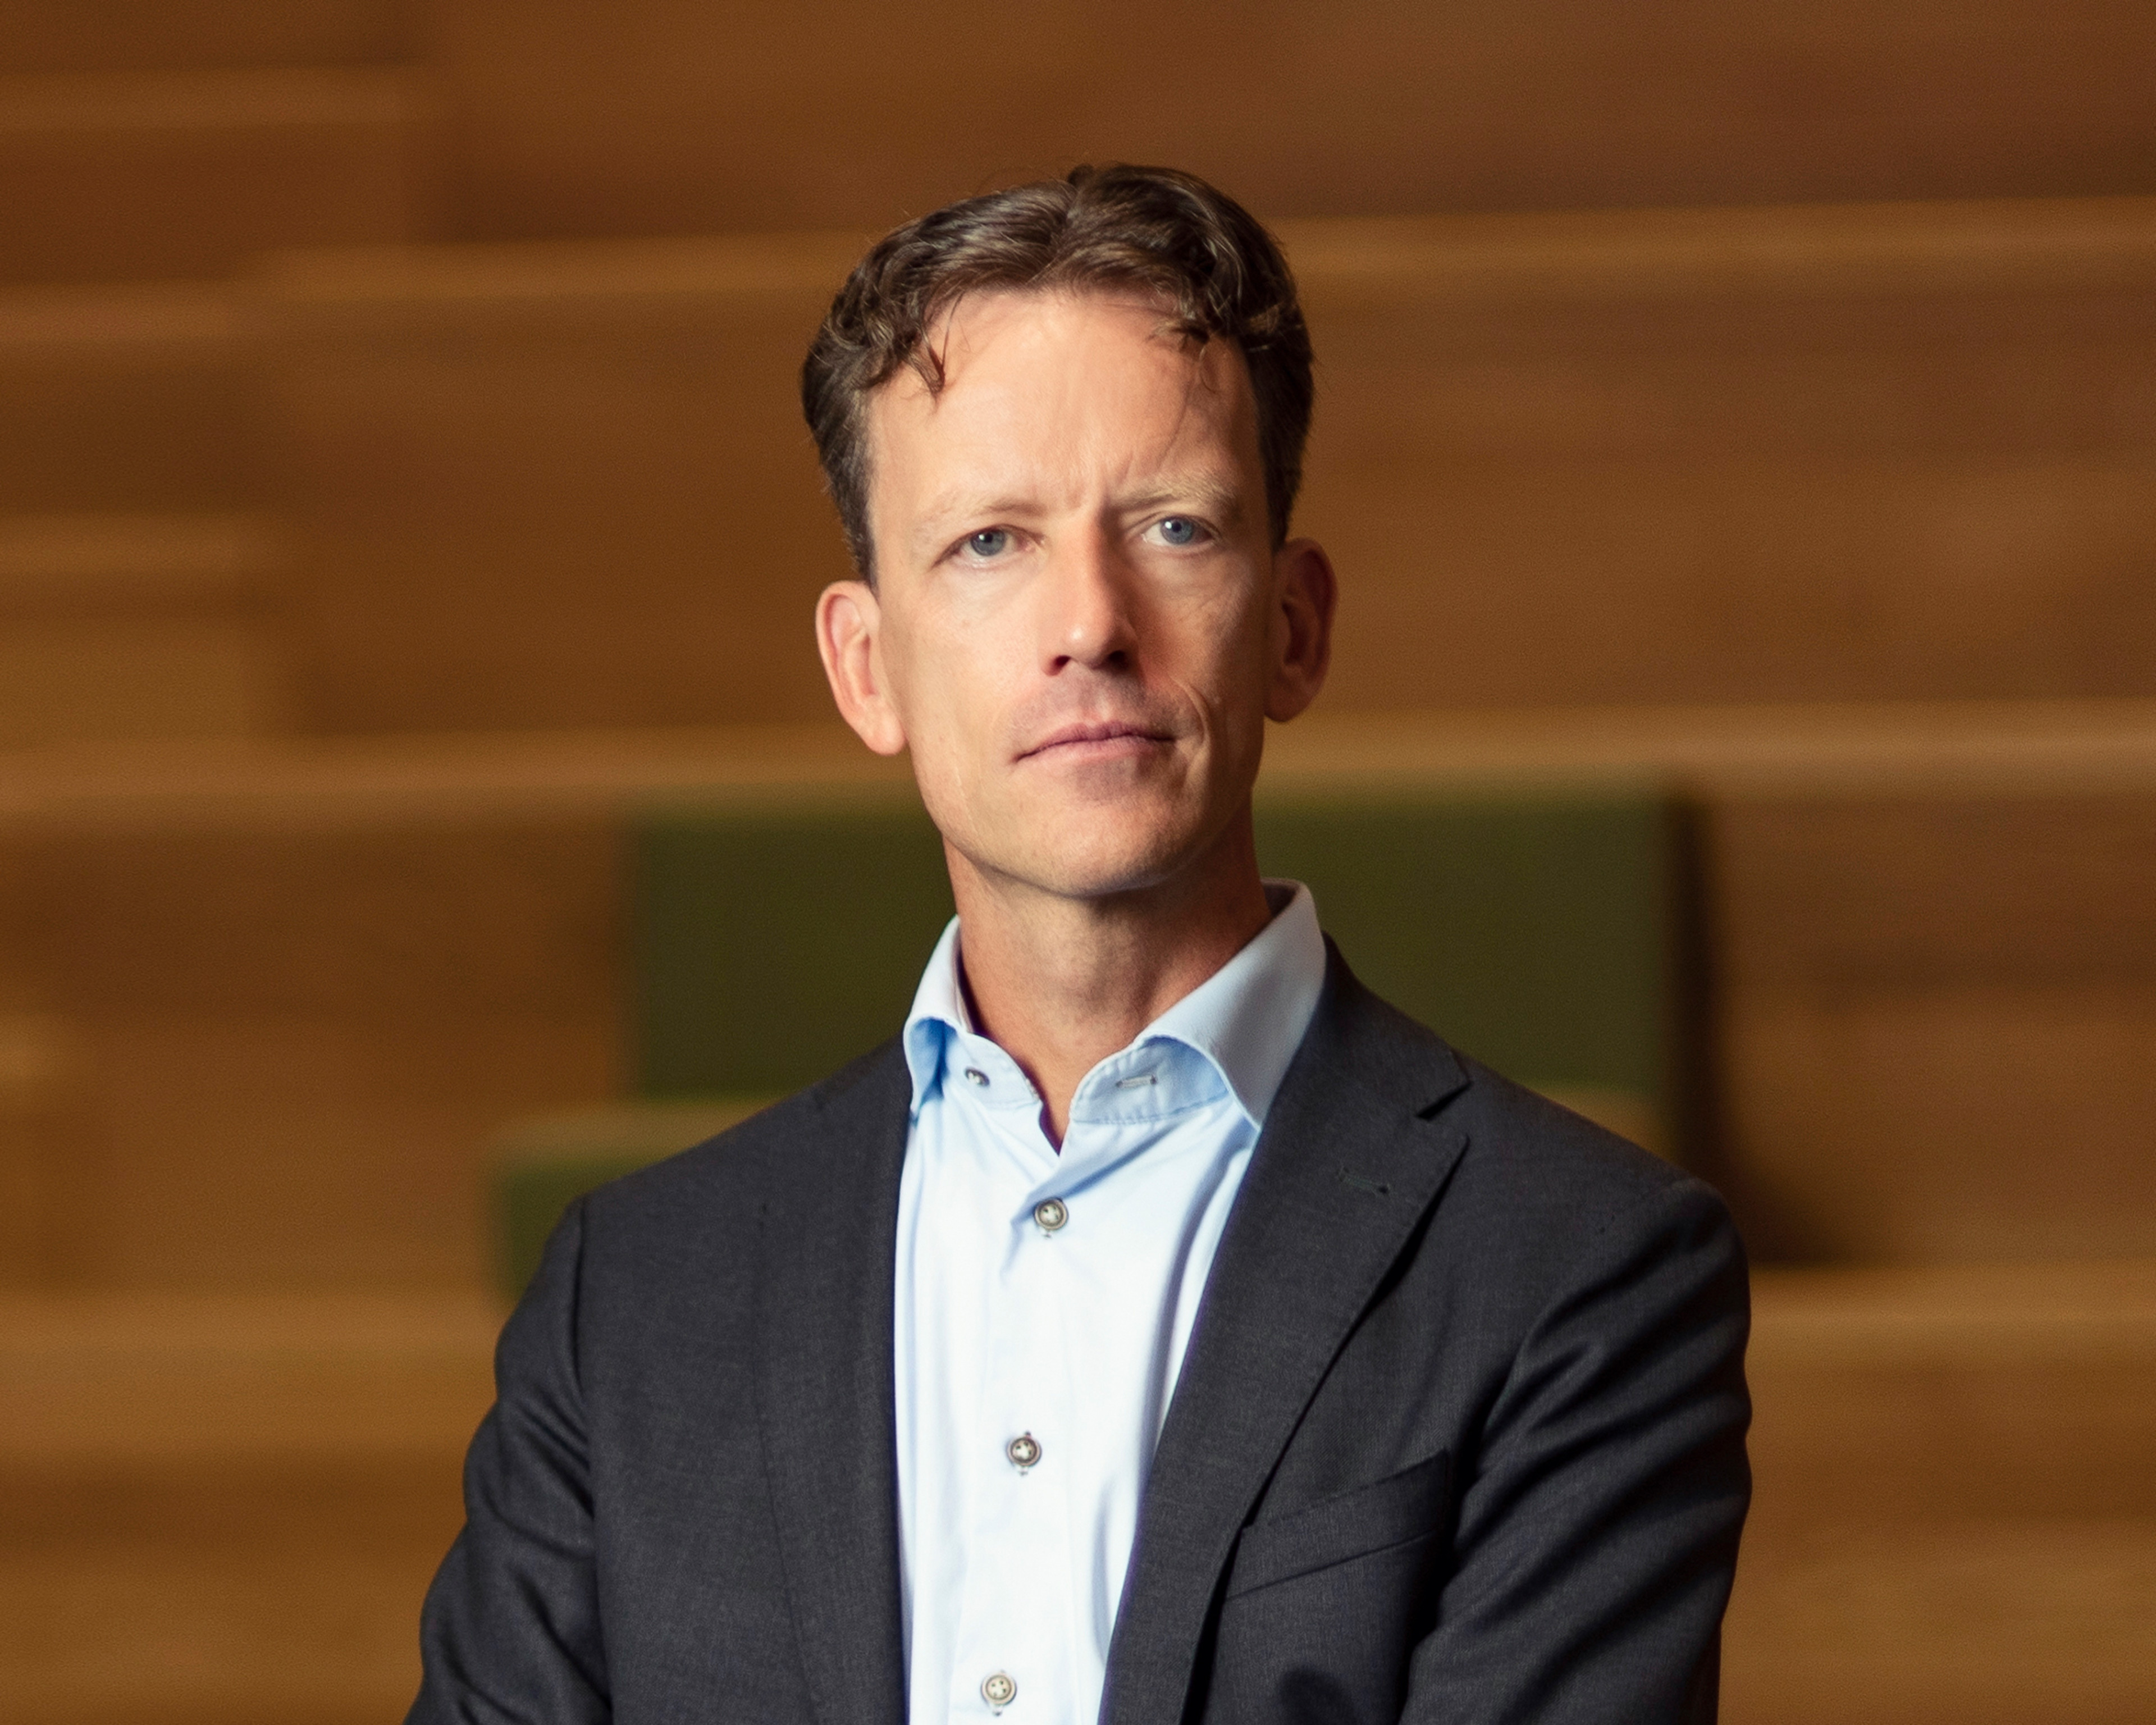
Active management of bond duration can protect against any future rate rises while still generating returns if yields continue to fall, says Robeco’s Olaf Penninga.
Authors

Summary
- First rate rise by the Fed need not be feared
- Active duration management adjusts rate sensitivity
- Quant model uses futures to adjust portfolio
- Investors can still benefit from further yield falls
The prospect of the first US rate rise in almost a decade has caused many government bond investors to believe that they now face declining or negative returns. Bond yields and prices move inversely, which means that if rates do rise, and yields rise in tandem, then bond values would fall.
By focusing on duration, or the amount of time before the bond matures, investors can adjust the interest rate-sensitivity of their holdings, says Penninga, portfolio manager of the Robeco Lux-o-rente government bond fund. Shorter-dated bond values are generally less sensitive to rate rises than longer-dated ones.
Lux-o-rente uses a duration management quantitative model as its sole performance driver. An overlay of liquid interest rate futures is added to an underlying portfolio of global government bonds to steer the duration profile of the portfolio. The model predicts interest rate moves in the three main bond markets; Germany, Japan and the US. The strategy was designed to be able to strongly benefit from falling interest rates and protect against rising interest rates.
Markets reacted positively to a meeting by the US Federal Reserve (Fed) on March 18 at which members of the rate-setting Federal Open Market Committee gave their strongest indication yet that rates would rise this year for the first time since 2006. Crucially, Fed chairwoman Janet Yellen said the US central bank no longer needed to be ‘patient’ about when to start hiking rates, though she stressed that they didn’t need to be ‘impatient’ either.
“Many investors worry about rising yields as the Fed prepares to start hiking rates,” says Penninga. “Yellen has stressed that the removal of “patience” from the Fed’s statement need not imply a rate hike as early as June, but the Fed might very well start raising rates this year.”
“While the Fed will probably not raise rates in a straight line to over 5%, like they did in 2004-2006, a somewhat more modest tightening cycle could potentially also hurt government bond markets. In 1999 the Fed embarked on a series of rate hikes totaling 1.75%. From current levels, that would take the Fed Funds rate just to 2%. However, the anticipation of that tightening pushed US 10-year bond yields up by 1.8% in 1999.”
Many investors worry about rising yields as the Fed prepares to start hiking rates
“In today’s low-yield environment government bond markets are more vulnerable to rising yields,” he says. “Firstly, the relatively low level of yields offers little buffer to cushion price declines of bonds. On top of that, the average duration of government bonds has increased in recent years as countries have issued more long-dated bonds.”
“Therefore, actively controlling interest-rate risk is thus crucial. With its outspoken duration management Robeco Lux-o-rente is well-suited for today’s challenging market environment.”
Get the latest insights
Subscribe to our newsletter for investment updates and expert analysis.
How the fund works
The Lux-o-rente fund achieves this by buying bonds to achieve a portfolio duration that can deviate from the benchmark average of seven years by minus-six years to plus-six years in either direction. In this way, the duration positioning of the fund varies from one to 13 years.
“By reducing duration it can protect against rising yields,” says Penninga. “The duration management is fully based on the outcomes of our proprietary quantitative model, which has demonstrated its market timing ability since the late 1990s. The 1999 rise in bond yields for example was correctly anticipated by the model. This market timing ability is crucial for successful duration management.”
Markets have been afraid of rate hikes before. After the financial crisis in 2008, investors originally expected a Fed rate hike when the worst of the crisis had blown over in late 2009, when nothing happened. “Reducing duration too early would have meant missing out on great bond returns,” says Penninga.
He says the duration model really proved its worth when the Fed conducted its last act of tapering bond purchases in October 2014, and many investors expected rates to start rising. In fact, yields fell further, and US government bonds returned 6% over the six-month period around the decision (31 July 2014 – 31 January 2015).
Actively controlling interest-rate risk is crucial Olaf Penninga
Olaf Penninga
Portfolio Manager
Disciplined quant approach
“Over this period, Robeco Lux-o-rente had overweight duration positions, thus benefiting strongly from the rally in bonds,” says Penninga. “This underlines the advantage of the disciplined implementation of the quantitative model’s signals. The model forecasted lower bond yields for good reasons – like rapidly declining inflation putting pressure on central banks around the world to ease policy further.”
“Nevertheless, not many investors expected government bonds to perform well. Actually, the consensus view instead was that bond yields were so low that bonds were quite unattractive. Our model also takes the valuation of bond markets into account, but it decided that the macro environment called for even lower yields. By ignoring the emotional belief that ‘bond yields cannot go lower’, Robeco Lux-o-rente was able to benefit strongly from the rally in government bond markets.”
One of the advantages of the fund’s quantitative approach is that it allows researchers to back test what happens in different market environments, like the strong rise in bond yields in the 1970s. “The long-dated back test confirms that the model performs as well with rising yields as with falling yields,” says Penninga. “It also reveals that the model has actually performed best when bond yields made bigger moves, whether rates are rising or falling. This is a useful property as this is precisely when one needs active duration management the most.”
Important information
THIS WEBSITE IS SOLELY INTENDED FOR PROFESSIONAL INVESTORS, WHICH HAS THE MEANING ASCRIBED TO IT IN THE SECURITIES AND FUTURES ORDINANCE (CAP. 571 OF THE LAWS OF HONG KONG) AND ITS SUBSIDIARY LEGISLATION. Investment involves risks. Past performance is not indicative of future performance. The information contained in this website is provided for reference only and does not constitute investment advice or an offer or solicitation to buy or sell in any securities or to adopt any investment strategy. Investors should not base their investment decisions solely on the information provided on this website and are advised to seek independent advice (including advice on tax implications) before making any investment decisions. Investors should ensure they fully understand the risks associated with the investment products and should also consider their own investment objectives and risk tolerance level. The investment decision is yours. You should not invest unless the intermediary who sells you the investment products has advised you that it is suitable for you and has explained how it is consistent with your investment objectives. Please refer to the relevant offering documents or other legal documents for further details including the risk factors. This website is published by Robeco Hong Kong Limited which is regulated by the Hong Kong Securities and Futures Commission (“SFC”) (CE No. APU851). This website has not been reviewed by the SFC. No assurance can be given that the investment objective of any investment products will be achieved. No representation or promise as to the performance of any investment products or the return on an investment is made. The value of investments may fluctuate. Past performance, projections, or forecasts included in this website should not be regarded as guarantees or indications of future performance, and no express or implied warranty is provided. The contents of this website are based on sources believed to be reliable, but due to the nature of information delivery technology and the necessity of using multiple data sources, including third party content, their accuracy is not guaranteed. The opinions expressed are as of the date shown above and may change as market conditions evolve, and are subject to change without notice. These opinions may differ from those of other Robeco investment professionals. Robeco accepts no liability for any direct, indirect, or consequential loss arising from the use of this material or any comments, opinions, or estimates contained herein. Robeco has no duty to update this website or any website content. Materials on this website may not be reproduced, distributed, or published without prior written permission from Robeco. Unless otherwise specified, Source: Robeco.