Portfolio Manager
• Insight
El Niño risks and biodiversity investing in a warming world
The strongest El Niño in recent history is set to intensify droughts and floods worldwide, with climate change magnifying its impact and economic costs. Biodiversity serves as a natural buffer against extreme weather by enhancing ecosystem resilience and protecting critical resources. Companies already investing in nature-based solutions and resilient supply chains may be better equipped to navigate the disruptions ahead.
Authors
Sector Lead
Summary
- An imminent El Niño powerfully underscores economic risks of climate change
- Biodiversity acts as a buffer, boosting resilience for communities & companies
- The biodiversity strategy targets companies helping to protect natural capital
The 2026 El Niño is shaping up to be one of the most powerful on record. The National Oceanic and Atmospheric Administration (NOAA) currently assigns a 90% probability that it develops into a Super El Niño between October and December.
El Niño can trigger crop failures, food shortages, supply chain disruptions and inflationary pressures, while extreme weather damages infrastructure, reduces labor productivity, strains water and energy systems, and drives higher insurance losses. The result is a macroeconomic shock with significant implications for inflation, economic growth and corporate earnings. The IMF estimates that a typical El Niño increases global food prices by roughly 5% within a year, although there are regional differences.1 Citi estimates cumulative economic losses of USD 5-7 trillion over five years, equivalent to 4.5-6.4% of global GDP.2
Forests regulate rainfall, wetlands store water during droughts, healthy soils improve water retention, and biodiversity supports pollination and agricultural productivity. As biodiversity declines, these resilience mechanisms weaken and with significant economic consequences.
More than half of global GDP depends directly or indirectly on nature and the World Bank estimates harming it could result in economic losses of USD 2.7 trillion by 2030. That’s annual, not total. Yet the interaction between biodiversity loss, climate volatility and economic growth remains materially underappreciated by capital markets. As Mark J. Spalding, President & CEO of The Ocean Foundation, notes:
Every El Niño is a preview of what a warmer, less biodiverse ocean costs us, in fisheries, coastlines and communities. Biodiversity protection isn't separate from economic resilience; it's the foundation of it
His observation highlights the growing interconnection between biodiversity, climate resilience and economic performance. As natural capital deteriorates, economies become more vulnerable to climate shocks, affecting inflation, resource availability, supply-chain stability, corporate earnings and crucially, political capital.
Figure 1 – El Niño will intensify weather extremes in regions across the globe
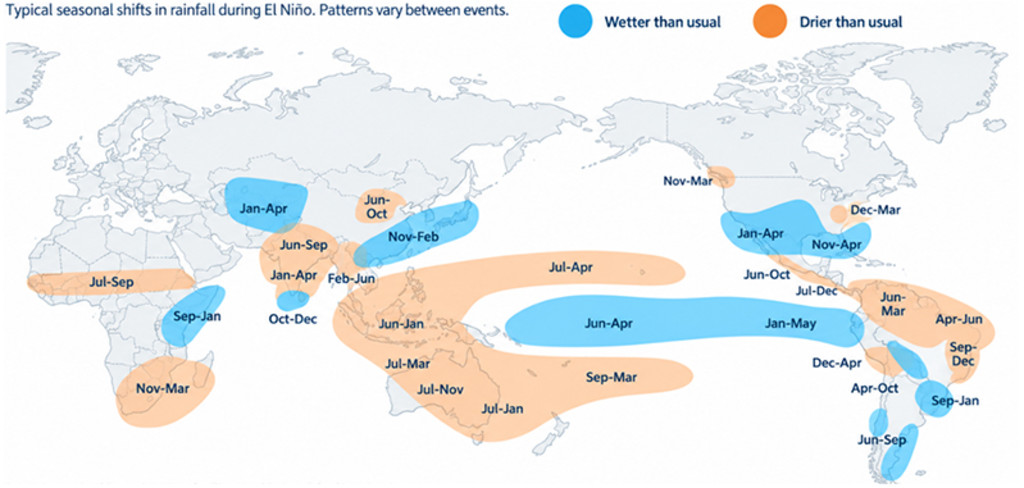
Source: Robeco, Columbia International Research Institute for Climate and Society (accessed 2026).
https://iridl.ldeo.columbia.edu/maproom/IFRC/FIC/elninorain.html
From risk to opportunity
The investment opportunity is not driven exclusively by government policy and corporate sustainability commitments. When climate disruption and biodiversity loss begin to affect harvests, water supplies, commodity prices and the reliability of global supply chains, they reshape the economics of entire industries. That creates demand for businesses that operate with greater resilience and produce with fewer natural-resource inputs.
The benefits of which can include improving water availability and quality, reducing pollution and waste, restoring degraded land, strengthening agricultural yields, or making materials and production processes more efficient. These solutions are increasingly becoming operational necessities rather than discretionary initiatives.
The effects also extend specifically to consumer-facing companies that depend on agricultural commodities, water and other natural-resource inputs. Businesses that improve soil health, protect water sources and secure more sustainable supply chains are better placed to secure essential raw materials, manage volatility in input costs and maintain production during environmental shocks.
For investors, this expands the opportunity from a narrow ‘green spending’ theme into a broader structural shift in how economies produce food, manage resources and build resilience. The World Economic Forum estimates that nature-positive business models could create up to USD 10 trillion in annual opportunities by 2030, including USD 3.6 trillion from sustainable food, land and ocean use.3
Importantly, biodiversity investing is already accessible today. Companies delivering environmental solutions, improving resource efficiency and enabling a more nature-positive economy operate across multiple sectors and collectively represent a multi-trillion-dollar market.
Figure 2 – Biodiversity loss is creating a significant investment opportunity
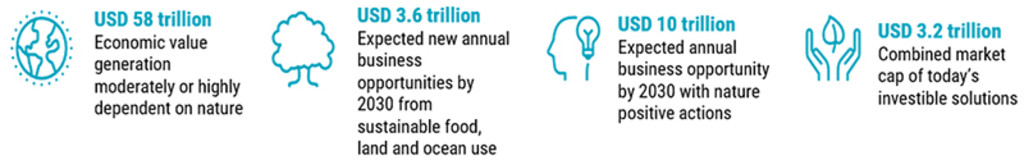
Source: Robeco, PwC 2023, WEF 2020, Citi Research & Global Insights 2021.
Spotlight on biodiversity during COP17
Momentum is building ahead of COP17 in Yerevan, Armenia (19-30 October 2026) where 196 countries will conduct the first formal review of progress against the 2030 Global Biodiversity Framework targets. While approximately 90% of countries have established national biodiversity targets, data, implementation strategies, and funding gaps remain significant challenges.
COP17 is expected to mark the transition from biodiversity target-setting to biodiversity implementation, with a strong focus on financing, accountability and measuring progress against previously agreed targets. It’s time to put meat on the bones of the agreed USD 200 billion per annum spend. Greater policy support, regulatory clarity and financial commitments could further accelerate private-sector investment in biodiversity-related solutions and strengthen the long-term growth outlook for companies exposed to these themes.
Biodiversity Equities D USD
- performance ytd (30-9)
- -0.26%
- Performance 3y (30-9)
- 7.58%
- morningstar (30-9)
- SFDR (30-9)
- Article 9
- Dividend Paying (30-9)
- No
Past performance is no guarantee of future results. The value of the investments may fluctuate. Annualized (for periods longer than one year). Performances are net of fees and based on transaction prices.
A strategy positioned for structural growth
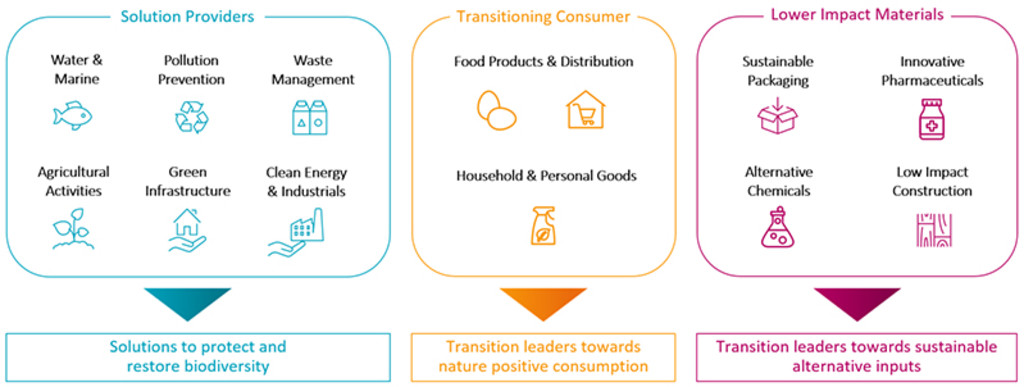
The Robeco Biodiversity Equities strategy focuses on companies that either help solve biodiversity challenges or are helping mititage biodiversity loss. The portfolio is built around three clusters:
Solution providers benefit directly from rising demand for water management, waste treatment, technology enablers and environmental infrastructure.
Transitioning consumer companies are reducing their biodiversity footprint through sustainable and environmentally responsible supply chains.
Lower-impact material providers that enable the transition through sustainable packaging, environmental monitoring tools, alternative chemicals and lower-impact construction materials.
Figure 3 – Robeco’s Biodiversity Equities strategy’s investment universe
Source: Robeco
Together, these segments aim to provide diversified exposure across the biodiversity value chain while maintaining a focus on high-quality companies with durable competitive advantages, strong cash generation and attractive long-term returns. For example, Veolia (a solution provider) is a critical supplier of water treatment and recycling solutions for cities and industries. Sprouts Farmers Market (a transitioning consumer) is a large US supermarket chain offering fresh, natural and organic foods. Finally, Novonesis – of the lower-impact materials group – makes natural, bio-based inputs to replace chemicals in food, agriculture, biofuels and other household products (see Figure 3).4
Beyond stock selection, engagement is intended to serve an important lever for real-world impact. Robeco aims to have 25% of the Biodiversity Equities strategy under enhanced engagement, led by our Active Ownership team. These long-term agreements outline clear milestones which underpin the goal of improving corporate biodiversity performance and strengthening long-term value creation.
Conclusion
El Niño is more than a weather event. Its increasing intensity highlights a fundamental investment reality: climate risk, biodiversity loss and economic outcomes are becoming increasingly interconnected. As ecosystems and natural resources deteriorate, future climate shocks are likely to become more economically costly.
What were once viewed primarily as environmental issues are increasingly emerging as drivers of inflation, supply-chain disruption and earnings volatility. As biodiversity moves from policy ambition to economic reality, companies that strengthen resilience, improve resource efficiency and protect natural capital are likely to be among the long-term winners.
Footnotes
1Allianz Economic Research, El Nino, July 2026.
2 Citi, Global Economic Outlook & Strategy, June 2026.
3World Economic Forum, ‘New Nature Economy Report II: The Future of Nature and Business.’ July 2020.
4The companies/securities shown here are for illustrative purposes only in order to demonstrate the investment strategy on the date stated. The companies/securities are not necessarily held by a strategy/fund nor is future inclusion guaranteed. No inference can be made on the future development of the company. This is not a buy, sell, or hold recommendation.