


Portfolio Manager
• Insight
What 20 years of defensive equities can teach investors
This year marks 20 years of Conservative Equities. What began as a contrarian idea has grown into a significant Robeco strategy with strong long-term track records. Looking ahead, we remain confident about its added value in client portfolios as a useful diversifier and alpha generator.
Authors


Head of Conservative Equities and Chief Quant Strategist
Summary
- Proof: positive alpha since inception across all three flagship Conservative Equity strategies, gross of fees
- Patience: defensive investing can lag for extended periods in strong bull markets
- Potential: a useful portfolio diversifier as market concentration rises
As with every distinctive active equity strategy, this hasn’t always come easily. Especially in strong and long bull markets, investors’ patience can be tested. Twenty years of experience offer a useful perspective on the proof, the patience and the potential of defensive investing.
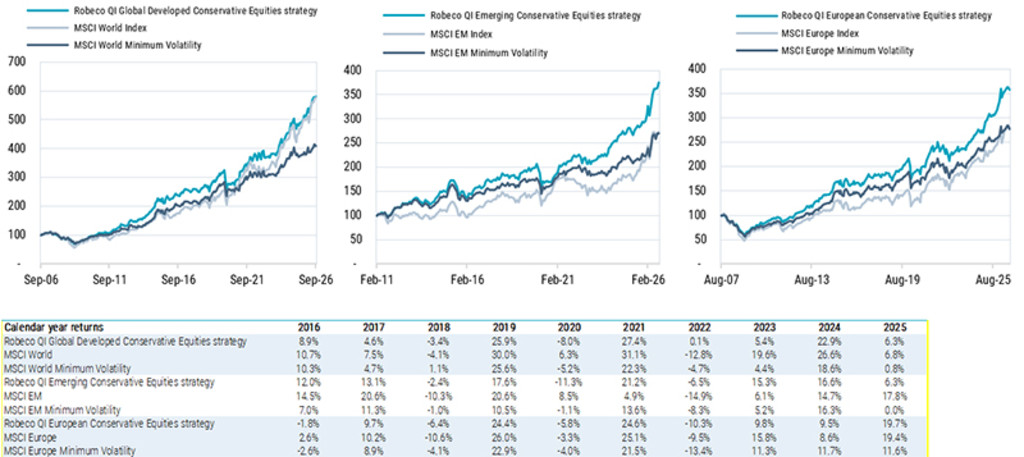
All three flagship Conservative Equities strategies have generated positive alpha1versus the broad market and outperformed minimum-volatility benchmarks since inception, gross of fees. Two forces have driven these results: reducing losses in down markets and including proprietary alpha signals to enhance returns, and the strategies have also added value versus minimum-volatility indices.
Figure 1 - Cumulative returns for three Conservative Equities flagship strategies – 30 September 2026
Past performance is no guarantee of future results. The value of your investments may fluctuate.
Source: Robeco. Figures gross of fees, based on gross asset value, in EUR. If the currency in which the past performance is displayed differs from the currency of the country in which you reside, then you should be aware that due to exchange rate fluctuations the performance shown may increase or decrease if converted into your local currency. Values and returns indicated here are before cost; the performance data does not take account of the commissions and costs incurred on the issue and redemption of units. These have a negative effect on the returns shown. Please refer to the appendix for other important disclosures. Date as of 30 September 2026. Inception dates: Robeco QI Global Developed Conservative Equities strategy – September 2006; Robeco QI Emerging Conservative Equities strategy – February 2011; Robeco QI European Conservative Equities strategy – August 2007. We used the unhedged track records for better comparison, in reality both Robeco QI Global Developed Conservative Equities strategy and the Robeco QI European Conservative Equities strategy were hedged until June 2012.
A broader investment universe, including hundreds of off-benchmark stocks, and fewer constraints allow portfolios to tilt towards proprietary alpha signals. Continuous innovation across Robeco’s quantitative equities platform includes trade-timing signals and distress signals based on machine learning.
The patience
Defensive investing can feel lonely when markets race higher. Over the past decade, global equities have enjoyed a powerful bull market, far outpacing emerging-market and European equities. Twenty years of experience show that lagging in strong bull markets is not necessarily a shortcoming but rather a feature of the strategy.
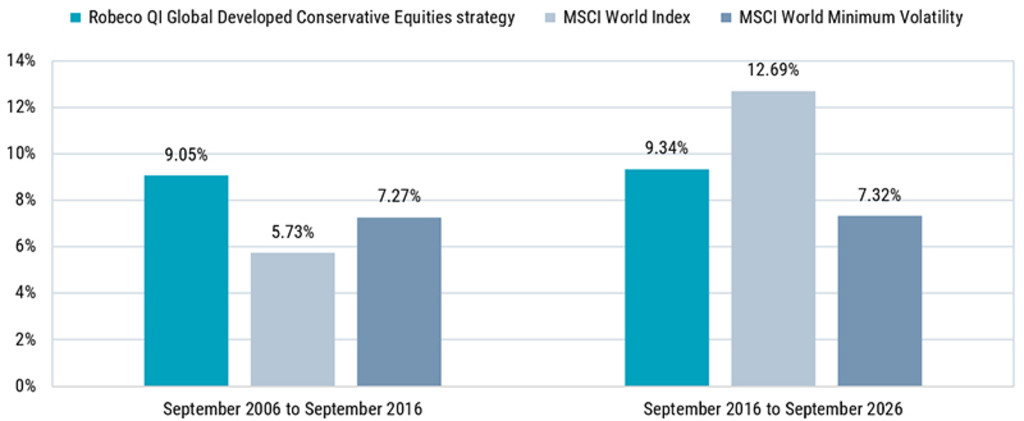
Figure 2 splits the global strategy’s 20-year history into two periods. The first decade favored downside protection; the second brought a long, US tech-led bull market. Annualized returns were strikingly consistent: 9.1% in the first decade and 9.3% in the second, gross of fees. Yet the perception was very different. The strategy outperformed both the market and the minimum-volatility index in the first decade. In the second, it again beat the defensive style index, but lagged the broad market.
Figure 2 | Two decades with similar returns and different perceptions
Past performance is no guarantee of future results. The value of your investments may fluctuate.
Source: Robeco. Figures gross of fees, based on gross asset value, in EUR. If the currency in which the past performance is displayed differs from the currency of the country in which you reside, then you should be aware that due to exchange rate fluctuations the performance shown may increase or decrease if converted into your local currency. Values and returns indicated here are before cost; the performance data does not take account of the commissions and costs incurred on the issue and redemption of units. These have a negative effect on the returns shown. Date as of: 30 September 2026. Based on monthly data in EUR of the gross asset value of the representative account Robeco Institutional Conservative Equity strategies. See table under Figure 1 for ten-year track records.
The exception to “winning by losing less” was 2020, when high-beta technology proved unusually defensive and defensive stocks did not reduce downside risk. Lagging the broad market for a decade is a very long time, even for investors with long-term horizons.
The potential
Strong markets can make portfolio defense seem less urgent, but they may also provide the best opportunity to put it in place. After years of double-digit returns, investors should consider whether the next decade will look anything like the last. Rising index concentration and the dominance of technology stocks increase dependence on a narrow group of market leaders.
Figure 3 | Defensive style out of favor in tech rally: we have been here before
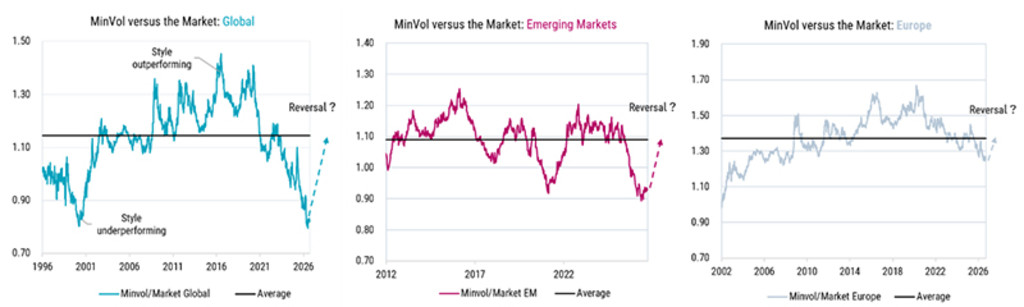
Source: MSCI, Bloomberg, Robeco. Date as of: 30 September 2026. MinVol versus the Market represents the relative cumulative total return ratio of the respective MSCI Minimum Volatility Index divided by the standard broad market MSCI Parent Index (MSCI World, MSCI Emerging Markets, and MSCI Europe). The horizontal line indicates the historical average ratio over the displayed time horizon. Past performance is no guarantee of future results
Investors do not need to predict the next correction or style rotation to recognize the value of stronger diversification. Our defensive equity strategies offer more balanced exposure through single-stock limits and up to 20% in off-benchmark stocks. With a beta of around 0.70, they are less exposed to market swings. Risk is explicitly managed at both stock level, using distress indicators, and portfolio level, through correlations and concentration limits.
Style performance changes over time, and the catalyst is hard to predict. Prolonged defensive underperformance has historically been followed by sharp recoveries. This history does not tell us when leadership will change, but it does show the value of maintaining exposure before a reversal begins.
Looking ahead
Conservative by name does not mean static in practice. The strategies have evolved as data, insights and computing power have improved, while their core philosophy has remained unchanged: avoiding unrewarded risk and seeking attractive upside. For investors seeking to retain meaningful equity exposure while strengthening portfolio resilience, Conservative Equities continues to offer a distinctive approach to defensive investing.
Footnote
1Alpha refers to the excess return of an investment relative to a benchmark index and is a measure of performance.


