Head of Next Gen Research

• Visie
Portfolio construction beyond risk and return
How 3D investing adds an investor-specific third objective
Traditional portfolio construction focuses on risk and return, yet investors often care about much more. In this insight from our Expected Returns 2027-2031 special topic, quant researchers Mike Chen and Iman Honarvar explain how generalized 3D investing can bring an additional investor-specific objective directly into portfolio design, making the resulting trade-offs more explicit.
Auteurs
Deputy Head of Next Gen Research
Topzoekwoorden
Samenvatting
- 3D investing adds an investor-specific objective to the risk-return framework
- Objectives reveal trade-offs that constraints alone may leave hidden
- Additional dimensions must be meaningful, measurable and governable
Traditional portfolio construction is usually framed as a two-dimensional problem: investors seek the highest expected return for a given level of risk, or the lowest risk for a given level of expected return.
Yet in practice, real investors often have additional objectives that matter for economic, regulatory, tax or mission-driven reasons. A pension fund may care about liability matching; an insurance company about capital efficiency; an income-oriented investor about stable cash flows; and a sustainability-focused investor about carbon footprint or alignment with broader goals. These preferences represent additional dimensions of investor utility that are often left implicit in traditional portfolio design.
From sustainability to generalized 3D investing
Chen and Mussalli (2020) argued that ESG investing should not rely solely on exclusions or reporting overlays, but should instead be integrated directly into portfolio construction. The trade-off between financial performance and sustainability should be made explicit rather than managed indirectly through constraints.
This led to the core idea behind 3D investing: the traditional risk-return framework can be extended to incorporate another important investor-relevant objective, namely sustainability. When an investor cares about sustainability as well as the risk-return trade-off, embedding this third objective directly into the portfolio optimization problem explicitly can lead to better outcomes than treating it as an external constraint.
The broader implication, however, goes beyond sustainability. Portfolio construction should reflect the true dimensionality of investor preferences. In its generalized form, 3D investing means jointly optimizing expected return, risk and an additional investor-specific objective. The nature of this third dimension depends on the investor's priorities.
For income-oriented investors, it may relate to dividend yield or stability. For tax-sensitive investors, it may reflect after-tax efficiency, including turnover, realized gains or dividend taxation. For institutional investors, it may be liability alignment; for defensive investors, resilience to severe losses, financial distress or downside risk. It may also reflect implementation preferences such as liquidity or regional exposure. In each case, the framework evaluates what investors gain and give up when emphasizing a particular objective.
Blijf op de hoogte van de nieuwste duurzame inzichten
Meld je aan voor onze nieuwsbrief om de trends binnen duurzaam beleggen te ontdekken.
Objectives are not the same as constraints
A crucial distinction is the difference between objectives and constraints. A constraint defines a boundary: carbon footprint must stay below a certain level, tracking error within a specified range, or a portfolio must avoid certain securities. Constraints impose discipline, satisfy policy requirements and ensure that minimum standards are met.
An objective, by contrast, is something the investor actively values and wants to improve, subject to trade-offs. If income, tax efficiency, sustainability, resilience or liability alignment enters the objective function directly, the portfolio construction process can evaluate the marginal cost and benefit of improving that dimension. This is more informative than simply imposing a rule and optimizing around it.
Hard requirements therefore belong in constraints, while preferences that admit trade-offs often belong in the objective function. An investor may require a minimum income level, for example, but still want to know whether additional income is worth the associated sector exposure, factor tilt or concentration risk. This distinction makes customization less ad hoc: the investment process remains disciplined, but the objective is expanded to reflect the investor's actual preferences.
Illustration: financial distress as the third dimension
Figure 1 shows a hypothetical application using GICS industry groups within the S&P 500 universe from 2005 to 2025. The three dimensions are volatility, debt-to-assets as a proxy for financial distress, and return. The grey surface represents traditional 2D optimization with debt-to-assets constraints. The magenta surface represents 3D optimization, in which all three dimensions are incorporated jointly in the objective function.
Figure 1: Hypothetical application of generalized 3S investing
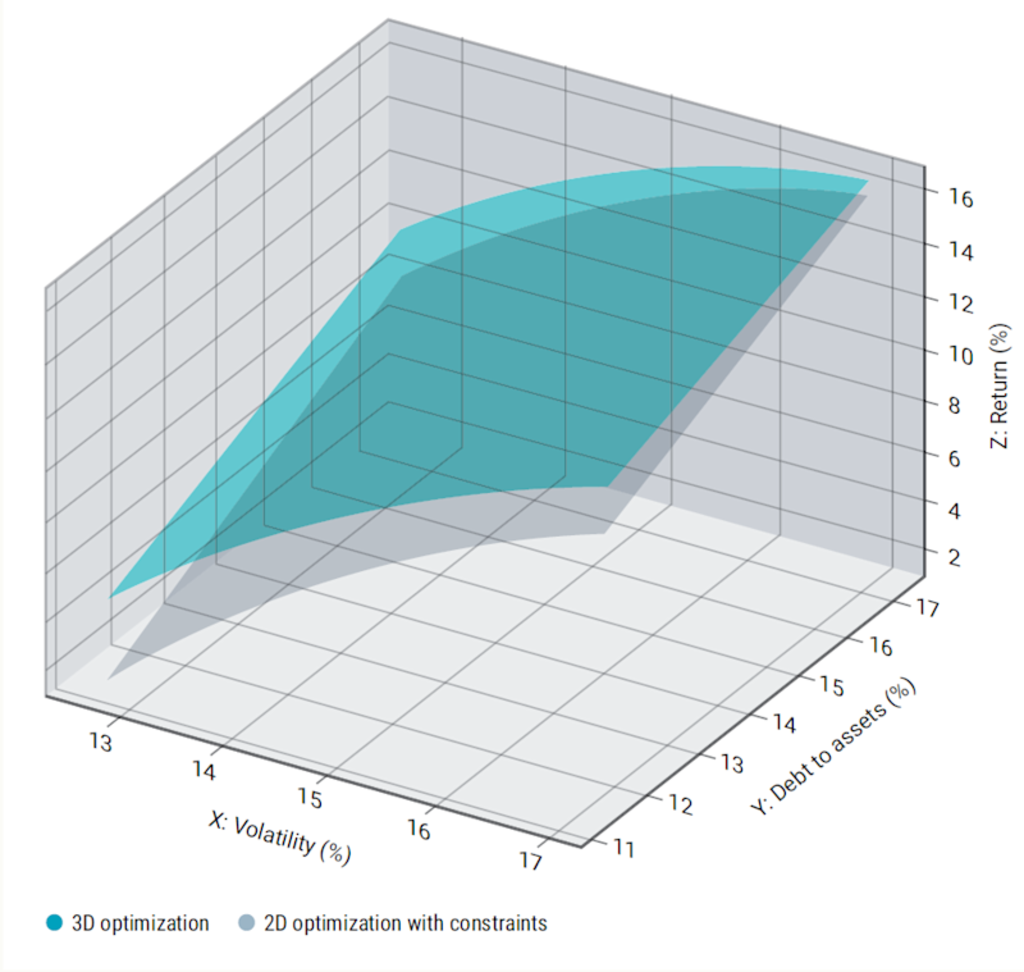
Source: Robeco. The two surfaces display the efficient frontiers under the two scenarios of 2D optimization with constraint and 3D optimization. The underlying assets are the equally weighted industry groups in the S&P 500 index from December 2005 to December 2025.
In this illustrative example, the 3D optimization surface lies above the constrained 2D surface across the relevant range of volatility and debt-to-assets. This indicates that investors can achieve a higher return profile for the same level of volatility and debt-to-assets exposure when the third objective is optimized directly rather than treated solely as a constraint. 3D investing does not eliminate trade-offs, but allows for a more efficient use of them by evaluating return, risk and the investor-specific objective simultaneously.
Flexible, but disciplined
Investor needs are becoming more varied, spanning local markets, tax, income, sustainability, implementation and governance. Generalized 3D investing provides a disciplined architecture for reflecting those priorities, making trade-offs explicit through controlled customization. Every additional objective must be measurable, economically justified and governable.
This article is an excerpt of a special topic in Robeco’s 5-year Expected Returns publication.