Strategist

• Insight
Warsh's wishful thinking
Kevin Warsh has been portrayed as an inflation hawk, but the picture is much more nuanced. His views actually suggest room for lower (not higher) rates, and his goal of shrinking the Fed’s balance sheet may turn out to be more wishful thinking than reality.
Authors

Strategist
Strategist
Top keywords
Summary
- Warsh looks less like a hawk and more like a pragmatic rate-cutter
- Shrinking the Fed’s balance sheet may prove harder than the rhetoric suggests
- The Treasury curve still has steepening potential
During his time as Federal Reserve Governor, Fed Chair-pick Kevin Warsh fretted about the inflationary risks emanating from Quantitative Easing (QE) and emerged as one of its most vocal internal critics. We now know QE primarily as a policy that has boosted the Fed’s balance sheet. Hence, it is of little surprise that in a Wall Street Journal op-ed in November 2025, he argued that “the Fed's bloated balance sheet… can be reduced significantly”. This view has cemented his recent portrayal as an inflation hawk.
However, he has also clarified that “if we would run the printing press a little quieter, we could then have lower interest rates”. Not a pure hawk then. What is more, back in July, he criticized the Fed’s “hesitancy” to cut rates during an interview with CNBC – which hardly sounds hawkish. As for Warsh’s view that the Fed’s balance sheet should decline, this could be perceived by investors as detrimental to the support of the longer-dated segments of the US Treasury market – something the current Treasury Secretary Scott Bessent would surely not cheer.
There’s also another practical difficulty to consider: aggressively shrinking the Fed’s balance sheet could re-ignite tensions in US money markets. A rapid decline in reserves risks pushing the system back toward scarcity, increasing volatility in overnight funding rates and repo markets. Indeed, to prevent this, the Fed has recently decided – after several years of Quantitative Tightening (QT) – to expand its balance sheet again mainly through increased Treasury bill purchases.
In short: we believe that the portrayal of Kevin Warsh as a hawk is overstated and expect that he will support a further reduction in policy rates by June, which would likely be his first meeting as Chair. Regarding his view that the Fed’s balance sheet may be excessively large, we believe it will be difficult in practice to shrink it meaningfully without regulatory adjustments to the ample-reserves regime in the banking system.
A plausible outcome is that the balance sheet – currently around 20% of GDP (see chart below) – expands more slowly than the US economy in the coming years, and/or that Warsh advocates for a faster shortening of the average maturity of the Fed’s bond portfolio. This should make our preference for the 2 to 5 year segment of the Treasury curve relative to 10 year maturities far from wishful thinking, and instead a logical outcome of a Fed that, under Warsh, is likely to favor pragmatism over ideology.
Federal Reserve assets, as % of GDP
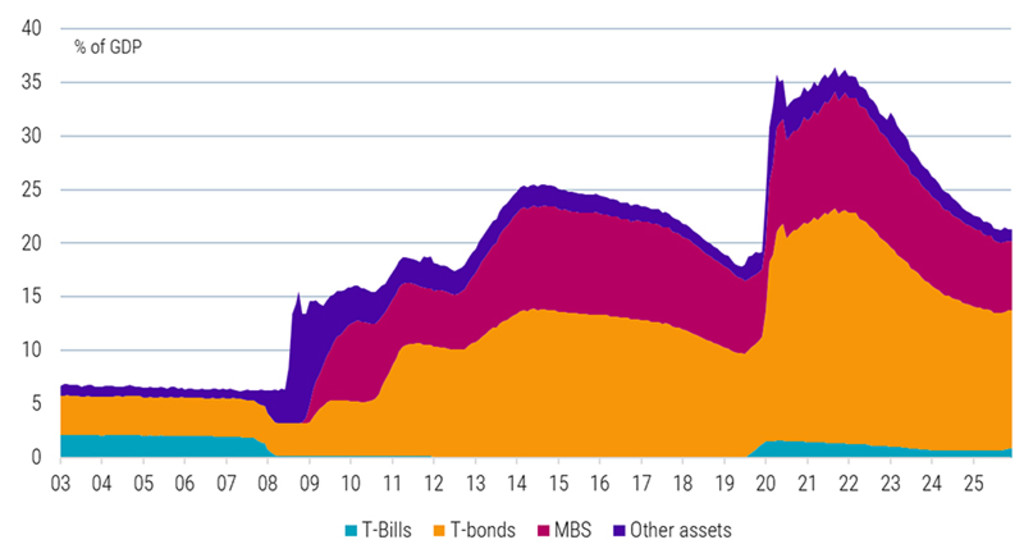
Source: Bloomberg, Robeco, 6 February 2025
Get the latest insights
Subscribe to our newsletter for investment updates and expert analysis.
Important information
THIS WEBSITE IS SOLELY INTENDED FOR PROFESSIONAL INVESTORS, WHICH HAS THE MEANING ASCRIBED TO IT IN THE SECURITIES AND FUTURES ORDINANCE (CAP. 571 OF THE LAWS OF HONG KONG) AND ITS SUBSIDIARY LEGISLATION. Investment involves risks. Past performance is not indicative of future performance. The information contained in this website is provided for reference only and does not constitute investment advice or an offer or solicitation to buy or sell in any securities or to adopt any investment strategy. Investors should not base their investment decisions solely on the information provided on this website and are advised to seek independent advice (including advice on tax implications) before making any investment decisions. Investors should ensure they fully understand the risks associated with the investment products and should also consider their own investment objectives and risk tolerance level. The investment decision is yours. You should not invest unless the intermediary who sells you the investment products has advised you that it is suitable for you and has explained how it is consistent with your investment objectives. Please refer to the relevant offering documents or other legal documents for further details including the risk factors. This website is published by Robeco Hong Kong Limited which is regulated by the Hong Kong Securities and Futures Commission (“SFC”) (CE No. APU851). This website has not been reviewed by the SFC. No assurance can be given that the investment objective of any investment products will be achieved. No representation or promise as to the performance of any investment products or the return on an investment is made. The value of investments may fluctuate. Past performance, projections, or forecasts included in this website should not be regarded as guarantees or indications of future performance, and no express or implied warranty is provided. The contents of this website are based on sources believed to be reliable, but due to the nature of information delivery technology and the necessity of using multiple data sources, including third party content, their accuracy is not guaranteed. The opinions expressed are as of the date shown above and may change as market conditions evolve, and are subject to change without notice. These opinions may differ from those of other Robeco investment professionals. Robeco accepts no liability for any direct, indirect, or consequential loss arising from the use of this material or any comments, opinions, or estimates contained herein. Robeco has no duty to update this website or any website content. Materials on this website may not be reproduced, distributed, or published without prior written permission from Robeco. Unless otherwise specified, Source: Robeco.