Portfolio Manager


• Insight
Sustainable investing: Don’t sign the divorce papers just yet
In light of the ongoing debate over ESG investing we analyzed a core global strategy to see how much performance could be attributed to ESG factors in the previous six years.
Authors


Top keywords
Summary
- Between 2017-2022 our research showed 22% of excess returns can be attributed to ESG
- Unsurprisingly 2022 bucked the trend and provided headwinds
- Sustainable investing is very much alive; a fall-out doesn’t mean an imminent divorce
From time to time even best friends can experience a fallout. For years it seemed the stock market and ESG tailwinds were a great match, with little to worry about. Then 2022 happened: war, an energy crisis, rampant inflation – we’ve all seen the headlines. For sustainable investment strategies, in particular, all these events proved to be a perfect storm.
2022 turned out to be the year where former ESG darlings struggled, whilst ESG ‘baddies’ such as defense companies, fossil fuels, and even tobacco, thrived. In other words, sustainable strategies got a reality check. It also reinvigorated the discussion over what “ESG” actually brings to the table return-wise, something we again explore here with reference to our core global equity strategy, Sustainable Global Stars Equities. In doing so, we’ve analysed the impact of ESG on our investment performance over the years, concluding the following:
Tracking the data since 2017, ESG integration and specific sector exclusions had a positive contribution to investment performance, despite 2022 being an ‘annus horribilis’.
2022 marked the first year though where all ‘sin sector’ exclusions detracted from performance.
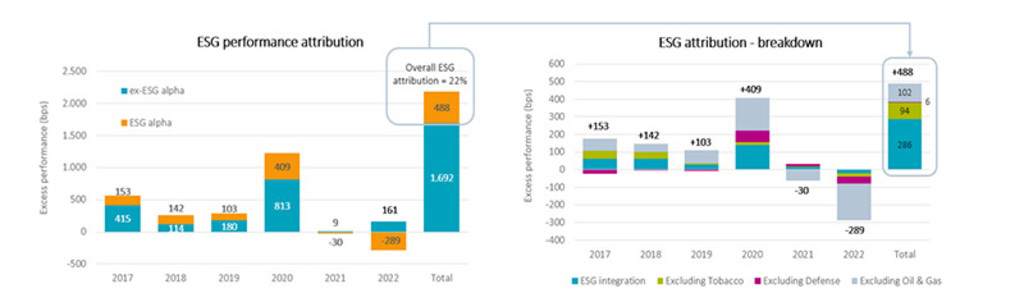
Between 2017-2022, around 22% of the strategy's excess returns can be attributed to ESG1
Put differently, of the annualized 334 basis points (bps) excess performance achieved over this time period, about 75 bps can be attributed to material ESG factors.
Sustainable investing is essentially about broad value creation, investing in companies that do business with respect for all stakeholders. In practice, we do not only look at financial sustainability, but we are integrating the concept more broadly and consider environmental and societal value creation too. Technically, this way of sustainable or ESG investing is called “ESG integration”, whereby material ESG factors form an additional lens in the decision-making process. Note that ESG is not a political ideology but a key step in our investment process.
To that end, within the Sustainable Global Stars Equities strategy, we invest in quality businesses that have strong sustainability strategies that can really impact a company’s business model, potentially creating value over the longer term. At the same time, we might also want exposure to so-called ESG improvers, or even ESG laggards, where upside potential can be quite meaningful if challenges are properly addressed. The benefit of such a barbell approach is that it enables us to invest in different segments of the market, making the portfolio more robust across different market cycles.
The 6-year track record
Even though we’ve incorporated ESG into our decision-making since inception of the strategy, we started explicitly measuring the ESG attribution to investment performance in 2017. Hence, we now have a six-year track record for our analysis (2017-2022), which is illustrated in Figure 1. The left chart of Figure 1 illustrates the strategy's overall excess performance split by ex-ESG and ESG alpha contribution. For example, in 2020, excess performance totalled 1,222 bps of which 409 bps could be attributed to the aforementioned way of ESG integration plus ESG exclusions. The figures also indicate that the ESG attribution to excess performance from 2017-2022 has been significant: ESG explains about 22%, or 75 bps, of the annualized 334 bps of excess performance.
Figure 1: ESG attribution to investment performance
Source: FactSet data
As we’ve argued previously, we believe sustainable investing is very much alive, despite the 2022 reset. A fall-out doesn’t mean an immediate divorce. There is a clear need though to move to the next level, finding the right balance between idealism and realism in the practical implementation of ESG considerations in investment portfolios. In renewing the ESG wedding vows, a forward-looking approach, ESG financial materiality, enhanced engagements in combination with thoughtful exclusions are critical; this should not only be a thought process at the asset manager level, but also among asset owners and regulators.
At Robeco Fundamental Equities, we go beyond nice-sounding ESG narratives and try to measure the actual impact ESG has on investment performance. As demonstrated, our way of consistently integrating and tracking ESG in our decision-making, allows for a good proxy of the importance of ESG in our investment portfolios.
Download the complete paper for a deep-dive into our methodology, results, and a case study illustrating how ESG factors influence investment performance for a specific company in our universe.
Footnote
1Sustainable Global Stars uses the MSCI World EUR Index as a reference index.
Important information
THIS WEBSITE IS SOLELY INTENDED FOR PROFESSIONAL INVESTORS, WHICH HAS THE MEANING ASCRIBED TO IT IN THE SECURITIES AND FUTURES ORDINANCE (CAP. 571 OF THE LAWS OF HONG KONG) AND ITS SUBSIDIARY LEGISLATION. Investment involves risks. Past performance is not indicative of future performance. The information contained in this website is provided for reference only and does not constitute investment advice or an offer or solicitation to buy or sell in any securities or to adopt any investment strategy. Investors should not base their investment decisions solely on the information provided on this website and are advised to seek independent advice (including advice on tax implications) before making any investment decisions. Investors should ensure they fully understand the risks associated with the investment products and should also consider their own investment objectives and risk tolerance level. The investment decision is yours. You should not invest unless the intermediary who sells you the investment products has advised you that it is suitable for you and has explained how it is consistent with your investment objectives. Please refer to the relevant offering documents or other legal documents for further details including the risk factors. This website is published by Robeco Hong Kong Limited which is regulated by the Hong Kong Securities and Futures Commission (“SFC”) (CE No. APU851). This website has not been reviewed by the SFC. No assurance can be given that the investment objective of any investment products will be achieved. No representation or promise as to the performance of any investment products or the return on an investment is made. The value of investments may fluctuate. Past performance, projections, or forecasts included in this website should not be regarded as guarantees or indications of future performance, and no express or implied warranty is provided. The contents of this website are based on sources believed to be reliable, but due to the nature of information delivery technology and the necessity of using multiple data sources, including third party content, their accuracy is not guaranteed. The opinions expressed are as of the date shown above and may change as market conditions evolve, and are subject to change without notice. These opinions may differ from those of other Robeco investment professionals. Robeco accepts no liability for any direct, indirect, or consequential loss arising from the use of this material or any comments, opinions, or estimates contained herein. Robeco has no duty to update this website or any website content. Materials on this website may not be reproduced, distributed, or published without prior written permission from Robeco. Unless otherwise specified, Source: Robeco.