Client Portfolio Manager High Yield

• Insight
Private credit: Opportunity, risk and selectivity in a maturing market
Private credit has become a major source of corporate finance, but risks are emerging in some fast-growing segments. Do these threaten the wider asset class or strengthen the case for selectivity? In this extract from a special topic in our 5-year Expected Returns publication, Client Portfolio Manager Maurice Meijers examines what this means for investors.
Authors
Top keywords
Summary
- Europe’s lower mid-market offers attractive opportunities
- Software lending highlights where risks are building
- Selectivity and disciplined underwriting are increasingly critical
Private credit has evolved from a niche segment of alternative finance into a major component of corporate lending markets. Although private debt existed well before the global financial crisis, the post-GFC retrenchment of banks from parts of the lending market created a powerful catalyst for growth. What was once a more specialized source of financing for mid-sized companies has since expanded into a multi-trillion-dollar asset class, attracting significant institutional capital and increasing regulatory attention.
As the asset class matures, investors face a more nuanced landscape. While private credit continues to benefit from powerful structural tailwinds (see Figure 1), pockets of risk have emerged in some of its fastest-growing segments. Distinguishing between structural strengths and concentrated risks is therefore increasingly important.
Figure 1: The amount of capital being invested into private credit transactions each year continues to accelerate
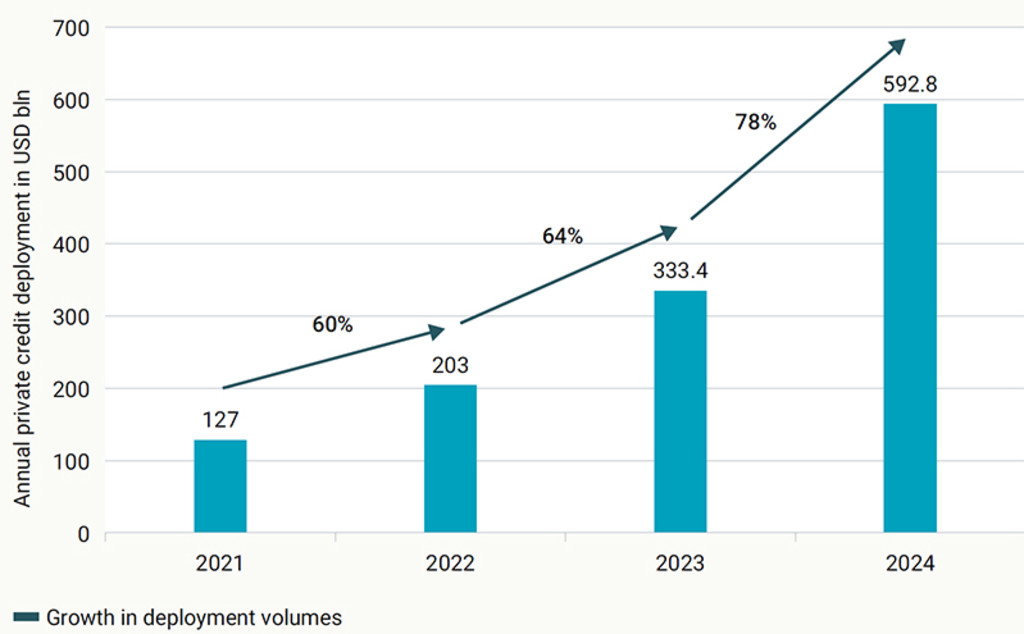
Source: ACC/AIMA, Financing the Economy 2025.
Private credit takes a different approach. Rather than being broadly syndicated or traded in public markets, loans are negotiated directly between borrowers and a limited group of lenders. There is no public market, no price discovery and often no external credit rating. With a bespoke pricing model, terms are tailored to the specific borrower and the lender typically maintains a direct relationship with the borrower throughout the life of the investment. This brings advantages and disadvantages, such as greater information access, stronger covenant protection and customized financing solutions, but it also comes with trade-offs, including illiquidity, reduced transparency and less frequent valuation (see Figure 2).
Figure 2: The broad universe of leveraged finance
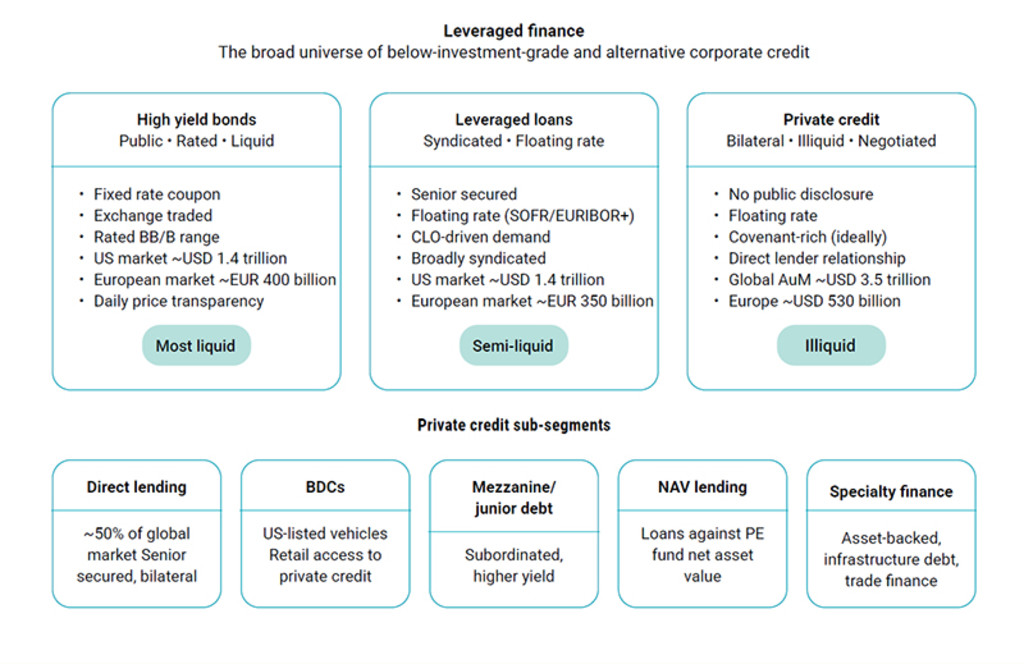
Source: Robeco, Preqin, Bloomberg, ICE Data Services, May 2026
The European opportunity
Following the global financial crisis, successive rounds of Basel capital requirements made it increasingly costly for banks to hold leveraged loans on their balance sheets. As traditional lenders retrenched, private capital stepped in to fill the financing gap.
This shift has created a particularly compelling opportunity in Europe. Banks remain the dominant providers of corporate credit, while non-bank lenders still account for a relatively small share of the market. Private credit is therefore earlier in its development, leaving many borrowers with limited financing alternatives outside the banking system. This is particularly evident in the lower mid-market,1 where SMEs and family-owned businesses have traditionally relied on relationship-based bank lending.
For lenders, these borrowers often offer a different risk profile from private equity-backed companies. Leverage is typically lower, relationships tend to be longer-term and covenant protections are often stronger. Because these companies sit below the radar of the largest direct lending platforms, competition can also be less intense, creating a potentially more attractive balance between risk and return.
What’s new in credits?
Stay ahead with our newsletter on the latest in credit investing.
Where risk is building
Recent developments in software lending illustrate where risks are building within private credit. Software companies – particularly SaaS businesses with recurring subscription revenues – became one of the most popular borrower groups for private credit lenders over the past decade. Predictable recurring revenues, high margins and low capital intensity made them appear ideal credit candidates.
That thesis is now being tested. Outstanding loans to SaaS firms grew from less than USD 8 billion in 2015 to more than USD 500 billion by the end of 2025, representing roughly a fifth of total direct lending exposure.2 As generative AI challenges aspects of traditional software business models, investors have begun reassessing growth assumptions and valuations across the sector.
What appears to be a technology story may ultimately prove to be a credit underwriting story Maurice Meijers
Maurice Meijers
Client Portfolio Manager High Yield
The concern is not just weaker revenue growth. Many loans were sized against enterprise values that were themselves based on revenue multiples. If AI disrupts the revenue outlook, the collateral base and repayment capacity can deteriorate at the same time. In that context, loans originated under assumptions that may no longer hold become more vulnerable, particularly where covenant protections weakened as competition among lenders intensified. What appears to be a technology story may ultimately prove to be a credit underwriting story.
A further complication is valuation. Because private loans are not publicly traded and borrowers disclose limited information, deterioration in credit quality may remain largely invisible until a covenant breach, missed payment or refinancing challenge forces recognition. By that point, lenders often have fewer options available.
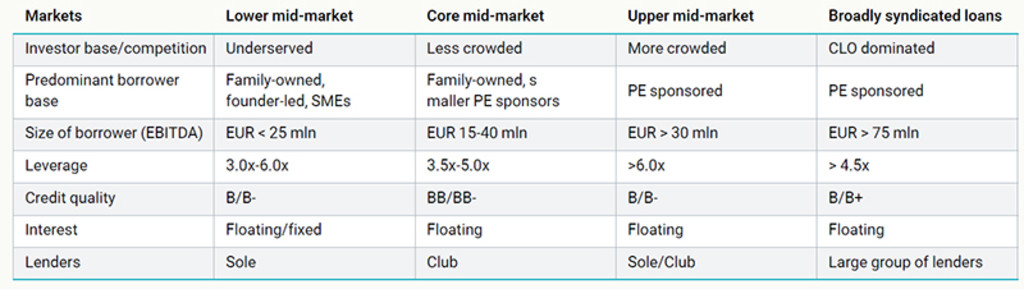
Table 1: Not all private credit is the same
Source: Robeco, June 2026.
Why this is not 2008
At this point, a reasonable question is whether stress in private credit could trigger a crisis similar to 2008. The answer is almost certainly no. While losses are likely to emerge in some parts of the market, the structure of private credit is fundamentally different from that of the banking system that sat at the center of the Global Financial Crisis.
Banks transformed short-term deposits into long-term loans and were deeply interconnected through the financial system. Private credit funds, by contrast, are typically closed-end vehicles funded predominantly by institutional investors who knowingly accept illiquidity in exchange for higher expected returns. When losses occur, they are absorbed by pension funds, insurers, sovereign wealth funds and endowments rather than transmitted through retail depositors or the banking system.
Importantly, private lenders often have tools available that public market investors do not. Direct relationships with borrowers, stronger documentation and the ability to negotiate bilateral solutions can provide flexibility when a company encounters difficulties. Amend-and-extend agreements, payment deferrals and debt restructurings can all help preserve value while avoiding forced asset sales.
This is where manager selection becomes critical. The key question is not whether some loans will be impaired, but whether the lender has the underwriting discipline, documentation rights and borrower relationships needed to manage through periods of stress and maximize recoveries.
Looking ahead: The five-year outlook
For investors with a five-year horizon, the key question is where within the asset class opportunities remain most attractive. The lower mid-market, non-sponsored lending and less sought-after areas of sponsored lending may offer a more favorable balance of risk and return. This is where Robeco focuses its lending activities, often alongside relationship banks with long-standing borrower knowledge. The emphasis is on capital preservation, covenant protection and conservative underwriting rather than maximizing leverage or yield.
As private credit matures, the opportunity is likely to shift from simply gaining exposure to the asset class toward identifying the segments where lender discipline, structural protections and borrower quality remain firmly aligned.
References:
Alternative Credit Council (ACC), & Houlihan Lokey. (2025). Financing the Economy 2025. Alternative Investment Management Association (AIMA). https://www.aima.org/static/e18bf558-90f4-4551-9d3fc002b498afc4/b0234dc6-4f8e-4f82-96fdd5dccae2a382/Financing-the-Economy-2025.pdf
Doerr, S., Eren, E., Krohn, I., & Todorov, K. (2026, March 16). Private credit's software lending meets AI disruption. BIS Quarterly Review. Bank for International Settlements. https://www.bis.org/publ/qtrpdf/r_qt2603v.htm
This article is an excerpt of a special topic in Robeco’s 5-year Expected Returns publication.
Footnotes
1 Typically refers to companies with EBITDA below EUR 50 million.
2 Doerr et al. (2026).