Head of Multi Asset & Equity Solutions, Co-Head Investment Solutions
• Monthly outlook
Why equities can still thrive as bond yields rise
Rising government bond yields have led some investors to question whether they should still be taking risks in equities – but corporate earnings are still a superpower for stocks, says multi-asset investor Colin Graham.
Authors
Summary
- US AAA-rated benchmark Treasuries now offer a yield above 5%
- Equities can still march on due to strong underlying corporate earnings
- Comparisons with 2022 do not apply so long as inflation remains contained
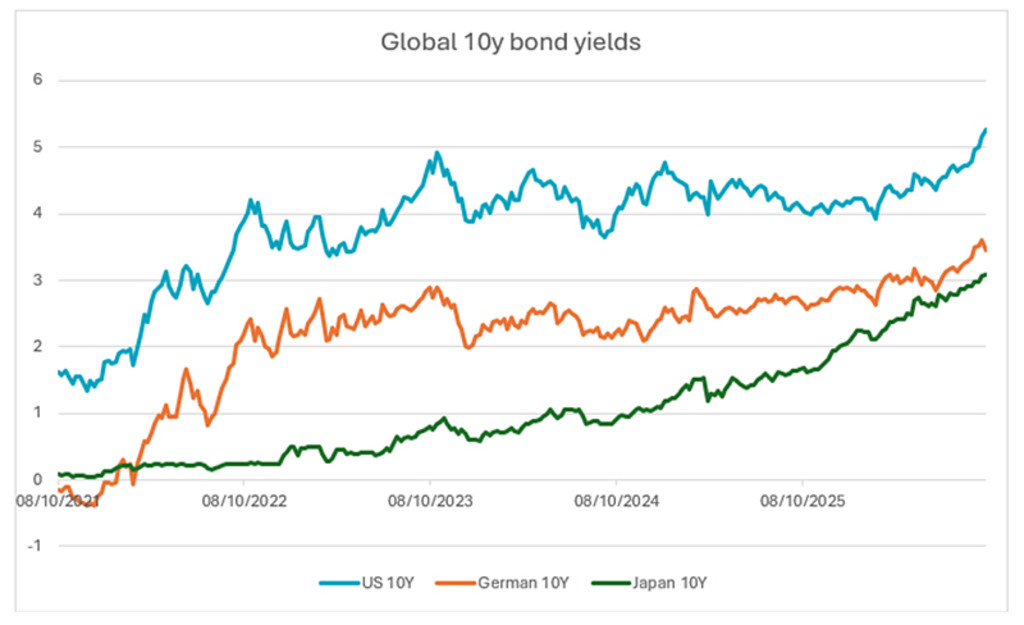
Yields in major sovereign markets such as the US and France have risen as high as 5.26%,1their most generous returns since bonds were spooked by rampant inflation following the post-Covid spending boom in 2022, and Russia’s invasion of Ukraine.
With yields that high from AAA-rated government debt, it begs the question of why investors should risk losing capital in stock markets which are seen as being at highs, fueled by an AI boom that may be unsustainable. Not so, says Graham, Head of Multi-Asset at Robeco.
“For years, investors enjoyed an easy tune – bonds offered paltry returns, leaving stocks as the only game in town, in the famous TINA mindset: ‘There Is No Alternative’. But lately, a new, seductive melody has echoed from the bond market.”
Why risk your hard-earned money in the stock market when you can get a guaranteed 5% risk-free?
“With 10-year Treasury yields hovering around a striking 5.26%, safe government bonds are whispering to investors: ‘Why risk your hard-earned money in the stock market when you can get a guaranteed 5% risk-free?’”
“This is the classic ‘Siren call’ of higher bond yields. In Greek mythology, sailors lashed themselves to masts to resist the fatal call of the Sirens, creatures with the head of a woman and the body of a bird who use enchanting music to lure seafarers to a watery grave. Today, investors are left wondering: Can our stock portfolios sail safely past this temptation, or are we heading for the rocks?”
Figure 1: How bond yields have risen in the US, Germany and Japan
Past performance is no guarantee of future results. The value of your investments may fluctuate.
Source: Robeco, Bloomberg, October 2026.
It’s different from 2022
The reality is different though, thanks to strong corporate earnings that lie behind the continuing stock market rally, and no repeat of the inflation expectations that derailed the bond market in 2022, Graham says.
“A 5% yield certainly isn't a Siren call death sentence for the stock market,” he says. “When bond yields spike, Wall Street’s traditional playbook says that stocks must crash. Higher yields mean higher borrowing costs and a higher discount rate on future profits, which mathematically shrinks stock valuations.”
“However, advanced modeling such as discounted cash flow analysis reveals a fascinating plot twist: a 100-basis-point (one full percentage point) rise in borrowing costs does surprisingly little direct damage to most major stock markets, though it can have a dramatic effect on small-cap indices. It took 200 bps of rate rises to create the environment of the 1987 crash when stocks dropped by 25%.”
“The real danger isn't just the math of debt; it's competition for capital. If safe AAA-rated bonds pay 5% to 6%, investors demand a higher equity risk premium to justify holding volatile stocks. If that required return creeps up even a little bit, it can compress stock price multiples – unless corporate earnings grow fast enough to foot the bill. Most investors will agree that 100 bps rise in bond yields does little to close the gap with earnings growth.”
Global Bonds DH USD
- performance ytd (30-9)
- -3.11%
- Performance 3y (30-9)
- 3.19%
- morningstar (30-9)
- SFDR (30-9)
- Article 8
- Dividend Paying (30-9)
- No
Past performance is no guarantee of future results. The value of the investments may fluctuate. Annualized (for periods longer than one year). Performances are net of fees and based on transaction prices.
Inflation is structurally different
Graham says it is also important to distinguish between what happened the last time yields spiked in 2022, and the market’s dynamics today.
“If the 2022 inflation shock still gives you nightmares, take a deep breath,” he says. “We emphasize that today’s inflation is structurally very different from 2022.”
“Firstly, the demand shock is gone: the wild, post-Covid spending spree and massive fiscal stimulus that fueled 2022's inflation scare have faded. Today’s inflation is primarily driven by supply pressures, such as the Middle East conflict, not runaway consumer demand.”
This can be seen in recent figures for both wage and price inflation. The Atlanta Fed Wage Growth Tracker has fallen to 4.1% in August 2026 compared with 6.7% four years earlier, while the core Consumer Price Index (excluding more volatile food and energy) was 2.4% – its lowest level since the pandemic. Headline inflation is higher at 3.4% due to higher energy costs.
The superpower saving equities
Meanwhile the superpower that enables stocks to stay afloat, and remain attractive despite the lure of higher yields, is simple – corporate earnings are putting up “epic numbers”, Graham says.
“Historically, a massive surge in bond yields came alongside sluggish corporate performance,” he says. “Today, however, US trailing earnings are growing at a robust 28% year-on-year. In short, the sheer horsepower of corporate earnings is overwhelming the gravity of higher discount rates.”
Robeco’s recent Expected Returns five-year outlook predicts that developed and emerging market equities will continue to deliver the highest returns in the coming years.2 Developed market stocks are seen returning 7.0% a year in annualized terms in euros, significantly outpacing the 3.25% that domestic government bonds are predicted to deliver, despite the recent spike.
The Sirens’ sea may be choppier
Graham says it means equities can keep marching higher, so long as inflation expectations don’t shoot up, which means wage pressures need to remain well-contained, and earnings growth needs to outpace the rising cost of capital.
“In all, the sea may be a bit choppier with 5% bond yields on the map, and there is room in a high-growth risk profile to increase bond allocation. However, with strong corporate earnings driving the ship, for now equities still have a clear path forward.”
Footnotes
1 Past performance is no guarantee of future results. The value of your investments may fluctuate.
2 Expected performance is no guarantee of future results. The value of your investments may fluctuate. The scenarios presented are an estimate of future performance based on evidence from the past on how the value of this investment varies, and/or current market conditions and are not an exact indicator. What you will get will vary depending on how the market performs and how long you keep the investment/product.
Get the latest insights
Subscribe to our newsletter for investment updates and expert analysis.