• Insight

Quant chart: Asian hardware stocks show big gains and big swings

The AI spending boom may be taking place in US boardrooms, but much of the action is showing up on Asian factory floors. Share-price gains have been enormous, but the journey has differed sharply from one company to the next.

Authors
    Portfolio Manager

As the largest US technology companies pour billions into AI infrastructure, much of that spending flows through Asia’s hardware supply chain. Taiwan sits at its center, with Korean companies also supplying essential memory, components and manufacturing capacity.

Share price gains and drawdowns

Across the 51 stocks shown in Figure 1, the median one-year return was 173%. Yet the median decline from a recent high was 23%. While twenty stocks gained at least 200% over the year, seven were 40% or more below their recent peaks. As our chart shows, the market still looks exceptionally strong over 12 months, but much less uniform close up.

Figure 1 | Big gains have come with very different drawdowns
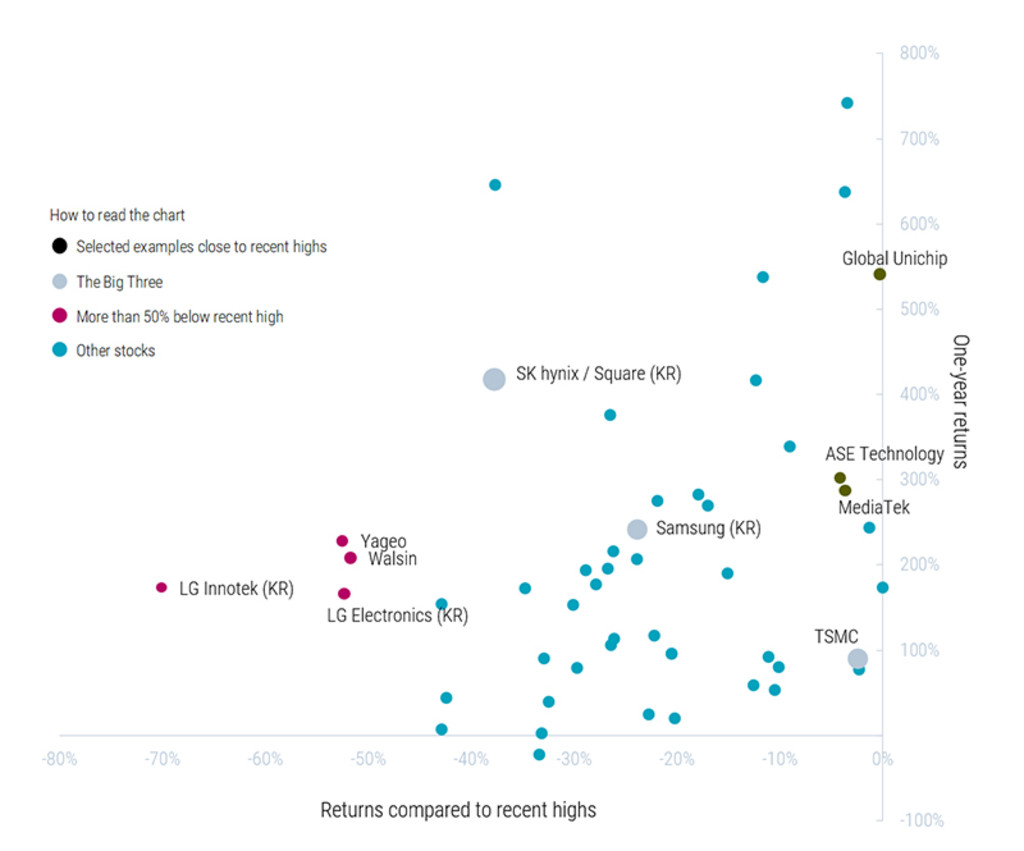
Past performance does not guarantee future results. The value of your investments will fluctuate. Companies named and shown are for illustrative purposes only. No inference can be made about their future development. This is not a buy, sell or hold recommendation. Source: Robeco analysis; Bloomberg.1 One-year share-price returns and declines from recent highs for 51 companies in the Asian AI hardware value chain. All figures as of 24 September 2026.

The scatter makes that divergence visible. MediaTek2, ASE Technology and Global Unichip, three sizable companies at the heart of the AI boom, remained within 5% of their recent highs, supported by order growth and earnings momentum. LG Innotek, LG Electronics, Yageo and Walsin were more than 50% below their peaks, despite positive one-year returns for all four.

The value chain behind the dispersion

The ten-step framework in Figure 2 helps explain the spread. AI hardware moves from chip design through foundries, memory, substrates, packaging and testing, and then into networking, power and cooling, components, boards and complete servers. Companies at each stage face different demand cycles, competitive pressures and starting valuations. Exposure to the same spending boom can therefore produce very different earnings and share-price outcomes.
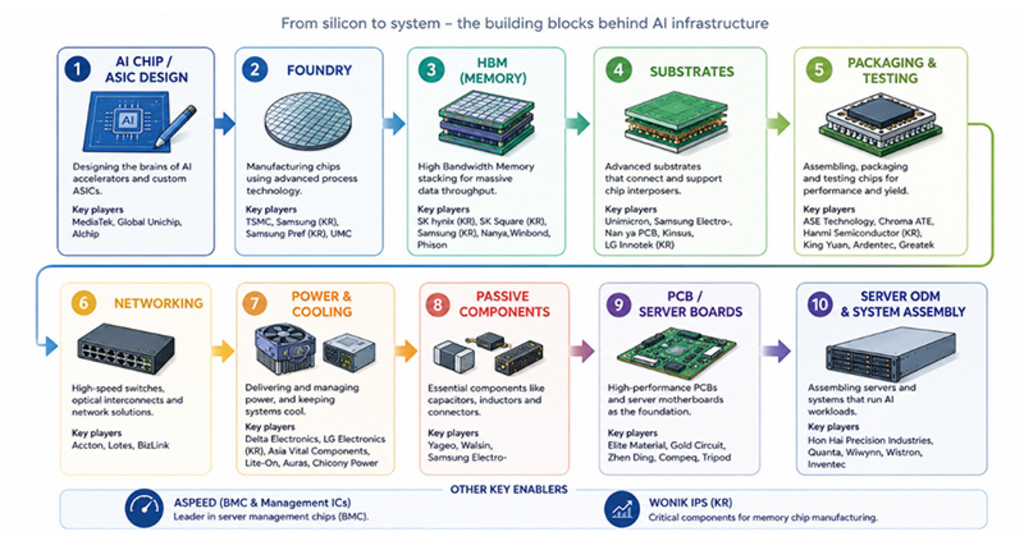
Source: Robeco. This framework is one of several possible classifications of the AI hardware value chain. It focuses on the main Taiwanese and Korean players; companies from Japan, China and the US also compete across the chain.

Why stock selection matters

For investors, identifying an AI beneficiary is only the starting point. The harder question is how much future growth the share price already reflects. A healthy AI business can still disappoint when expectations move too far ahead of earnings. Strong earnings revisions, by contrast, can support further gains after a large rally.

Robeco’s emerging markets quant strategies seek to capture these differences through many bottom-up stock-level decisions, while keeping overall country and sector exposures balanced. Indeed, so far in 2026, technology stock selection has contributed positively without an overall overweight to AI-related names.

Footnotes

1Source: The following are trademarks and service marks of Bloomberg Finance L.P., a Delaware limited partnership, or its subsidiaries: BLOOMBERG, BLOOMBERG ANYWHERE, BLOOMBERG MARKETS, BLOOMBERG NEWS, BLOOMBERG PROFESSIONAL, BLOOMBERG TERMINAL and BLOOMBERG.COM: Absence of any trademark or service mark from this list does not waive Bloomberg's intellectual property rights in that name, mark or logo. All rights reserved.
2Companies named and shown are for illustrative purposes only. No inference can be made about their future development. This is not a buy, sell or hold recommendation.
Explore our EM quant strategies

Let's keep the conversation going

Keep track of fast-moving events in sustainable and quantitative investing, trends and credits with our newsletters.

Don’t miss out

Robeco aims to enable its clients to achieve their financial and sustainability goals by providing superior investment returns and solutions.

Important information
The Robeco Capital Growth Funds have not been registered under the United States Investment Company Act of 1940, as amended, nor or the United States Securities Act of 1933, as amended. None of the shares may be offered or sold, directly or indirectly in the United States or to any U.S. Person (within the meaning of Regulation S promulgated under the Securities Act of 1933, as amended (the “Securities Act”)). Furthermore, Robeco Institutional Asset Management B.V. (Robeco) does not provide investment advisory services, or hold itself out as providing investment advisory services, in the United States or to any U.S. Person (within the meaning of Regulation S promulgated under the Securities Act).
This website is intended for use only by non-U.S. Persons outside of the United States (within the meaning of Regulation S promulgated under the Securities Act who are professional investors, or professional fiduciaries representing such non-U.S. Person investors. By clicking “I Agree” on our website disclaimer and accessing the information on this website, including any subdomain thereof, you are certifying and agreeing to the following: (i) you have read, understood and agree to this disclaimer, (ii) you have informed yourself of any applicable legal restrictions and represent that by accessing the information contained on this website, you are not in violation of, and will not be causing Robeco or any of its affiliated entities or issuers to violate, any applicable laws and, as a result, you are legally authorized to access such information on behalf of yourself and any underlying investment advisory client, (iii) you understand and acknowledge that certain information presented herein relates to securities that have not been registered under the Securities Act, and may be offered or sold only outside the United States and only to, or for the account or benefit of, non-U.S. Persons (within the meaning of Regulation S under the Securities Act), (iv) you are, or are a discretionary investment adviser representing, a non-U.S. Person (within the meaning of Regulation S under the Securities Act) located outside of the United States and (v) you are, or are a discretionary investment adviser representing, a professional non-retail investor.


Access to this website has been limited so that it shall not constitute directed selling efforts (as defined in Regulation S under the Securities Act) in the United States and so that it shall not be deemed to constitute Robeco holding itself out generally to the public in the U.S. as an investment adviser. Nothing contained herein constitutes an offer to sell securities or solicitation of an offer to purchase any securities in any jurisdiction. We reserve the right to deny access to any visitor, including, but not limited to, those visitors with IP addresses residing in the United States. This website has been carefully prepared by Robeco. The information contained in this publication is based upon sources of information believed to be reliable. Robeco is not answerable for the accuracy or completeness of the facts, opinions, expectations and results referred to therein. Whilst every care has been taken in the preparation of this website, we do not accept any responsibility for damage of any kind resulting from incorrect or incomplete information. This website is subject to change without notice. The value of the investments may fluctuate. Past performance is no guarantee of future results. If the currency in which the past performance is displayed differs from the currency of the country in which you reside, then you should be aware that due to exchange rate fluctuations the performance shown may increase or decrease if converted into your local currency. For investment professional use only. Not for use by the general public.