Head of Credits

• Fixed Income Quarterly Outlook
Higher bond yields in an era of abundant supply
Higher yields have strengthened the case for fixed income, even as abundant bond supply, inflation and tight spreads complicate the outlook. Our first integrated Fixed Income Quarterly Outlook brings together Robeco’s macro, rates and credit views to explore where opportunities remain and why selectivity matters.
Authors

Head of Global Macro and Portfolio Manager
CIO High Yield, Portfolio Manager
Head of Emerging Markets Debt
Summary
- High starting yields provide a strong base for future fixed income returns
- Higher rates are increasing pressure on risk assets and leveraged borrowers
- AI investment and rising issuance are reshaping fixed income markets
AI is usually discussed as a technology or equity market story. For fixed income investors, however, it is increasingly becoming a supply story. Consensus expectations for hyperscaler capital expenditure in 2027 now exceed USD 1 trillion, while expected bond issuance from the largest technology companies has risen sharply as more of that investment is financed through debt.
The funding requirement also extends well beyond the hyperscalers. Data centers require a substantial and reliable supply of electricity, drawing utilities and grid operators into the same investment cycle. As this infrastructure expands, financing needs are spreading across the wider AI ecosystem.
Higher yields have strengthened the case for fixed income, but this is not a market for large directional bets
Understanding fixed income
Fixed income forms the stable core of a portfolio, providing regular income and capital return.
This new corporate borrowing arrives at a time when governments and supranational issuers already have substantial funding requirements. Fiscal deficits remain large and sovereign issuance is elevated, while public investment needs are growing. This means governments, technology companies and utilities are increasingly competing for the same pool of long-term capital.
This represents a reversal from recent years, when companies borrowed less, shortened maturities and reduced net issuance in response to higher rates. Limited bond supply, combined with persistent investor demand, provided powerful technical support for credit spreads. That scarcity is now giving way to greater bond abundance.
For investors, greater supply is not simply a risk. It should also create more choice and potentially better entry points into high-quality issuers. But it strengthens the case for active selection across sectors, maturities and currencies rather than relying on scarcity to keep spreads compressed.
Table 1 - Fixed income views at a glance
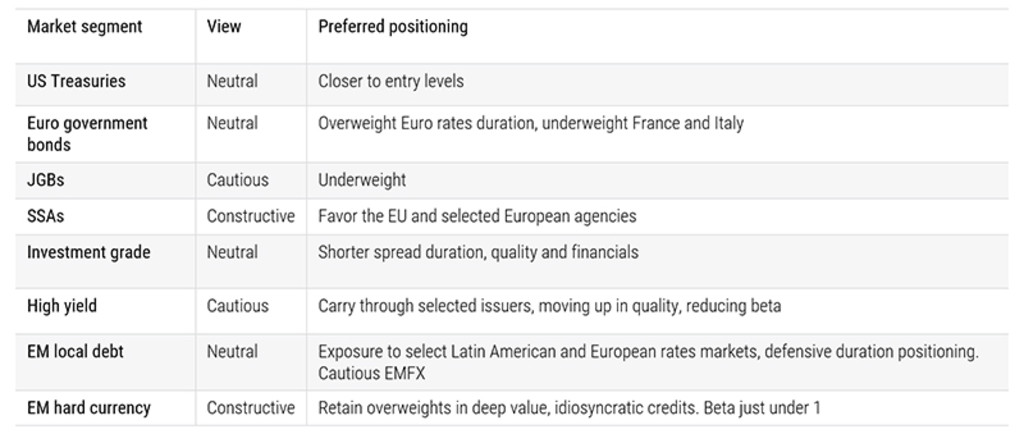
For illustrative purposes only. This is the current overview as of the date stated above and not a guarantee of future developments. It should not be assumed that any investments in sectors/markets/regions/themes/market cap/country identified were or will be profitable.
Source: Robeco, October 2026
For our detailed views on rates, credit and emerging market debt, including the developments that could make us more constructive, read the full Fixed Income Quarterly Outlook, or explore the key messages and positioning implications in Fixed Income Quarterly Outlook in Brief.
What’s new in credits?
Stay ahead with our newsletter on the latest in credit investing.